Talk to an Expert
Talk to an Expert ✆ +91 945 945 6700
Trusted by 10,000+ Businesses

ESOP Accounting Under Ind AS 102

Reviewed by CA and CS Team, Patron Accounting LLP ICAI & ICSI Registered| 15+ Years Experience| Last Updated: July 2026 Verify Credentials →

Grant-wise charge tied to the register: Each period's employee benefits expense traces back to individual grants, so the charge is never just a scheme-level total.

Graded vesting charged correctly: Each tranche of a graded-vesting grant is a separate arrangement, so the cost lands front-loaded rather than spread evenly.

Modifications with a documented treatment: Each repricing, extension, acceleration, cancellation and lapse carries its own working, with incremental fair value spread over remaining vesting.

Deferred tax computed alongside: You get deferred tax on options measured at each reporting date, because the book charge and tax deduction land in different years.

15+ YearsIndustry Experience
CA & CSCertified Experts
4.9
Based on real Google reviews

Get Free Consultation

Talk to a CA/CS expert today

🇮🇳 +91

    Our team will get back to you shortly. No spam.

    Real Stories from Real People

    Verified Google reviews from founders and businesses Patron works with across India.

    Sunny Ashpal
    Sunny Ashpal
    Director - Demandify Media
    Google
    Anjanay Srivastava
    Anjanay Srivastava
    Founder - Hunarsource Consulting
    Google
    Mayur Shewale
    Mayur Shewale
    Founder - Bijasani Traders
    Google
    Ascendancy International
    Ascendancy International
    Owner
    Google

    I've had an outstanding experience working with my CA - Patron Accounting. Their professionalism, attention to detail, and timely communication made the entire process seamless and stress-free.

    I'm glad that I was able to connect with Patron. They took the minimum time to do the calculations based on the details provided by me and were really helpful throughout the process.

    Really a fantastic experience with Patron Accounting especially Shubham, he was extremely great. Knowledgeable person who deserves the 5 star for smooth handling of all documentation.

    Patron Accounting gives the best service related to all account handling of our firm. I am blessed and extremely happy that Patron Accounting assigned us a dedicated point of contact.

    I have called Patron to file ITR for my 5 family members. I worked with Shubham Junjunwala and Amin Jain. It was a smooth process. They understand basics very well and respond promptly.

    From the very beginning, their approach has been highly professional, prompt, and solution-oriented. Every interaction reflected their deep knowledge and commitment to helping clients.

    Very proficient and professional staff. Do fantastic job and instant response. Strongly recommended engaging them for all accounting needs specially for startups and growing businesses.

    I contacted them to file the ITR. Shubham was the POC for me and he was really very professional and giving prompt responses. Highly recommend them for tax and compliance work.

    Join 3,000+ Founders and Businesses on Patron

    Rated 4.9 on Google - trusted for startup accounting since 2019.

    Talk to an Expert
    10,000+Businesses ServedGST compliance and litigation support across India.
    15+Years ExperienceDeep expertise in IP registration, GST & business compliance.
    50,000+Documents FiledReturns, appeals, and filings handled accurately.
    4.9★Client RatingTrusted by entrepreneurs, startups, and growing businesses.
    ISO CertifiedProfessional standards and documented processes.
    SSL SecureYour financial and business data is fully protected.

    What ESOP Accounting Covers — Scope, Deliverables and Who It Suits

    📌 TL;DR - ESOP Accounting Services at a Glance

    Ind AS 102 requires share-based payments to be expensed at grant-date fair value across the vesting period, not at exercise. The grant-wise charge for graded and cliff vesting is computed by Patron, with valuation inputs documented and the disclosures an auditor will test prepared in advance. Perquisite TDS on exercise is calculated alongside the accounting entry. Common among companies running ESOP pools from seed stage to pre-IPO.

    The ESOP register usually sits in a spreadsheet while the books sit in the accounting software, and the two drift apart the moment someone resigns mid-vesting. Patron works from the grant register itself, rebuilds it where it has gaps, and posts the charge and the corresponding reserve into your ledger each period with a working that ties every figure to the individual grant it came from. How share-based payments are expensed covers the mechanics.

    Across every tranche granted since the pool opened, the workings must hold. ESOP accounting gets heavier with each tranche, modification, repricing or cancellation, not with headcount. Expense workings, journal entries and disclosure notes sit in scope. Independent valuation of shares does not, and is handled under a separate assignment, as is any technical opinion referred to the Institute of Chartered Accountants of India.
    What Is ESOP Accounting?

    Ind AS 102 is the accounting standard that governs how a company records share-based payments, including employee stock options. ESOP accounting is the service that applies that standard to your scheme. It measures each grant at its grant-date fair value and spreads that charge across the period an employee must serve before the options vest. The charge is recognised whether the options are ultimately exercised or lapse unexercised.

    This service posts the resulting expense and the matching reserve into your ledger, grant by grant, and prepares the disclosures an auditor will later test. It reads the valuation an independent registered valuer supplies rather than producing that figure itself. Perquisite tax due when options are exercised is computed alongside the entry, and modifications, forfeitures and cancellations are reflected as they occur. Ind AS 102 work of this kind covers the numbers and the notes; the share valuation and any tax return remain separate assignments.

    Key Terms for ESOP Accounting:

    What Is ESOP Accounting. Ind AS 102 is the accounting standard that governs how a company records share-based

    Who Needs ESOP Accounting in India?

    ESOP accounting under Ind AS 102 is for companies that have granted share options and now must expense them. Once a scheme is live and the first tranches vest, the businesses below carry a charge to compute grant by grant.

    • Venture-backed startups running an ESOP pool from seed stage, with grants now needing a fair-value charge.
    • Companies whose graded or cliff vesting schedules must be charged across each vesting period.
    • Firms that have repriced, modified or cancelled option grants part-way through vesting.
    • Businesses where the ESOP register in a spreadsheet has drifted from the entries in the ledger.
    • Pre-IPO companies facing diligence that ties the employee benefit charge back to the grant register.
    • Companies computing perquisite TDS on exercise alongside the share-based payment entry.
    • Unlisted companies moving to Ind AS reporting that must restate earlier option grants.
    • Firms with deferred tax on the ESOP charge still to compute and disclose.

    Our ESOP Accounting Services

    ServiceWhat We Do
    Grant-date fair valuation reviewGrant data collected and the valuation report read, fixing grant-date fair value used for share based payment accounting On event / as needed
    Vesting schedule and expense chargeVesting schedule built and the Ind AS 102 charge spread as ESOP expense over the vesting period, with true-up Quarterly
    Modifications, forfeitures and exercisesScheme modifications, forfeitures and exercises accounted with a documented treatment for each event that arises during the year On event / as needed
    Deferred tax computationDeferred tax on the ESOP charge computed alongside the accounting entries, keeping esop accounting and tax in step Annually
    Payroll interface supportExercise-date fair value and quantities handed to payroll on time, supporting perquisite computation without giving employee tax advice On event / as needed
    Disclosures and audit fileRoll-forward note, reserve movement and standard disclosures prepared, with an esop advisory review ready for the audit Annually
    Our Process

    How ESOP Accounting Works — Our Process

    How Patron delivers esop accounting, step by step from onboarding to a clean monthly close.

    Step 1

    Scheme and grant data collection

    We collect the scheme document, board and shareholder approvals and every grant letter. From those we build a grant-wise register: grant date, number of options, exercise price, vesting conditions and employee identity. The accounting is done per grant, not per scheme.

    Illustration for Scheme and grant data collection: We collect the scheme document, board and shareholder approvals and every
    Step 2

    Reading the valuation report

    Fair value at grant date is taken from the registered valuer's report; we do not perform the valuation. We review the inputs and check that the model, the grant dates and the option terms in the report agree to the grant register before the numbers are used.

    Illustration for Reading the valuation report: Fair value at grant date is taken from the registered valuer's report; we do
    Step 3

    Building the vesting schedule

    Each vesting tranche of a graded-vesting grant is treated as a separate arrangement with its own vesting period, so the charge is front-loaded rather than straight-lined across the whole grant. Service, performance and market conditions are separated at this stage.

    Illustration for Building the vesting schedule: Each vesting tranche of a graded-vesting grant is treated as a separate
    Step 4

    Expense charge and true-up

    The grant-date fair value is charged to employee benefits expense over each tranche's vesting period with the credit in a share-based payment reserve within other equity. Estimates of how many options will vest on non-market conditions are revised at each reporting date.

    Illustration for Expense charge and true-up: The grant-date fair value is charged to employee benefits expense over each
    Step 5

    Modifications, forfeitures and exercises

    Repricing, extension, acceleration, cancellation and lapse each have their own treatment, and incremental fair value on a modification is charged over the remaining vesting period. Exercises move the reserve to share capital and securities premium; expired options are transferred within equity.

    Illustration for Modifications, forfeitures and exercises: Repricing, extension, acceleration, cancellation and lapse each
    Step 6

    Deferred tax and payroll interface

    Because the accounting charge and the tax deduction arise in different periods, we compute the deferred tax position at each reporting date and split any excess to equity. We also give payroll the exercise-date data it needs for perquisite valuation and withholding.

    Illustration for Deferred tax and payroll interface: Because the accounting charge and the tax deduction arise in different
    Step 7

    Disclosures and audit file

    We draft the note: nature and terms of each scheme, the options roll-forward from opening to closing with weighted average exercise prices, valuation model and inputs, and the total expense recognised. The supporting working papers go to the auditor as one file.

    Illustration for Disclosures and audit file: We draft the note: nature and terms of each scheme, the options roll-forward
    Client Portal

    How You Work With Patron

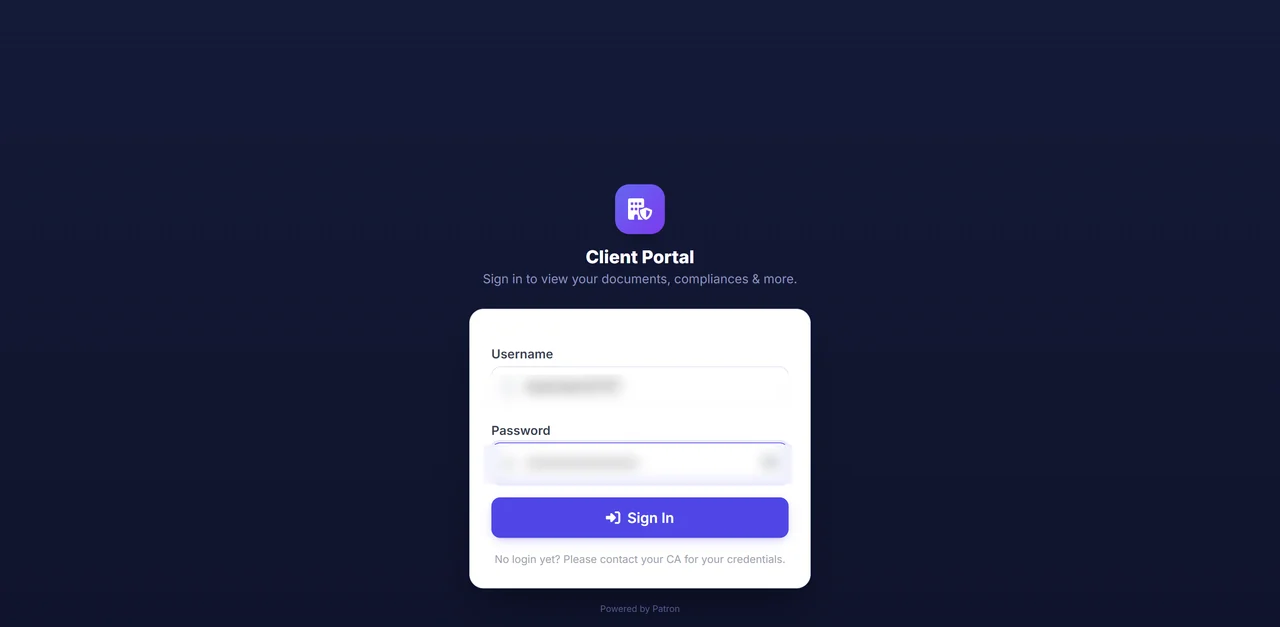
    Everything happens in one secure login. You can see your active services, the Patron team on your account, and anything still pending. Once you raise a request, it moves through the same clear steps every time, so you always know exactly where your work stands.

    Secure client portal login screen
    1

    Sign in securely

    Your books, documents and requests all sit behind one private, password protected login. The team handling your account is shown on screen, so nothing sensitive ever needs to travel over email or WhatsApp.

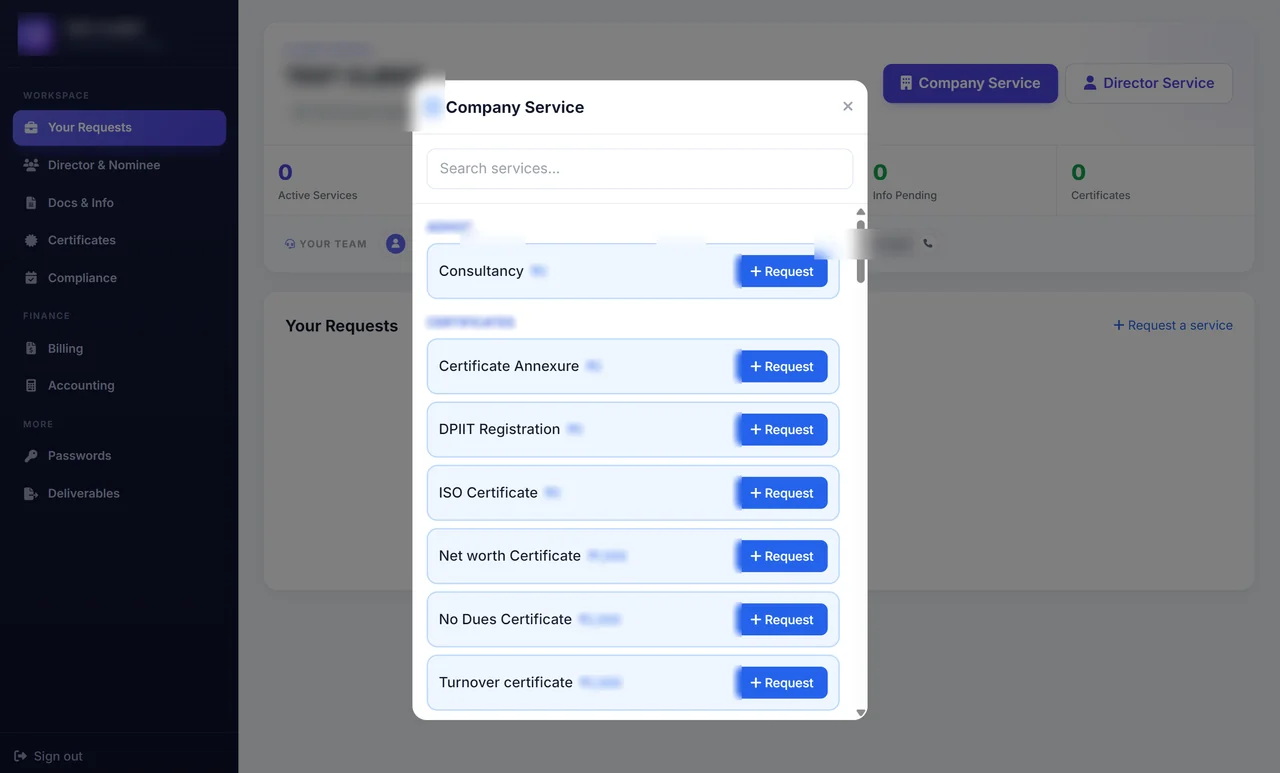
    Service catalogue inside the client portal
    2

    Raise your request

    Choose the service you need from the menu inside the portal, where the price is shown before you go ahead. Your request is logged the moment you send it, with no phone calls or reminder emails to wait on.

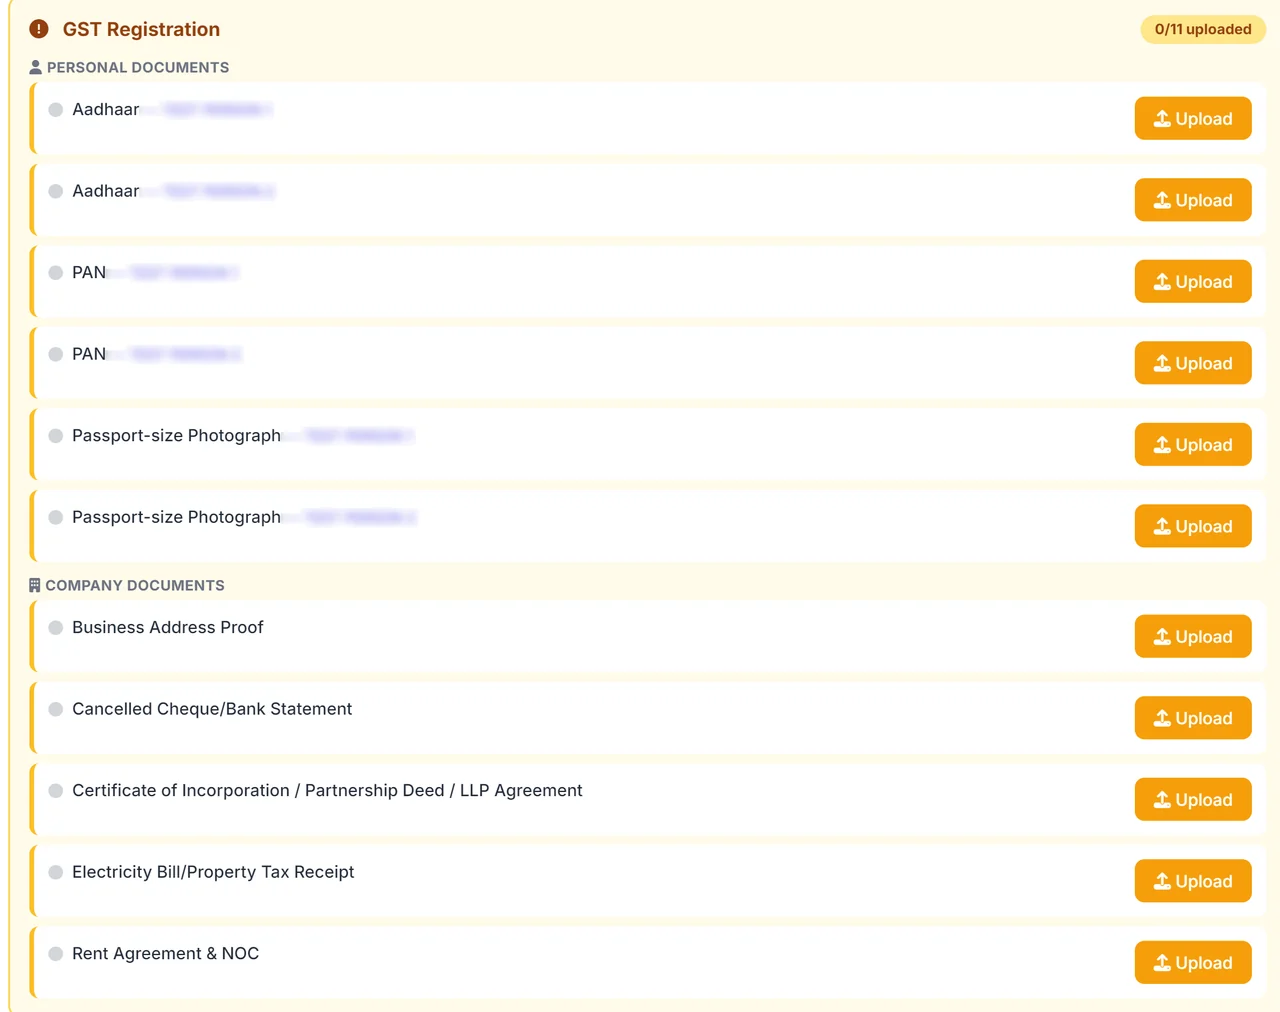
    GST registration document checklist in the client portal, with an upload button beside each item
    3

    Share what the service asks for

    For every service, the portal lists the exact documents it needs, each with its own upload button. The example shown here is the GST registration checklist. When a service needs nothing from you, it simply asks for nothing.

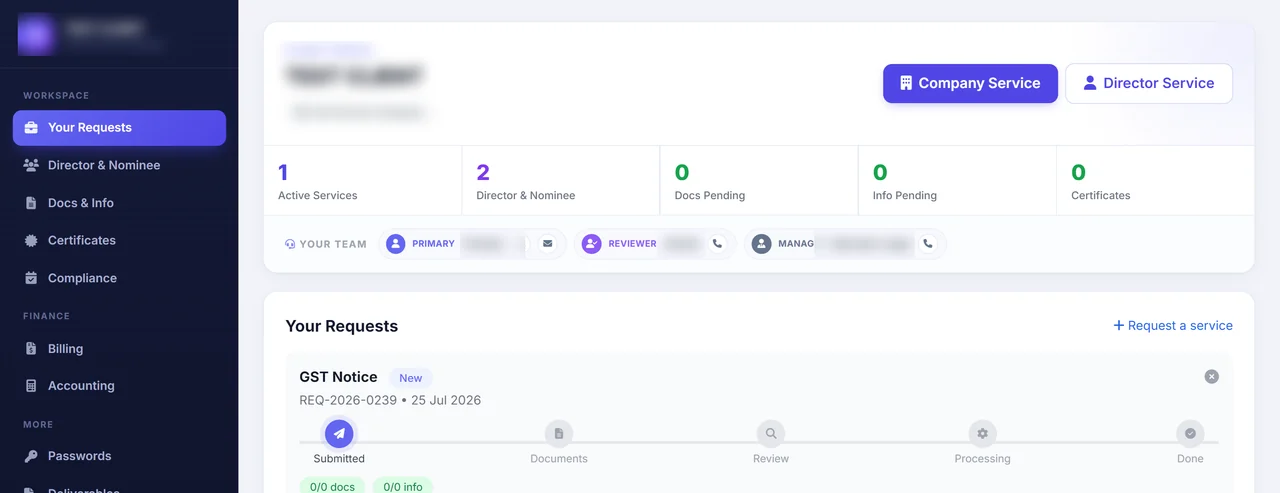
    Live request tracker inside the client portal
    4

    We review, prepare and file

    Once your documents are in, your team checks them, prepares the work and files it for you. A live tracker shows each stage as it happens, from review to processing to done, so you never have to ask where things stand.

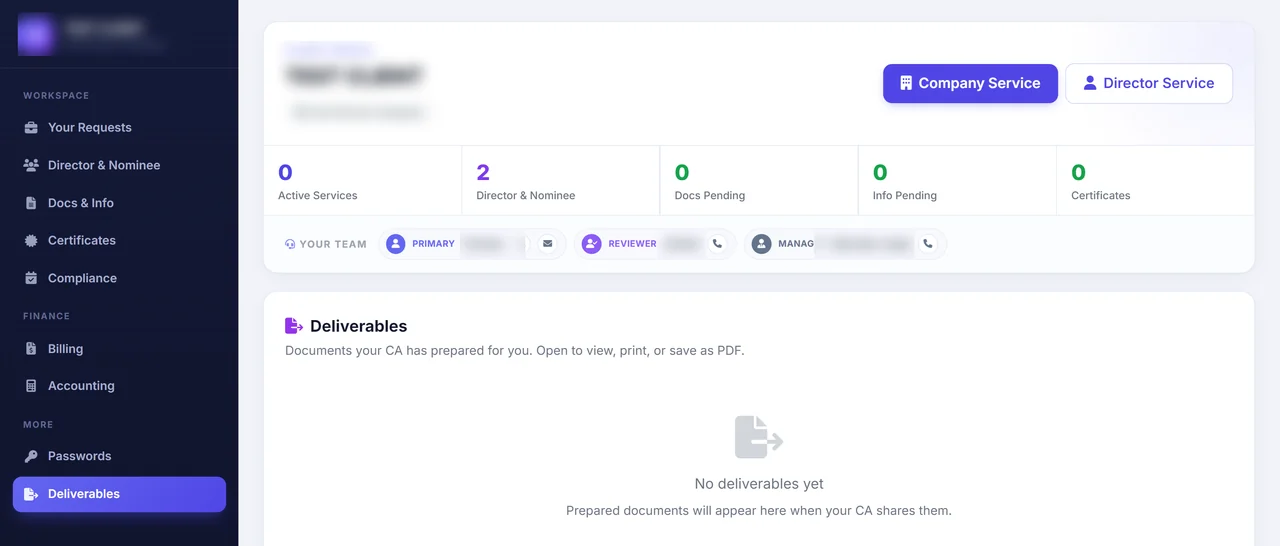
    Deliverables area of the client portal
    5

    Collect your finished work

    Every completed return, computation and certificate is placed in your Deliverables area. You can open, print or download any of them as a PDF whenever you need a copy.

    Common ESOP Accounting Challenges and How We Solve Them

    ChallengeImpactHow Patron Accounting Solves It
    Employees resign mid-vesting, but the expense is never trued upShare-based cost stays booked for options that will never vest, overstating expense and understating profit.Patron trues up the forfeiture at each reporting date, reversing cost for unvested options; see how Ind AS 102 works.
    Repriced or modified grants skip the incremental fair-value chargeA repricing that raises award value goes unrecorded, understating expense until an auditor catches it.We apply modification accounting, measuring incremental fair value at the change and spreading it over remaining vesting.
    Deferred tax on share-based expense left uncomputedThe timing difference between book expense and tax deduction is missed, misstating deferred tax assets.Patron computes deferred tax on the ESOP charge, tracking the temporary difference to the exercise event.
    Cash-settled SARs treated like equity-settled optionsA cash-settled award is a liability that must be remeasured, so profit and liabilities both mislead.Our team classifies cash-settled SARs as a liability and remeasures fair value at each reporting date.
    Options granted to a subsidiary's employees hit the wrong entityGroup share-based cost lands in the parent alone, distorting each company's standalone results.Patron allocates the group share-based charge and books a recharge, so each entity carries its own cost.

    ESOP Accounting Fees

    Fee ComponentAmount
    Scoped engagement — a single entity at routine share-based-payment volumeOn quote
    Excl. GST & Government Charges

    ESOP accounting under Ind AS 102 is scoped per engagement, since grant structures, vesting terms and valuation inputs differ widely. What sets the fee is the scope of work: number of schemes, tranches and whether fair-value support is needed. Book a scope call on +91 94594 56700.

    Fees exclude GST and government charges. Final quote confirmed after a scoping review.

    All fees and charges listed are indicative only and do not constitute a binding offer. Final amounts may vary depending on the volume of work and the complexity involved.

    Professional accounting and compliance charges are scoped to your number of entities, funding stage and monthly transaction volume, and are separate from statutory and government charges. Contact us for a detailed, fixed quote.

    Get a free ESOP Accounting consultation - Call +91 945 945 6700 or WhatsApp us. No-obligation assessment.

    ESOP Accounting Compliance Calendar 2026

    ComplianceDue DateApplies To
    TDS / TCS deposit (Challan ITNS-281)7th of every month (30 April for March)Every business that deducts tax at source on salaries, rent, contractor or professional fees
    ESOP perquisite TDS deposit on allotment7th of the month after allotmentEmployers allotting shares under an approved ESOP
    Advance tax first instalment (15%)15 June 2026Companies, firms and individuals with a tax liability of Rs 10,000 or more
    Tax audit report (Form 3CA/3CB-3CD)30 September 2026Businesses crossing the Section 44AB turnover threshold
    Income-tax return, audit cases31 October 2026Companies and audit-liable firms
    Financial statements filing (Form AOC-4)Within 30 days of the AGM (by 29 October 2026 for a 30 September AGM)Companies filing audited financials with the ROC
    IND AS 102 / share-based payment disclosure at year-endWith the annual financial statementsCompanies running equity-settled ESOP schemes

    For ESOP accounting the live date is the perquisite TDS on the 7th of the month after allotment. The IND AS 102 charge is then disclosed at year-end and carried into the audit-case ITR on 31 October. Patron handles ESOP perquisite tax and fair-value entries together. Download the 2026 calendar or talk to a CA on +91 94594 56700.

    Key Benefits

    Why Professional ESOP Accounting Matters

    Grant-wise charge tied to the register

    Each period's employee benefits expense traces back to individual grants, so the charge is never just a scheme-level total.

    • Grant date, option count, exercise price and vesting conditions held per grant
    • Without it, no one can attribute the charge once the owner leaves

    Graded vesting charged correctly

    Each tranche of a graded-vesting grant is a separate arrangement, so the cost lands front-loaded rather than spread evenly.

    • Each tranche carries its own vesting period and charge
    • Straight-lining understates the early years of the grant
    • Without it, correcting later restates comparatives investors have already seen

    Modifications with a documented treatment

    Each repricing, extension, acceleration, cancellation and lapse carries its own working, with incremental fair value spread over remaining vesting.

    • Incremental fair value spread over the remaining vesting period
    • Without it, a board decision lands as an unexplained movement in other equity

    Deferred tax computed alongside

    You get deferred tax on options measured at each reporting date, because the book charge and tax deduction land in different years.

    • Excess relief taken to equity, not to profit
    • Without it, a late audit adjustment changes reported profit after circulation

    Payroll given exercise-date data

    Payroll receives the exercise-date figures it needs to value the perquisite, taken from the same register that drives the charge.

    • Perquisite valued and withheld from the same grant register
    • Without it, employees meet an unexpected perquisite withholding on their salary slip

    Roll-forward note ready for audit

    You can show which assumptions produced last year's share-based payment note, because we wrote the papers while the decision was fresh.

    • Assumptions behind the share-based payment note documented when made
    • Without it, last year's assumptions are recalled from memory a year later

    Why Businesses Choose Patron Accounting for ESOP Accounting (Ind AS 102)

    Five things a founder can check before handing over the books. Each is a claim with the proof behind it.

    Grant-wise fair value and graded vesting, computed and documented

    ESOP accounting turns on the fair value of each grant. We compute grant-wise fair value and map graded vesting schedules, documenting the workings, and we set out fair value versus intrinsic value so the basis is defensible.

    Ind AS 102 expense recognition and perquisite TDS on exercise

    We handle Ind AS 102 expense recognition across the vesting period and the perquisite TDS due when employees exercise. With 25,000+ filings completed, this measurement and the payroll data behind it are routine for our team.

    Option register reconciled to the share register and cap table

    We reconcile your option register to the share register and cap table, then post the charge in whichever ledger you keep, Zoho Books, Xero, Tally Prime or Odoo. Modifications and cancellations are tracked with a documented treatment.

    Vesting-period charge computed each quarter, audit-ready

    Each quarter we compute the vesting-period charge and hand you an audit-ready roll-forward note. Our blog shows how ESOP expense is spread over vesting, and the 4.9 star Google rating reflects clients whose auditors accepted the workings.

    ESOP pools among 3,000+ businesses served

    ESOP pools, from seed-stage startups to pre-IPO companies, sit among the 3,000+ businesses we have served since 2019. Behind the measurement stand 15+ years, our in-house team of CAs and CS, and a 4.9 star Google rating.

    Figures reflect Patron Accounting LLP engagements since 2019. Scope and turnaround are confirmed in your engagement letter.

    Intrinsic Value Method vs Fair Value Method

    CriterionIntrinsic Value MethodFair Value Method
    What the method isCharge based on market price less exercise price at grantCharge based on option fair value using a valuation model
    Permitted under Ind AS 102Not permitted for expense recognition, save rare unmeasurable casesThe mandatory method for share-based payment expense
    Expense recognitionUnderstates or omits time value, often a lower chargeCaptures time value, spread over the vesting period
    Compliance and tax impactRisks non-compliant financials and audit qualification for Ind AS filersAligns book charge with the standard, cleaner audit position
    MIS and financial clarityMay flatter early profits, understates true employee costReflects the genuine cost of options in the accounts
    Valuation effortSimple to compute, no option pricing model neededNeeds an option pricing model such as Black Scholes
    VerdictUnder Ind AS 102 the fair value method is mandatory for ESOP expense recognition. Intrinsic value is not permitted except where fair value cannot be measured reliably. Follow the standard, not preference. Read fair value versus intrinsic value.

    Legal and Regulatory Framework for ESOP Accounting

    ESOP numbers are kept to Ind AS 102, and that standard is made binding through the Companies Act's requirement that the financial statements be true and fair. The standard treats an option granted to an employee as a cost of their service, so a scheme that pays nothing in cash still leaves a charge in the profit and loss.

    The framework then splits into two clocks that rarely align: the accounting charge spread over the vesting period and the tax event that lands only on exercise. That is why Vesting Period Graded Amortization governs the books while a separate perquisite arises for the employee, and why the choice against an ESOP Intrinsic Value Method matters for what gets disclosed. ESOP accounting keeps both clocks and the disclosures aligned against the provisions below.

    • Ind AS 102, Share-based PaymentThe fair value of options at grant is charged to profit and loss over the vesting period, with graded vesting recognised tranche by tranche - the heart of Ind AS 102 Share-based Payment. Companies on AS instead follow ICAI's Guidance Note on Accounting for Share-based Payments (revised 2020).
    • Section 17(2)(vi) with Rule 3(8), Income-tax Act 1961The gap between fair market value on exercise and the exercise price is a perquisite in the employee's hands, with TDS deducted under Section 192.
    • Section 192(1C)/191(2), Income-tax Act 1961An eligible startup may defer the perquisite TDS to the earliest of five years, sale, or exit, easing the employee's cash position.
    • Schedule III with the Guidance Note on Share-based PaymentsThe outstanding options, weighted exercise price and the year's charge are disclosed in the notes to accounts.
    • Companies (Accounting Standards) Rules 2021 and Companies (Indian Accounting Standards) Rules 2015The standard that applies follows the company's framework, with Ind AS 102 binding once the company is on Ind AS.
    • Section 128, Companies Act 2013The books carrying the charge stay on accrual and double entry, retained for eight years. A neglected scheme is first rebuilt through catch-up bookkeeping.

    Practical note: the perquisite TDS on exercise is the step most often missed, because the accounting charge under Ind AS 102 and the tax event fall in different periods.

    Official sources: Ministry of Corporate Affairs · Income Tax Department · GST Portal · Startup India (DPIIT)

    How is ESOP cost calculated and recognised under Ind AS 102?

    Under Ind AS 102 the ESOP cost equals the grant date fair value of the options multiplied by the number of options expected to vest, charged to the profit and loss across the vesting period with a matching credit to a share based payment reserve within equity. For equity settled awards the grant date fair value is never remeasured in later periods.

    What is a vesting condition as per Ind AS 102?

    A vesting condition under Ind AS 102 is a condition an employee must satisfy to become entitled to the option, and it is either a service condition or a performance condition. Service conditions and non market performance conditions are reflected by revising the number of options expected to vest at each reporting date. Market conditions are built into the grant date fair value and are never trued up.

    Is a valuer needed for ESOP fair value, and which model is used?

    Fair value is normally determined by a registered valuer or merchant banker using an option pricing model, most often Black Scholes for plain vanilla options and a binomial or lattice model where performance conditions or early exercise behaviour exist. The inputs are exercise price, share fair value, expected volatility, risk free rate, expected life and expected dividend yield, and each must be documented.

    What does ESOP mean?

    ESOP stands for Employee Stock Option Plan, a scheme under which a company grants employees the right to buy its shares at a fixed exercise price once a vesting period is completed. In India the issue is governed by Section 62(1)(b) of the Companies Act 2013 read with Rule 12 of the Companies (Share Capital and Debentures) Rules 2014, and the accounting charge follows Ind AS 102.

    What entries are passed when options are granted, vested, exercised and lapsed?

    No entry is passed at grant. During vesting, employee benefits expense is debited and the share based payment reserve is credited each period. On exercise, bank and the reserve are debited while share capital and securities premium are credited. Where vested options lapse unexercised, the reserve is transferred to general reserve or retained earnings rather than reversed through profit.

    Can ESOPs be given to advisors?

    No, an outside advisor or consultant cannot be granted ESOPs, because the Companies Act permits options only to permanent employees and directors of the company and of its holding, subsidiary or associate companies. Advisors are usually compensated instead through sweat equity shares, warrants or a cash settled plan. Where an advisor is formally appointed a director, options become possible and the charge still follows Ind AS 102.

    What happens in the books when an employee leaves before vesting?

    Options that lapse before vesting because the employee resigns are reversed, so cumulative expense already charged is written back in the year the forfeiture occurs and only vested options continue to carry cost. Options lapsing after vesting are not reversed through the profit and loss. Because the vesting estimate is revised at every reporting date, the attrition assumption is a live number.

    What ESOP disclosures are required in financial statements?

    Financial statements must disclose the nature and terms of each scheme, options outstanding, granted, exercised, forfeited and expired during the year, weighted average exercise price and remaining contractual life, the valuation model with its inputs, and the total expense recognised. Scheme details are also reported to shareholders and the relevant MCA forms are filed when shares are issued on exercise.

    Does the ESOP expense reduce taxable income?

    The Ind AS 102 charge is a book expense, while the deduction under the Income Tax Act is generally the discount actually borne by the company and is claimed in the year of exercise rather than across the vesting period. That mismatch creates a timing difference and a deferred tax asset. Because case law has shifted on this point, the position is confirmed before filing.

    What does an ESOP accounting engagement involve and how long does it take?

    A first time Ind AS 102 setup takes 2 to 3 weeks and covers scheme document review, grant register build, valuation coordination, the vesting period expense schedule, deferred tax working and draft disclosures for the financial statements. Quarterly upkeep afterwards is lighter. Effort depends on the number of grant tranches and whether subsidiary or overseas employees are covered.

    Quick Answers

    The ESOP register usually sits in a spreadsheet while the books sit in the accounting software, and the two drift apart the moment someone resigns mid-vesting. Patron works from the grant register itself, rebuilds it where it has gaps, and posts the charge and the corresponding reserve into your ledger each period.

    ESOP Accounting Deadlines You Cannot Afford to Miss

    TDS / TCS deposit (Challan ITNS-281) is due 7th of every month (30 April for March). ESOP perquisite TDS deposit on allotment is due 7th of the month after allotment. Advance tax first instalment (15%) is due 15 June 2026. Patron tracks each against your books so nothing is reconstructed after the fact. Call +91 94594 56700 to set up a filing-reminder schedule.

    Start Your ESOP Accounting with Patron Accounting

    Boards approve fresh grants while earlier tranches remain uncosted, and the finance team then rebuilds a full year of vesting in the fortnight before the audit. That work is done twice: once badly under pressure, once properly when Ind AS 102 workings are questioned. The cost is senior time, taken at the worst moment.

    Diligence on a funding round reaches the cap table quickly, and the question that follows is whether the reported employee benefit charge reconciles to the grant register. With the ESOP accounting already assembled tranche by tranche and the assumptions written down, that thread closes in one exchange rather than a reconstruction exercise.

    Your scheme document is where this starts, together with the grant letters actually issued under it. Dates, exercise price, vesting conditions, and any grants made in a predecessor entity. Those facts set the charge, and older periods may need books brought up to date.

    Book a Free Consultation - No Obligation.

    Explore Our Accounting Services

    Related services our CA-led team delivers for businesses across India.

    Reviewed by the CA & CS Team, Patron Accounting LLP
    ICAI & ICSI registered  ·  15+ years in Indian accounting & compliance  ·  Last reviewed 23 July 2026  ·  Next review 23 October 2026