Talk to an Expert
Talk to an Expert ✆ +91 945 945 6700
Trusted by 10,000+ Businesses

GSTAT Appeal Filing: Resolve Conflicting GST Rulings at GSTAT

Reviewed by CA and CS Team, Patron Accounting LLP ICAI & ICSI Registered| 15+ Years Experience| Last Updated: 16 March 2026 Verify Credentials →

Disputes Covered: Demand orders, ITC reversals, penalty disputes, refund rejections

Pre-Deposit: 10% of disputed tax under Section 112(8) CGST Act - capped at Rs 20 crore

Deadline: 3-month limitation from order date under Section 112(1) CGST Act 2017

Specialist: GSTAT matters supported by Subham Jhunjhunwala - CA Finalist, Accounting & Tax Professional

10,000+ Businesses Served | 4.9 Google Rating | GSTAT Appeal Support by Patron Accounting

15+ YearsIndustry Experience
CA & CSCertified Experts
4.9
Based on 500+ reviews

Get Free Consultation

Talk to a CA/CS expert today

🇮🇳 +91

    Our team will get back to you shortly. No spam.

    Real Stories from Real People

    Hear how teams across industries use Patron to save time, cut costs, & stay in control.

    Sunny Ashpal
    Sunny Ashpal
    Director - Demandify Media
    Google
    Anjanay Srivastava
    Anjanay Srivastava
    Founder - Hunarsource Consulting
    Google
    Mayur Shewale
    Mayur Shewale
    Founder - Bijasani Traders
    Google
    Ascendancy International
    Ascendancy International
    Owner
    Google

    I've had an outstanding experience working with my CA - Patron Accounting. Their professionalism, attention to detail, and timely communication made the entire process seamless and stress-free.

    I'm glad that I was able to connect with Patron. They took the minimum time to do the calculations based on the details provided by me and were really helpful throughout the process.

    Really a fantastic experience with Patron Accounting especially Shubham, he was extremely great. Knowledgeable person who deserves the 5 star for smooth handling of all documentation.

    Patron Accounting gives the best service related to all account handling of our firm. I am blessed and extremely happy that Patron Accounting assigned us a dedicated point of contact.

    I have called Patron to file ITR for my 5 family members. I worked with Shubham Junjunwala and Amin Jain. It was a smooth process. They understand basics very well and respond promptly.

    From the very beginning, their approach has been highly professional, prompt, and solution-oriented. Every interaction reflected their deep knowledge and commitment to helping clients.

    Very proficient and professional staff. Do fantastic job and instant response. Strongly recommended engaging them for all accounting needs specially for startups and growing businesses.

    I contacted them to file the ITR. Shubham was the POC for me and he was really very professional and giving prompt responses. Highly recommend them for tax and compliance work.

    Join 10,000+ Satisfied Businesses

    10,000+ Businesses Served | 4.9 Google Rating | GSTAT Appeal Support by Patron Accounting

    Talk to an Expert
    10,000+Businesses ServedGST compliance and litigation support across India.
    15+Years ExperienceDeep expertise in IP registration, GST & business compliance.
    50,000+Documents FiledReturns, appeals, and filings handled accurately.
    4.9★Client RatingTrusted by entrepreneurs, startups, and growing businesses.
    ISO CertifiedProfessional standards and documented processes.
    SSL SecureYour financial and business data is fully protected.

    GSTAT Appeal Filing in India - Overview

    TL;DR: GSTAT appeal filing under Section 112 CGST Act 2017 requires a 10% pre-deposit of disputed tax (capped at Rs 20 crore under CGST), filed electronically via Form GST APL-05 on efiling.gstat.gov.in within 3 months of the appellate order. Pre-deposit triggers automatic stay of recovery under Section 112(9). Backlog appeals must be filed by 30 June 2026.

    ParameterDetails
    Governing LawSection 112, Central Goods and Services Tax Act, 2017
    Pre-Deposit10% of disputed tax under Section 112(8) - capped at Rs 20 crore CGST
    Time Limit3 months from order communication under Section 112(1)
    CondonationUp to 3 additional months under Section 112(6) - total outer limit 6 months
    FormForm GST APL-05 on efiling.gstat.gov.in
    Stay of RecoveryAutomatic under Section 112(9) on payment of pre-deposit
    Backlog Deadline30 June 2026 for pre-1 April 2026 orders (Notification S.O. 4220(E))

    GSTAT appeal filing in India is a critical step for any business that has received an adverse order from the GST First Appellate Authority or Revisional Authority. Section 112 of the Central Goods and Services Tax Act, 2017 provides the statutory framework for filing a second appeal before the Goods and Services Tax Appellate Tribunal, constituted under Section 109 CGST Act 2017. Patron Accounting provides end-to-end GSTAT appeal filing and representation services, with GSTAT matters led by of-counsel Subham Jhunjhunwala.
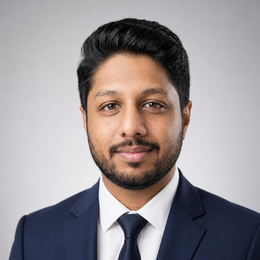
    Subham Jhunjhunwala - CA Finalist and Accounting and Tax Professional at Patron Accounting
    Accounting & Tax Professional

    Subham Jhunjhunwala

    CA Finalist | Graduate

    CA Finalist Accounting & Taxation GST & Compliance

    Subham Jhunjhunwala is a CA Finalist and Accounting & Tax Professional at Patron Accounting LLP, focused on accounting, taxation, and compliance. He works alongside the firm's CA and CS team on GST and GSTAT appeal matters.

    What Is GSTAT - The GST Appellate Tribunal

    Definition: GSTAT (Goods and Services Tax Appellate Tribunal) is the statutory appellate tribunal constituted under Section 109 of the Central Goods and Services Tax Act 2017 to hear second appeals against orders of the first appellate authority in GST matters across India. It has its Principal Bench at New Delhi and 31 State Benches.

    The GSTAT is the highest court in the country on questions of fact in GST matters. Each bench comprises two Judicial Members and two Technical Members - one from the Central Government and one from the State Government. The Tribunal was operationalised on 24 September 2025 and is the first tribunal in India to go fully digital from inception, with all appeals filed electronically through the official GSTAT e-filing portal at efiling.gstat.gov.in.

    GSTAT vs Commissioner (Appeals): GSTAT, unlike the Commissioner (Appeals) under Section 107 CGST Act, is a judicial body - not a departmental authority - and its orders carry the force of a court decree, making GSTAT the first genuinely independent forum in the GST appellate hierarchy.

    GSTAT (Goods and Services Tax Appellate Tribunal), also referred to as the GST Tribunal or GST Appellate Tribunal, was constituted under Section 109 CGST Act 2017 by the Central Government.

    Key Terms:

    • Pre-deposit - 10% of disputed tax under Section 112(8), capped at Rs 20 crore CGST
    • Stay of Recovery - Automatic under Section 112(9) on payment of pre-deposit
    • Impugned Order - Order being challenged before GSTAT
    • Form GST APL-05 - Prescribed e-filing form for GSTAT appeals
    • Condonation of Delay - Up to 3 additional months under Section 112(6)
    GSTATSection 112 CommissionerAppeals (S.107) RevisionalAuthority (S.108) 10% Pre-deposit | 3-Month Deadline | Auto Stay Stay of Recovery (S.112(9)) GSTAT Appeal Filing Flow - Section 112 CGST Act

    Who Should File a GSTAT Appeal

    Any person aggrieved by an order of the First Appellate Authority under Section 107 or the Revisional Authority under Section 108 of the CGST Act can file an appeal before the GSTAT. This includes registered taxpayers who received:

    • Adverse GST demand orders where the first appellate authority upheld the demand fully or partially
    • ITC reversal orders - Input Tax Credit disallowed or reversed by the department
    • Penalty orders - Penalties imposed under various GST provisions
    • Refund rejection orders - GST refund claims denied at the first appellate stage

    Under Section 112(1) CGST Act 2017, the GSTAT appeal must be filed within 3 months of the date of communication of the order. For orders communicated before 1 April 2026, the deadline has been extended to 30 June 2026 by Notification S.O. 4220(E) dated 17 September 2025.

    The Tribunal may refuse to admit appeals where the tax, ITC, or penalty involved does not exceed Rs 50,000 under Section 112(2).

    Our GSTAT Appeal Services

    ServiceWhat We Do
    Pre-Deposit Computation and StrategyExact calculation under Section 112(8) CGST Act, including the Rs 20 crore cap under Finance (No. 2) Act 2024, and strategy to protect working capital
    Grounds of Appeal Drafting and E-FilingLegally robust grounds of appeal and electronic filing of Form GST APL-05 on efiling.gstat.gov.in
    Stay of Recovery ApplicationSecuring automatic stay under Section 112(9) and filing interlocutory applications for additional protection where necessary
    Hearing RepresentationIn-person and virtual representation before the Principal Bench at New Delhi and State Benches across India
    Cross Objection FilingFiling of cross objections under Section 112(5) CGST Act within 45 days of receipt of notice of appeal
    High Court WritWhere GSTAT remedy is unavailable, time-barred, or a jurisdictional error exists - filing writ under Article 226
    Our Process

    7 Steps to File Your GSTAT Appeal

    Our end-to-end process for filing your GSTAT appeal under Section 112 CGST Act

    Step 1

    Review the Impugned Order

    Obtain and carefully review the order of the first appellate authority (Commissioner Appeals under Section 107) or the revisional authority (under Section 108). Identify the specific findings, quantum of demand, and statutory provisions at issue.

    Demand quantum identifiedLegal issues mapped
    Order Reviewed01
    Step 2

    Calculate Pre-Deposit Under Section 112(8)

    Compute 10% of the disputed tax amount, verify whether the Rs 20 crore CGST cap applies under Finance (No. 2) Act 2024, and confirm the amount already deposited under Section 107(6) at the first appellate stage.

    10% calculation verifiedRs 20 crore cap check
    10% Calc
    Pre-Deposit Computed02
    Step 3

    Pay Pre-Deposit Via GST Portal

    Make the pre-deposit payment through the GST portal challan or electronic credit ledger (ECL). The Supreme Court upheld pre-deposit payment through ECL in the Yasho Industries ruling (SLP dismissed 19.05.2025).

    ECL/Cash Ledger paymentPayment proof secured
    Payment Made03
    Step 4

    Prepare Grounds of Appeal

    Draft clear, numbered grounds of appeal with specific legal arguments, supported by relevant CBIC circulars, High Court and Supreme Court judgments, and documentary evidence.

    Legal arguments structuredPrecedents cited
    Grounds Drafted04
    Step 5

    File Form GST APL-05 on GSTAT Portal

    Register on the GSTAT e-filing portal at efiling.gstat.gov.in, complete the appeal form with order details, party details, and grounds. Upload all supporting documents in PDF format and pay filing fees via Bharatkosh.

    E-filed on GSTAT portalFee paid via Bharatkosh
    APL-05 Filed05
    Step 6

    Serve Notice and Obtain Filing Number

    Upon successful submission, a filing number is generated. The system sends acknowledgement via SMS and email. Serve notice on the respondent (Commissioner) as per Rule 33(1) GSTAT Procedure Rules, 2025.

    Filing number receivedNotice served
    SMS + Email
    Notice Served06
    Step 7

    Appear at Admission Hearing

    Attend the admission hearing before the assigned bench. The automatic stay of recovery under Section 112(9) takes effect once the appeal is admitted with confirmed pre-deposit.

    Expert representationAutomatic stay activated
    Appeal Admitted
    Stay Activated07

    Documents Checklist for GSTAT Appeal

    • Certified copy of the impugned order from the First Appellate Authority or Revisional Authority
    • Original order of the adjudicating authority (order-in-original)
    • Form GST APL-01 and Form GST APL-03 filed at the first appeal stage
    • Challan or proof of pre-deposit payment under Section 112(8) and Section 107(6) CGST Act
    • Detailed grounds of appeal with consecutively numbered paragraphs
    • Power of attorney or vakalatnama for authorised representative
    • Supporting CBIC circulars, notifications, and HC/SC judgments relied upon
    • GSTIN certificate and tax liability statements
    • Index of all documents, paginated and bookmarked
    • English translations of any non-English documents (certified by both parties)

    Download our GSTAT Appeal Document Checklist - email sales@patronaccounting.com or call +91 945 945 6700.

    4 Common Challenges in GSTAT Appeals - and Our Approach

    Incorrect Pre-Deposit Calculation

    A deficient or excess pre-deposit is the most common ground for appeal rejection at the admission stage. In our experience representing clients before GSTAT, many appellants either use the old 20% rate or fail to account for the Section 107(6) amount already deposited. Patron Accounting's GSTAT team computes the exact obligation under Section 112(8) with the Finance (No. 2) Act, 2024 cap, verified against the demand order.

    Missing the 3-Month Limitation Window

    Under Section 112(1), the appeal must be filed within 3 months of order communication. Section 112(6) allows condonation up to 3 additional months - but this is discretionary, not guaranteed. Patron Accounting's GSTAT team has observed that delays in gathering documents or calculating pre-deposit are the most frequent causes of time-bar. We mobilise within 48 hours of engagement.

    Poorly Drafted Grounds of Appeal

    Subham Jhunjhunwala notes that a common error at this stage is filing generic or template grounds without referencing specific statutory provisions, CBIC circulars, or judicial precedents. The Tribunal is not bound by the grounds set forth in the appeal form under Rule 31 of GSTAT Procedure Rules, 2025, but the appellant cannot urge new grounds without leave.

    E-Filing Portal Navigation Challenges

    The GSTAT portal requires precise data entry, PDF document uploads (max 20 MB), and payment via Bharatkosh. Across the matters we have handled, portal session timeouts and ARN/CRN validation errors are common. Patron Accounting provides complete portal management from registration to filing number receipt.

    Illustrative Scenario: A manufacturing company with an annual turnover of approximately Rs 200 crore received a demand order of Rs 85 lakh for ITC reversal. The first appellate authority upheld the demand. Patron Accounting's GSTAT team computed the pre-deposit at Rs 8.5 lakh under Section 112(8), prepared detailed grounds challenging the ITC reversal, and filed the appeal electronically within 6 weeks - resulting in admission with automatic stay of recovery under Section 112(9), protecting the company's working capital.

    Pre-Deposit, Filing Fees, and Engagement Terms

    Pre-Deposit Module - Section 112(8) CGST Act: The pre-deposit is 10% of the remaining amount of tax in dispute, in addition to the 10% already deposited under Section 107(6) at the first appellate stage. The total across both stages is 20% of the disputed tax component.

    ComponentAmountBasis
    Total demand orderRs 1,00,00,000Order of first appellate authority
    Of which: disputed taxRs 70,00,000Tax component of demand
    Of which: penaltyRs 30,00,000Penalty component
    Pre-deposit at first stage (S.107(6)) - already paidRs 7,00,00010% of disputed tax
    Pre-deposit at GSTAT stage (S.112(8)) - payable nowRs 7,00,00010% of disputed tax (additional)
    Total deposited across both stagesRs 14,00,00020% of disputed tax
    Balance amount - recovery stayed under S.112(9)Rs 86,00,000Automatically stayed on GSTAT admission

    Note: Finance (No. 2) Act, 2024 caps the Section 112(8) pre-deposit at Rs 20 crore under CGST. These are illustrative figures. Actual pre-deposit depends on the specific order amounts.

    Fee ComponentAmount
    Filing FeeRs 1,000 per Rs 1 lakh of tax/penalty (max Rs 25,000)
    Interlocutory Application FeeRs 5,000
    Patron Accounting Professional FeesStarting from INR 24,999 (Exl GST and Govt. Charges)

    All fees listed are indicative only and do not constitute a binding offer. Final amounts may vary depending on volume and complexity of work.

    Calculate Your Pre-Deposit Obligation - Speak to Our GSTAT Team

    Why Choose Patron Accounting for Your GSTAT Appeal

    Specialist Support

    GSTAT matters supported by Subham Jhunjhunwala, CA Finalist, with the firm's CA and CS team.

    Firm-Backed Support

    Backed by Patron Accounting's ICAI and ICSI registered CA and CS team.

    Patron Accounting Scale

    10,000+ businesses served, 4.9 Google rating (500+ reviews), 15+ years of GST compliance, notice response, and litigation expertise.

    Pan-India GSTAT Representation

    Offices in Pune, Mumbai, Delhi, and Gurugram. Representation across the Principal Bench at New Delhi and State Benches pan-India.

    Client-First Approach

    Initial strategy discussion before formal engagement. No engagement without a clear, transparent assessment of your position and pre-deposit obligation.

    Trusted by Businesses Across India

    10,000+
    Businesses Served
    4.9
    Google Rating
    15+
    Years Experience
    "Patron Accounting's GSTAT team understood our pre-deposit exposure immediately. Subham Jhunjhunwala's approach to structuring the grounds of appeal was methodical and thorough." - CFO, Manufacturing Company

    With offices in Pune, Mumbai, Delhi, and Gurugram, Patron Accounting provides GSTAT representation across the Principal Bench at New Delhi and State Benches including Mumbai, Bangalore, Chennai, Hyderabad, and Ahmedabad.

    GSTAT Appeal vs High Court Writ - Comparison

    FeatureGSTAT Appeal (S.112)HC Writ (Art.226/227)Supreme Court SLP
    When to UseAdverse first appellate order within 3 monthsJurisdictional error, violation of natural justice, GSTAT time-barredAfter High Court final order
    Pre-Deposit10% under Section 112(8)No pre-deposit as general ruleNo pre-deposit as general rule
    TimelineVariable - bench dependent6-18 months12-36 months
    Key ConsiderationPrimary remedy - exhaust before writNot a substitute for GSTAT where jurisdiction existsLast resort - constitutional jurisdiction

    A GSTAT appeal under Section 112 is the appropriate remedy where the first appellate authority has passed an order on merits - unlike a High Court writ under Article 226, which lies only where there is a jurisdictional error, violation of natural justice, or where the GSTAT remedy is time-barred beyond the 6-month outer limit under Section 112(6).

    What is the pre-deposit amount for a GSTAT appeal under Section 112?

    The pre-deposit is 10% of the disputed tax under Section 112(8) CGST Act, in addition to the 10% already paid under Section 107(6) at the first appellate stage. This amount is capped at Rs 20 crore under the CGST Act per the Finance (No. 2) Act, 2024 (effective 01.11.2024). Payment activates automatic stay of recovery under Section 112(9).

    What is the time limit to file a GSTAT appeal?

    A GSTAT appeal must be filed within 3 months from the date of communication of the order under Section 112(1) CGST Act 2017. The Tribunal may condone delay up to 3 additional months under Section 112(6). For backlog appeals (orders before 1 April 2026), the deadline is 30 June 2026. Beyond 6 months total, the right to appeal is permanently lost.

    Can the GSTAT appeal deadline be extended beyond 6 months?

    No. Under Section 112(6) CGST Act, the maximum condonation period is 3 months beyond the standard 3-month limit. GSTAT has no power to condone delays beyond this 6-month total. If the deadline is missed, the only recourse may be a High Court writ petition under Article 226.

    How do I file an appeal on the GSTAT e-filing portal?

    Register on the official GSTAT e-filing portal at efiling.gstat.gov.in, validate your ARN/CRN, complete Form GST APL-05 with order details and grounds of appeal, upload supporting documents in PDF format, pay fees via Bharatkosh, and authenticate with DSC or Aadhaar e-sign.

    What happens if I miss the GSTAT appeal deadline?

    Missing the 3-month window under Section 112(1) means the tribunal remedy is lost unless condonation is granted within the additional 3-month period under Section 112(6). Beyond the 6-month outer limit, the only recourse is a writ petition before the jurisdictional High Court under Article 226.

    Can I get a stay of recovery after filing a GSTAT appeal?

    Yes. Under Section 112(9) CGST Act, recovery of the balance disputed amount is automatically stayed during the pendency of the GSTAT appeal once the appellant has paid the pre-deposit under Section 112(8). No separate stay application is needed - it operates by force of statute.

    What is the difference between GSTAT Principal Bench and State Bench?

    The Principal Bench sits at New Delhi under Section 109(3) and hears matters of national importance, inter-state disputes, and anti-profiteering cases. State Benches hear matters in their respective jurisdictions - there are 31 State Benches across 44 locations in India.

    What is the filing fee for a GSTAT appeal?

    The filing fee is calculated at Rs 1,000 per Rs 1 lakh of tax or penalty involved, subject to a maximum of Rs 25,000. For interlocutory applications, the fee is Rs 5,000. All fees are paid online through the GSTAT portal via Bharatkosh.

    Quick Answers

    What percentage must be deposited for GSTAT appeal?
    10% of disputed tax under Section 112(8), capped at Rs 20 crore. In addition to 10% paid under Section 107(6).
    What is the limitation period for GSTAT appeal?
    3 months from order date under Section 112(1). Condonation up to 3 additional months under Section 112(6).
    Is stay of recovery automatic?
    Yes - Section 112(9) provides automatic stay once pre-deposit is paid.
    What is the backlog appeal deadline?
    30 June 2026 for orders before 1 April 2026 per Notification S.O. 4220(E).
    What form is used for GSTAT appeal?
    Form GST APL-05, filed electronically on efiling.gstat.gov.in.
    Can GSTAT appeal be withdrawn?
    Yes, with Tribunal approval. Decision on withdrawal must be rendered within 15 days.

    3-Month GSTAT Deadline - Act Now

    Limitation Urgency: GSTAT appeals must be filed within 3 months of the date of communication of the order under Section 112(1) CGST Act 2017. Condonation up to 3 additional months under Section 112(6). Beyond 6 months, the right to appeal at the GSTAT is permanently lost.

    Every day from the order communication date reduces your available window. For backlog appeals with orders before 1 April 2026, the filing deadline is 30 June 2026.

    Contact Patron Accounting immediately: +91 945 945 6700 | WhatsApp Us

    The 3-Month GSTAT Deadline Is Running - Contact Us Today

    GSTAT appeal filing in India under Section 112 CGST Act 2017 requires precision in pre-deposit computation, adherence to the 3-month limitation window, and legally robust grounds of appeal. The Tribunal's digital-first approach through the e-filing portal at efiling.gstat.gov.in demands accurate documentation and procedural compliance.

    Patron Accounting's GSTAT practice is supported by Subham Jhunjhunwala, CA Finalist and Accounting & Tax Professional, working alongside the firm's CA and CS team on every GSTAT engagement. With the 3-month limitation clock running from the date of order communication, every day of delay narrows the window for strategic preparation.

    Book a Free Consultation - No Obligation.

    Content Created: 16 March 2026  |  Last Updated: 16 March 2026  |  Next Review: 16 June 2026  |  Reviewed By: CA & CS Team, Patron Accounting LLP

    This page is reviewed every 3 months or when triggered by: New GSTAT bench constitution notifications, Finance Act amendments to Section 112 CGST Act, CBIC circulars on pre-deposit or stay of recovery, GSTAT e-filing portal procedure changes, significant HC or SC judgments on GSTAT jurisdiction, or any change to the Rs 20 crore pre-deposit cap.