Several units of measure
Fibre and yarn are held by weight, fabric by length (and by weight per square metre), garments by piece. Conversions between them are where many differences start.

Stock Audit · Textile and apparel
An independent count and valuation of fibre, yarn, greige and finished fabric, garments in production, finished garments, trims and seconds held by a spinner, weaver, processor, garment maker or brand, compared with the books and, where the stock secures a loan, with the bank's stock statement. Textile stock is measured in kilograms, metres and pieces at once, changes form at every stage and loses value quickly when the shade, the season or the quality is wrong, so the count and the valuation both need care.
In short
A stock audit is an independent check, usually ordered by your bank through the sanction letter, that the stock pledged as security exists, is saleable and yours, and is valued correctly. In a textile or apparel business the audit asks the same questions. But the stock answers them differently: yarn is weighed, fabric is measured and weighed, garments are counted, half the stock may be lying with dyers, printers and stitching units, and two rolls of the same item can be worth different amounts because of shade, season or quality.
This page covers what the industry changes: the count by unit of measure, shade lots and GSM, greige against finished fabric, seconds and old seasons, stock with job workers, the records a mill or garment unit keeps, what the count usually finds and what moves the fee. Everything about the stock audit itself is written once on our India-wide stock audit page and is not repeated here.
What changes
Six things that a count of fabric, yarn and garments has to handle and a count of cartons on racks does not.
Fibre and yarn are held by weight, fabric by length (and by weight per square metre), garments by piece. Conversions between them are where many differences start.
Yarn becomes greige fabric, greige becomes dyed or printed fabric, fabric becomes cut panels and then garments. Each stage carries a different cost and a different unit.
Dyeing, printing, processing, embroidery and stitching are often done by job workers, so your stock is spread across many premises that are not yours.
Fabric from different dye lots may not match, and fabric or garments with defects sell as seconds at a lower price. Two rolls of one item are not interchangeable.
Garments and printed fabric for past seasons can lose most of their value, so carrying them at cost overstates the stock the bank lends against.
Fabric is counted by rolls with ticket lengths, garments by cartons and bundles, so the count has to test what is actually inside rather than read the label.
A lender's stock audit covers one asset class, is commissioned by a lender rather than required by the Companies Act, reports to that lender and gives no opinion on the accounts. Most bank panels require a practising Chartered Accountant firm; some lenders also empanel Cost Accountants, so check your bank's panel conditions. Who can sign, and RBI's position, are set out under when a stock audit is needed on our India-wide stock audit page.
Scope
Every stage of the stock, in the unit that stage is held in, and the valuation rule that applies to each. The standard parts of a bank stock audit report are described under what the stock audit report contains on our India-wide stock audit page.
| Stock category | What is checked |
|---|---|
| Fibre and yarn | Weight by count, type and lot; bag and cone counts; sample bags weighed |
| Greige fabric | Rolls by quality, length and weight; lot identification; what is at each processor |
| Processed fabric | Rolls by shade lot, design and finish; ticket length and fabric weight tested against a sample |
| Work in progress | Cut panels and garments by stage of stitching, finishing and packing; stock lying with job workers |
| Finished garments | Pieces by style, size, colour and season; sample cartons opened and counted against the carton marking |
| Accessories and trims | Buttons, zips, labels, threads and packing material by quantity and value |
| Seconds, rejects and waste | Quantity, how they are separated from first quality, and how they are valued |
| Valuation | Lower of cost and net realisable value, stage by stage; write-downs for seconds and old seasons |
Under AS 2 and Ind AS 2, inventory is carried at the lower of cost and net realisable value. Net realisable value is the estimated selling price less the estimated costs to complete and sell; write-downs are usually made item by item, and related items in one product line may be grouped. LIFO is not permitted under AS 2, Ind AS 2 or ICDS II: cost is FIFO or weighted average, with specific identification for items that are not interchangeable. The count separates seconds from first quality; it does not grade the fabric.
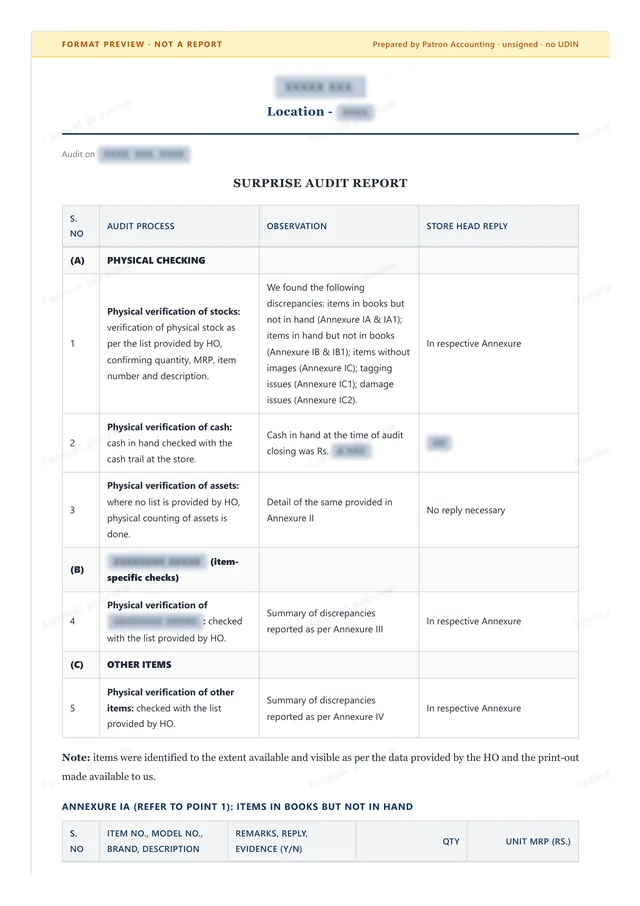
See a sample
Stock audit report
A summary of a stock audit report to the bank, with the stock and book-debt reconciliation and the drawing power.
Values hidden for privacy. Names, numbers and dates are covered. Your own document carries your details.
Download stock audit report sample (PDF) View stock audit report sample
Process
The method depends on the engagement scope: the number of units and job workers, whether production pauses, and whether a full count or a sample is required. These are the steps the textile stock adds to the general stock audit procedure.
Agree how issues to production, receipts from job workers, deliveries to processors and dispatches during the count will be recorded, so that fabric moving between your unit and a dyer on the count day is counted once.
You and the auditorWeigh or count yarn by bag and cone; count fabric rolls and test ticket lengths and weights by unrolling or re-measuring a sample; count garments by carton, with sample cartons opened against the carton marking.
Field teamNote the shade lot, design and quality on each roll or bundle as it is counted, so the stock can be matched to the records and valued correctly, and rolls without a lot identification are listed.
Field teamRecord cut panels and garments at each stage of stitching, finishing and packing, and test fabric issued against garments produced using your consumption norms.
Field teamGoods sent to a job worker under section 143 of the CGST Act stay your stock, because ownership does not pass, so they are counted in your inventory and confirmed with challans and job-worker statements, and where the scope allows, at the job worker's premises.
Field team and job workersWhere inventory is material, SA 501 expects the auditor to attend the physical count, evaluate management's procedures, inspect the inventory and perform test counts. Sample size and test checks are designed using the principles of SA 530 (Audit Sampling).
AuditorReconcile the count with the stock records by stage and lot, value seconds and old-season stock at net realisable value, recompute eligible stock where the stock secures a limit, discuss the differences with you and report. How long the report takes depends on the scope and the team needed, and is confirmed with your quote.
Patron, to the bankThe textile task
The four things a textile count records that a general stock count never meets, and the one place most of the differences come from.
Fabric dyed in different lots can differ slightly in colour, so garments are cut from one shade lot at a time. Rolls without shade-lot identification are hard to use and often sell at a discount. The count records the lot on every roll and flags unidentified or mixed lots. Term: shade lot. Guide: why shade, lot and batch matter more than SKU.
Fabric is often bought and sold by weight but stored and used by length. Grams per square metre links the two. If the actual GSM differs from the standard in your records, every quantity converted between weight and length is wrong. The count test-weighs sample lengths to check the conversion. Term: GSM fabric weight.
Greige fabric is woven or knitted but not yet bleached, dyed or finished. It is valued differently from processed fabric and is often at a processor's premises, so the count separates greige from processed stock and confirms what is with each processor. Term: greige fabric. Guide: counting greige, finished goods and trims by weight.
Fabric and garments with defects, and garments from past seasons, are worth less than first-quality current stock. The count lists them separately and checks that they are valued at what they can realistically be sold for, not at cost. Term: seconds and rejects. Guide: valuing unsold collections at season end.
Conversion check
A roll's weight should follow from its length, its width and its GSM. When the three do not agree, the difference points to a measurement problem, a wrong standard GSM, or a shortage.
If the same roll weighs 27 kg on the scale, either 10 metres are missing or the fabric is lighter than its ticket says. The count records which.
Goods sent to a job worker under section 143 of the CGST Act stay the principal's stock, because ownership does not pass, so they are counted in the principal's inventory and confirmed with challans and job-worker statements. Inputs must come back within one year and capital goods within three years, or the principal is treated as having supplied them on the day they were sent. Term: job work stock.
Many banks leave stock lying with job workers out of drawing power unless the sanction letter or hypothecation agreement expressly covers it, and banks treat work in progress differently: some exclude it from drawing power, others include it with a higher margin set in their credit policy. A textile count therefore reports stock with each job worker, and WIP by stage, as separate lines so the bank can apply its own rule.
What to keep ready
These are the records a mill or garment unit keeps that a general stock audit does not ask for. The general list, sanction letter to insurance policy, is under records to keep ready before the count on our India-wide stock audit page.
What the count finds
The six differences that come up most often in fabric, yarn and garment stock, the usual reason, and what a unit can do about each before the next count.
| Finding | Usual cause | What to do |
|---|---|---|
| Roll lengths shorter than the tickets | Tickets not updated after cuts for samples or small orders | Re-ticket rolls after every cut; test-measure on receipt |
| Fabric by weight not matching fabric by length | The standard GSM in the records differs from the actual GSM | Test GSM by lot and correct the conversions |
| Mixed or unidentified shade lots | Lot not recorded at receipt or after processing | Label the shade lot on every roll at receipt and after every processing stage |
| Old open job-work challans | Goods returned without a record, or still with the job worker | Reconcile challans with every job worker monthly; chase anything older than the time the bank or section 143 allows |
| Past-season garments carried at full cost | No season-wise ageing of finished garments | Review stock by season and write down to net realisable value |
| Cartons with fewer pieces than marked | Cartons opened for samples or shortages and not re-marked | Seal cartons and record every opening |
Many banks exclude obsolete, expired or slow-moving stock from drawing power, using ageing cut-offs set in their own policy and sanction letter, so past-season garments carried at cost overstate the stock the limit is secured on. Under section 17(5)(h) of the CGST Act, input tax credit must be reversed on goods lost, stolen, destroyed, written off, or given as gifts or free samples, so a write-off of rejected fabric or garments has a GST consequence as well as a valuation one.
Fees
A written quote once the units, the job workers, the stages in scope and the bank's requirements are known. The general cost drivers of a stock audit are under what a stock audit costs on our India-wide stock audit page.
Professional fee
Starting from ₹2,499 Exl GST and Govt. Charges · one unit, standard scopeThe quote rises with the work the stock involves, not with the size of the loan alone. Travel is charged extra and quoted for each location in your written quote.
Fees exclude GST and government charges. All fees listed are indicative only and do not constitute a binding offer; the final amount is confirmed after a scoping review and depends on the volume of work and the complexity involved.
For a quote, send the number of units and job workers, the stages in scope and whether the stock secures a bank limit, and you will receive the fee and the records list in writing.
How it is delivered
Patron Accounting runs stock audits across India through local field teams coordinated by Patron. Engagement planning, scope and quality review stay with Patron, and the report is reviewed and signed off by a Chartered Accountant.
Statements about frequency, panels, job-worker stock, work in progress and ageing exclusions describe common bank practice; your own sanction letter decides how they apply to you.
Read
The report format, the RBI position, how often a stock audit is required and the common deficiencies a bank stock audit finds are covered by the guides linked from the national stock audit page.
Get a quote
Share the number of units and job workers, the stages of production involved and whether the stock secures a bank limit, and you will receive a quote and a list of records to prepare.
We reply on working days.
Stock that is not textile, or a different service? Say so in the message and the right team calls instead. By sending this form you agree to our privacy policy. No spam, no sharing of your details.
Message us on WhatsApp with the bank's request, your units and your job workers, and the stock audit team replies.
Chat on WhatsAppWorking hours: 9 AM to 6 PM, Monday to Saturday.
A CA reads the bank's request, confirms the units, the job workers and the stages in scope, and sends the scope, the fee and the records list in writing before any visit is planned.