Many small sites
Each store is its own count with its own differences, so results are reported store by store and category by category, not only as one total for the chain.

Stock Audit · Retail stores and chains
An independent count of the stock in one store or across a chain, compared with the point-of-sale and inventory system, so you know what each store really holds, where the differences are and what they cost you. Where the stock secures a working capital limit, the same count supports the stock statement you give the bank.
In short
A retail stock audit, often called a store audit, counts what is actually in each store and compares it with what the till and the inventory system say should be there. The difference, once wrong codes, unprocessed returns and transfers in transit are taken out, is the stock the business has lost without a sale. Retailers and franchisors use it to measure that loss store by store; banks ask for it where store stock secures a working capital limit.
This page covers what a chain of stores changes: counting many small sites while they keep trading, stock spread across the shop floor and the back room, records driven by billing, shrinkage, returns and transfers, the records a store keeps, what the count usually finds and what moves the fee. What a stock audit is and how one is carried out in general are written once on our India-wide stock audit page.
What changes
A factory may hold hundreds of items in a few stores. A retail chain holds thousands of items spread thinly across many stores, on shelves, in back rooms and on the road between them.
Each store is its own count with its own differences, so results are reported store by store and category by category, not only as one total for the chain.
Goods sit on shelves, end-caps, window displays, fitting rooms and by the till as well as in the back room. Every area is mapped so nothing is missed or counted twice.
Many stores cannot close for long, so the count is planned around trading hours, and sales made while counting are captured and adjusted at the end.
System stock falls each time an item is billed. Wrong billing codes, returns not processed and exchanges keyed as new sales all turn into count differences.
Transfers from the warehouse and between stores leave one location before they reach the next, and a transfer received but not confirmed shows as a shortage in one store and an excess in another.
Theft, damage, expiry, supplier short-deliveries and admin errors reduce stock without a sale. The count is often the only reliable measure of how much each store loses.
A lender's stock audit covers one asset class, is commissioned by a lender rather than required by the Companies Act, reports to that lender and gives no opinion on the accounts. Who can sign, and RBI's position, are under when a stock audit is needed on our India-wide stock audit page.
Scope
Each store is checked area by area and item by item. The standard parts of a bank stock audit report are under what the stock audit report contains on our India-wide stock audit page.
| Area | What is checked |
|---|---|
| Quantity by store | Counted quantity against the system, item by item and store by store |
| Location within the store | Shop floor, back room, displays, fitting rooms and the damaged-goods area |
| Shrinkage | Value of stock missing without a sale, by store and by category |
| Returns and damaged goods | Customer returns awaiting processing, damaged and expired stock, goods waiting to go back to suppliers |
| Transfers | Stock on the way between the warehouse and stores, and between stores |
| Pricing and labelling (where in scope) | Packaged goods carrying the declarations the Legal Metrology (Packaged Commodities) Rules 2011 require, including the retail sale price |
| Valuation (where in scope) | Lower of cost and net realisable value, or the retail method where it approximates cost |
| Bank terms (where the stock is security) | Declared stores, insurance cover and drawing power |
Under AS 2 and Ind AS 2, inventory is carried at the lower of cost and net realisable value. Both standards allow the retail method for convenience, but only where the result approximates actual cost, so a chain that values stock at selling price less a margin should be ready to show the margin is realistic for each category, especially after a mark-down. For more, read retail inventory method vs cost method.
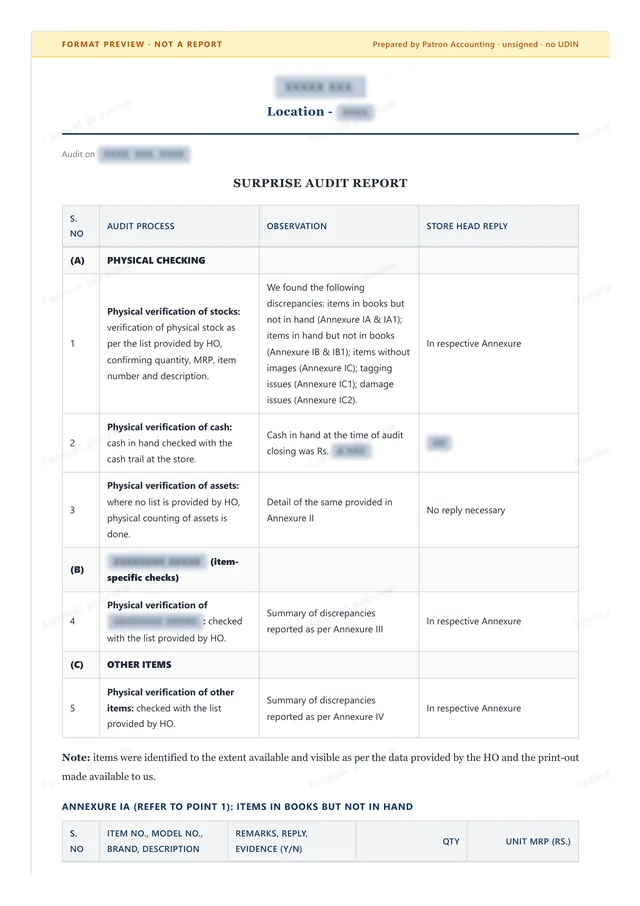
See a sample
Stock audit report
A summary of a stock audit report to the bank, with the stock and book-debt reconciliation and the drawing power.
Values hidden for privacy. Names, numbers and dates are covered. Your own document carries your details.
Download stock audit report sample (PDF) View stock audit report sample
Process
The method depends on the engagement scope: the number of stores, how long each can pause selling, and whether a full count or a sample is required. Whether counts happen before opening, after closing or during trading, and whether till or cash checks are included, is agreed for each engagement. These are the steps stores add to the general stock audit procedure.
Agree which stores are counted and in what order, and how sales, returns and deliveries on the count day will be recorded.
You and the auditorDivide the store into shop-floor sections, back room, displays, fitting rooms and the damaged-goods area, so every area has a counter. The shelf plan helps here: where planogram compliance is good, the zone map follows it.
Auditor and store managerRecord item code, quantity and condition in each zone, and keep damaged, expired and customer-held goods apart from saleable stock.
Field teamWhere inventory is material, SA 501 expects the auditor to attend the physical count, evaluate management's procedures, inspect the inventory and perform test counts. Sample size and test checks are designed using the principles of SA 530 (Audit Sampling), from the system to the shelf and from the shelf to the system.
AuditorRecount items with large differences, then check for unbilled sales, returns not processed, wrong codes and transfers in transit before calling anything a loss.
Field team and store staffAdjust for sales and receipts made while counting, and compare the counted stock with the system at the cut-off.
AuditorShow differences and shrinkage by store and category, with the causes found and the fixes recommended. How long the report takes depends on the scope and the team needed, and is confirmed with your quote.
Patron, to you or the bankThe retail task
The raw difference between the shelf and the system is not shrinkage until its other causes are taken out. A store audit separates them so loss-prevention work goes to the right stores and categories.
Stock that disappears without a sale: theft by customers or staff, damage, expiry, short-deliveries and admin errors. It varies by format and category, so the useful comparison is with each store's own history and with your other stores, not with a single industry number. The audit splits what can be explained from what cannot.
A customer return accepted at the counter but not processed shows as excess stock; a return to a supplier that has left the store but not been recorded shows as a shortage. Both are traced before any difference is reported. Saleable returns go back to stock; the rest are listed apart.
Food products are also subject to the Food Safety and Standards Act 2006, so storage conditions and remaining shelf life are recorded for perishables. Expired and damaged goods are listed separately from saleable stock and valued at what they can realistically fetch.
Items with a low sell-through rate sit on shelves and in back rooms long after their season. The count lists them by age so their value can be reviewed against net realisable value before the next mark-down decision.
Under section 17(5)(h) of the CGST Act, input tax credit must be reversed on goods lost, stolen, destroyed, written off, or given as gifts or free samples. Shrinkage confirmed by the audit therefore affects the GST return as well as the profit and loss account.
Record each write-off with its reason, date and approval when it is made, so that stock, profit and GST records stay aligned and the next count does not find the same loss again.
What to keep ready
These are the records a store or chain keeps that a general stock audit does not ask for. The general list, sanction letter to insurance policy, is under records to keep ready on our India-wide stock audit page.
What the count finds
The differences that come up most often across a chain of stores, the usual reason, and what to change before the next count.
| Finding | Usual cause | What to do |
|---|---|---|
| Shortages concentrated in a few categories | Theft or damage in small or high-value items | Review display, security tagging and access for those categories |
| Excess in one store, shortage in another | Transfers sent but not received in the system | Make receiving stores confirm transfers on the day |
| Items on the shelf but not in the system | Wrong item codes at receiving or billing | Correct the codes and retrain staff on scanning |
| Back-room stock the system cannot see | Deliveries not received in the system | Receive deliveries on the day they arrive |
| Expired or damaged stock counted as saleable | No separate area or register | Keep a marked area and record removals daily |
| The same store differs count after count | Weak store-level controls | More frequent cycle counts and supervision in that store |
Few chains can count every store every month, and they do not need to. A rotation that counts high-risk stores and categories more often, with cycle counts of small, high-value items in between, keeps differences small and makes each full count quicker. For how to build that rotation, read retail stock audit frequency.
Not the same job
"Store audit" is used for two different checks. Many retailers use both; this page covers the first.
| Point | Retail stock audit | Mystery audit |
|---|---|---|
| Question answered | Is the stock in each store what the system says? | How does each store treat a customer? |
| Method | Physical count and reconciliation | Visits by people posing as customers, scored on a checklist |
| Who sees it | Finance, loss prevention and, where the stock is security, the bank | Operations, brand and training teams |
| Output | Store-wise differences, shrinkage and causes | Store-wise scorecards on service and standards |
Related checks
An outlet visit scored against your service standards. It answers how the store sells, not what it holds. Mystery audit
Whether shelves match the agreed layout is measured as planogram compliance. A stock audit uses the layout to plan the count; it does not score it.
Fees
A written quote once the stores, their size and the trading arrangements are known. The general cost drivers of a stock audit are under what a stock audit costs on our India-wide stock audit page.
Professional fee
Get a quote Exl GST and Govt. Charges · final fee after scopingThe quote rises with the number of stores and items and with how the count fits around trading. travel quoted per location Work usually starts within 3 to 5 working days of confirmation.
Fees exclude GST and government charges. All fees listed are indicative only and do not constitute a binding offer; the final amount is confirmed after a scoping review and depends on the volume of work and the complexity involved.
For a quote, send the number of stores, their rough size and whether they can close for the count, and you will receive the fee and the records list in writing.
How it is delivered
Patron Accounting runs stock audits across India through local field teams coordinated by Patron. Engagement planning, scope and quality review stay with Patron, and the report is reviewed and signed off by a Chartered Accountant.
Statements about audit frequency describe common bank practice; your own sanction letter decides how it applies to you.
Read
Get a quote
Share the number of stores, their rough size and whether they can close for the count, and you will receive a quote and a list of records to prepare.
We reply on working days.
Not a retail count, or a different service? Say so in the message and the right team calls instead. By sending this form you agree to our privacy policy. No spam, no sharing of your details.
Message us on WhatsApp with the number of stores and their cities, and the stock audit team replies.
Chat on WhatsAppA CA confirms the stores, the dates and how trading will be handled, and sends the scope, the fee and the records list in writing before any count is planned.