Stock Audit for Auto Component Manufacturers in India
An independent count and valuation of the steel, castings, forgings, bought-out parts, part-machined work in progress, finished parts and scrap held by a component maker, compared with the books and, where the stock secures a loan, with the stock statement given to the bank. On any day much of that stock is not in the stores: it sits between machining operations, with heat-treatment and plating job workers, in transit to a vehicle maker's plant or in a customer's warehouse, so the count follows the routing rather than the racks.
7+ years in practice (since 2019)
Reports reviewed and signed off by a Chartered Accountant
Content reviewed by Subham Jhunjhunwala, CA FinalistRegulatory and banking statements signed off by CA Sundram GuptaReviewed on 23 October 2026
Auto component stock audit at a glanceWhat is counted, where, and who orders it
Starting from ₹2,499 Exl GST and Govt. Charges · one unit, standard scope · travel quoted per location
Final fee after scoping
What is countedSteel and castings by weight and lot, bought-out parts by count or pack, WIP by operation, finished parts by part number, scrap by weight
Where the stock sitsStores, machining cells and the assembly line, heat-treatment and plating job workers, goods in transit and customer warehouses
Who orders itUsually your bank, through the sanction letter of a cash credit or overdraft limit; sometimes management, the statutory auditor or a buyer
Where we countPlants and job-work sites anywhere in India, by local field teams that Patron coordinates; Patron keeps planning, scope and quality review
What a stock audit is, the general procedure, the report format and the general records list sit on the national stock audit page, linked under "Read here, read there" below.
In short
An auto component stock audit, in short
A lender usually orders a stock audit through the sanction letter, to confirm that the stock behind a working capital limit exists, belongs to the borrower and is valued correctly. At a component plant that stock is half-made most of the time: a bar becomes a forging, the forging is turned and drilled, the part goes out for heat treatment or plating and comes back, and only then is it a finished part carrying a customer's part number. Each stage has its own cost, and several of them happen on someone else's premises.
This page covers what the component business changes: counting work in progress operation by operation, stock with job workers and the age of their challans, consumption against the bill of materials, scrap and rework, parts made for one customer, the plant records the count needs, the usual findings and what moves the fee. The stock audit itself is written up once on our India-wide stock audit page and is not repeated here.
Read here, read there
Here
What component stock changes in the countRouting stages, job workers, bought-out parts, scrap, customer parts
Here
What the count covers, stage by stageSteel and castings to finished parts; what the report adds
Here
Job work, WIP and the bill of materialsChallan age, stage-wise WIP, the consumption check
What makes auto component stock different to audit
Six things a count of forgings, machined parts and bought-out items has to handle that a count of finished goods on racks never meets.
Work in progress at every operation
A part may be forged or cast, turned, drilled, heat treated, plated or painted and assembled. Stock at each operation carries a different cost, so it is counted and valued at the stage it has reached, not as raw material and not as a finished part.
Stock that leaves mid-process
Heat treatment, plating, painting and some machining are often done by job workers, so a large share of the work in progress can be on other premises on the count day, under challans that stay open for weeks.
Bought-out parts in bulk
Fasteners, bearings, rubber parts and wiring harnesses arrive in large quantities of small items and are usually counted by weight or by sealed pack rather than piece by piece.
Parts made for one customer
A part made to one vehicle maker's drawing usually cannot be sold to anyone else. When a model is discontinued or a part number is superseded, that stock can lose most of its value at once.
The bill of materials as the standard
Material is issued against the bill of materials. When scrap, rework or unrecorded substitutions push actual consumption above the standard, the gap builds up in the stock records until a count exposes it.
Scrap, swarf and rework
Machining swarf, bar ends, rejected parts and rework stock are produced every shift. In this industry scrap can be a material share of raw material cost, enough to affect both profit and drawing power, so it has to be weighed and recorded.
Who asks for an auto component stock audit
Banks, where raw material, work in progress and finished parts secure a cash credit or overdraft limit. The requirement reaches the plant through the sanction letter, not through any statute, and the letter sets how often the count is due, commonly every quarter or half-year.
Management and the statutory auditor, at year-end or when consumption and closing stock stop making sense against what the plant produced.
Buyers and investors, during due diligence on a component business, to see what its inventory is really worth.
A lender's stock audit looks at one asset class and reports to that lender; it is commissioned by the lender rather than required by the Companies Act, and it gives no opinion on the accounts. Most bank panels require a practising Chartered Accountant firm and some lenders also empanel Cost Accountants, so check your bank's panel conditions. Who can sign, and RBI's position, are under when a stock audit is needed on our India-wide stock audit page.
Scope
What an auto component stock audit covers
Each kind of stock in the unit it is held in, with the identification that ties it back to the records. The standard parts of a bank stock audit report are under what the stock audit report contains on our India-wide stock audit page.
Stock category
What is checked
Steel bars, sheets, castings and forgings
Weight or count by grade and size; the heat or lot identification on each stack
Bought-out parts
Count, weight or sealed-pack count; ageing; parts for discontinued models
Work in progress
Quantity at each operation, the cost built up to that operation, and what is with each job worker
Finished parts
Quantity by part number and customer, packing, stock in transit and stock held at customer warehouses
Scrap, rejects and rework
Weight or count, where it is kept, how it is recorded and valued, and the scrap sale record
Consumables, tooling spares and packing
Quantity, and whether the bank's definition of stock includes them
Customer-supplied material
Identified and left out of your stock, because it belongs to the customer
Valuation
Lower of cost and net realisable value, the cost formula, and cost built up stage by stage
What the report adds for component stock
WIP by operation, each stage at its own cost, in the order of the routing
Job-work reconciliation: stock with each heat treater, plater and machining vendor, and the age of every open challan
Consumption against the bill of materials: which part numbers and operations carry the difference
Scrap and rework: what was generated, sold and recorded, and what was not
Customer-specific and slow-moving part numbers, with the write-down they need and its effect on drawing power
Under AS 2 and Ind AS 2 inventory is carried at the lower of cost and net realisable value. LIFO is not permitted under AS 2, Ind AS 2 or ICDS II; cost formulas are FIFO or weighted average, with specific identification for items that are not interchangeable. Dies, moulds, jigs and fixtures are usually fixed assets rather than stock, so they are left out of the count and checked through a fixed asset verification instead.
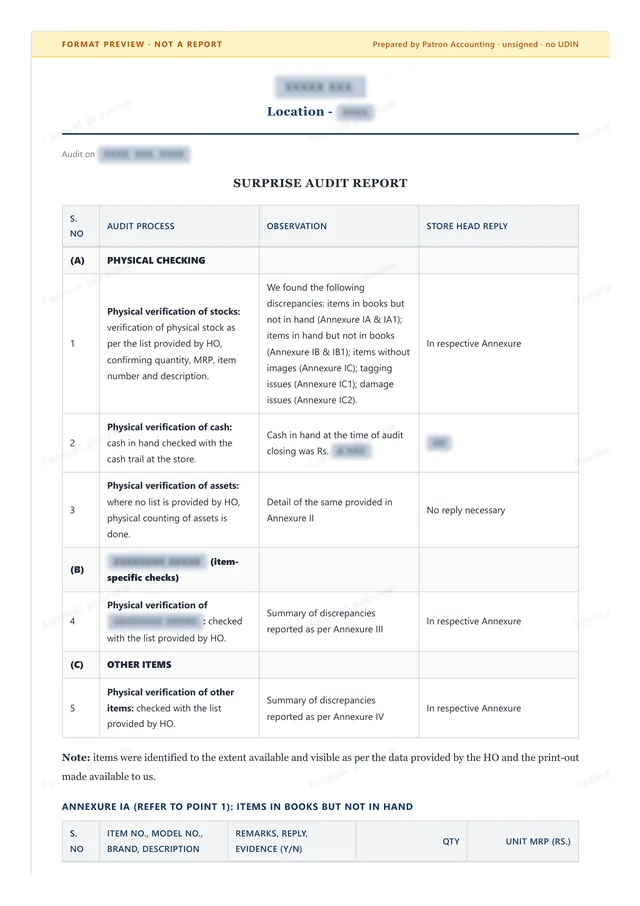
Sample with values hidden
See a sample
Stock audit report
A summary of a stock audit report to the bank, with the stock and book-debt reconciliation and the drawing power.
Prepared by
A Chartered Accountant at Patron Accounting
When you get it
After the stock audit is completed.
Values hidden for privacy. Names, numbers and dates are covered. Your own document carries your details.
The method depends on the engagement scope: how many plants and job-work sites there are, whether production pauses, and whether the bank wants a full count or a sample. Whether the count runs between shifts, over a planned shutdown or alongside production is agreed each time. These are the steps component stock adds to the general stock audit procedure.
1
Fix the cut-off around production
Agree how material issues, parts produced, rejections and receipts from job workers during the count will be recorded, and close the issue slips up to the cut-off, so material cannot leave the stores and reappear on the line inside one count.
You and the auditor
2
Count stores and finished parts
Count steel, castings, bought-out parts and finished parts by location; weigh small parts and swarf where agreed, fixing the weight per piece from a counted sample.
Field team
3
Count WIP operation by operation
Record what sits at each machine, cell and inspection point against its part number and the operation it has reached, so each stage can be valued at its own cost.
Field team
4
Confirm stock with job workers
Goods sent to a job worker under section 143 of the CGST Act stay the principal's stock, because ownership does not pass, so they are counted in the principal's inventory and confirmed with challans and job-worker statements. Where the scope includes it, the job worker's floor is visited in the same window.
Field team and job workers
5
Test
Where inventory is material, SA 501 expects the auditor to attend the physical count, evaluate management's procedures, inspect the inventory and perform test counts; the sample and the test checks follow the principles of SA 530 (Audit Sampling).
Auditor
6
Reconcile against the bill of materials
Reconcile the count with the stock records, then compare material issued with parts produced at the bill-of-materials quantity to find the part numbers and operations that carry the difference.
Auditor
7
Value and report
Value each stage at its cost, list slow-moving and customer-specific part numbers at net realisable value, recompute eligible stock where a bank limit is involved, discuss the differences with you and report. How long the report takes depends on the scope and the team needed, and is confirmed with your quote.
Patron, to the bank
The component task
Job work, WIP and the bill of materials
Most differences at a component plant start in one of three places: material away with job workers, value sitting between operations, and consumption that has drifted from the standard. The count reports each on its own line.
Work in progress by stage
A flange that has been forged and turned but not yet heat treated is worth more than the bar and less than the finished part. Banks treat WIP differently: some exclude it from drawing power, others include it with a higher margin set in their credit policy. Reporting it stage by stage lets the bank apply its own rule and shows where material is piling up between operations. Term: sub-assembly stock.
Bill of materials against actual issue
When actual consumption runs above the bill of materials, the records drift away from the floor. The usual causes are scrap above the standard allowance, rework that uses extra material, substitutions nobody recorded and a BOM left unchanged after a design change. Guide: reconciling the BOM to shop-floor consumption.
Scrap and rework
Swarf, bar ends and rejected parts are weighed where they arise and again when they are sold. Scrap sold but never recorded, or rework stock carried as good parts, shows up later as a raw material shortage or a finished-parts excess.
Customer-supplied material and tooling
Free-issue steel or components supplied by a vehicle maker, and tooling the customer paid for, belong to the customer. They are tagged and kept out of your stock and your drawing power, even when they sit in your stores.
Consumption check
Parts made, the bill of materials and material issued have to agree
The material a batch should have used follows from the parts made, the BOM quantity per part and the scrap the standard allows. Issues above that figure point to extra scrap, rework, an outdated BOM or a shortage.
parts made×BOM kg per part×(1 + scrap allowance)=expected issue
10,000×0.42 kg×1.05=4,410 kg
If the stores issued 4,650 kg for that batch, 240 kg is unexplained. The count, the scrap weighments and the rework register show whether it went to swarf, to rework or somewhere else.
Stock with job workers: where most component differences start
Inputs sent to a job worker must come back within one year and capital goods within three years, or the principal is treated as having supplied them on the day they were sent (section 143 of the CGST Act). The Commissioner may extend these periods, by up to one more year for inputs and two years for capital goods, on sufficient cause being shown; the extension must be sought. The count therefore checks the age of each open challan as well as the quantity behind it. Term: job work stock.
Many banks leave stock lying with job workers out of drawing power unless the sanction letter or hypothecation agreement expressly covers it. A component count reports what is with each heat treater, plater and machining vendor on its own line, with the challan dates, so the bank can apply its own rule and you can chase anything that has stayed out too long.
What to keep ready
Records the component count works from
The records below are the ones a component plant keeps and a general stock audit does not ask for. The general list a bank expects, from the sanction letter to the insurance policy, is under records to keep ready before the count on our India-wide stock audit page.
01
Stock register by part number and location The book figure being tested, with each job worker and customer warehouse as a location
02
Bill of materials and routing To value WIP by operation and to compare standard with actual consumption
03
Production, rejection and rework reports To explain WIP, scrap and the parts sent back for rework
04
Job-work challans and job-worker stock statements To confirm stock away from the plant and to age every open challan
05
GRNs, delivery challans and e-way bills around the cut-off For the cut-off, and for parts moving between plants, vendors and customers
06
Scrap generation and scrap sale records To explain scrap leaving the plant, by weight and by value
07
Standard cost sheets and recent selling prices For stage-wise cost and the net realisable value of slow-moving part numbers
08
Bank sanction letter and stock statements Where the stock secures a limit: what counts as stock, the margins and the figures already given to the bank
Before count day, in the plant
Post every material issue, production entry, rejection and rework up to the cut-off, so WIP in the system reflects the floor.
Ask each job worker for a stock statement as on the cut-off date, part number by part number, so differences can be chased before the report.
Tag bins and trolleys at each operation with the part number and the stage reached.
Keep rejects, rework and scrap in marked areas, and weigh the scrap before the count.
Mark customer-supplied material clearly, so it is not counted as yours.
List slow-moving and discontinued part numbers with the reason, so the valuation discussion is quick.
What the count finds
What an auto component stock count usually finds
The six differences that come up most often in component stock, the usual reason, and what the plant can do about each before the next count.
Finding
Usual cause
What to do
Open job-work challans with old dates
Material not returned, or returned without a record
Reconcile challans with each job worker monthly and close them
Raw material short against the books
Scrap above the standard not recorded
Record scrap and rejections by shift; review the BOM scrap allowances
Finished parts for discontinued models
The customer stopped ordering the part number
Write down to net realisable value; seek a settlement from the customer
WIP valued at finished-part cost
No stage-wise costing
Value each stage at the cost incurred up to that stage
Stock at customer warehouses missing from the books
Consignment stock not tracked
Get periodic statements from customers and reconcile them
Scrap sold but not recorded
Weak control over scrap
Weigh and record scrap where it arises and when it is sold
Why scrap and write-offs matter beyond the count
Under section 17(5)(h) of the CGST Act, input tax credit must be reversed on goods lost, stolen, destroyed, written off, or given as gifts or free samples, so rejected parts written off after the count have a GST effect as well as a valuation one. Old open job-work challans can carry a GST consequence too, under the section 143 time limits described above.
Fees
What drives the fee for a component count
A written quote once the plants, the job workers, the stages in scope and the bank's requirements are known. The general cost drivers of a stock audit are under what a stock audit costs on our India-wide stock audit page.
Professional fee
Get a quote
Exl GST and Govt. Charges · final fee after scoping
The quote follows the plants, job workers and stages to be covered, not the size of the loan alone. travel quoted per location
Fees exclude GST and government charges. All fees listed are indicative only and do not constitute a binding offer; the final amount is confirmed after a scoping review and depends on the volume of work and the complexity involved.
What moves the fee for component stock
Plants, stores and job-work sitesHow many premises hold the stock, including every heat treater, plater and machining vendor in scope
Part numbers and operationsHow many part numbers are live and how many operations each passes through
Whether production pausesA count alongside running lines needs a tighter cut-off and more movement records than one over a shutdown
Full count or sampleAs agreed in the scope with you or the bank
State of costing and job-work recordsWhether stage-wise costs and challan records exist, or have to be rebuilt for the count
For a quote, send the number of plants and job workers, the approximate number of part numbers and whether the stock secures a bank limit; the fee and the records list come back in writing.
How it is delivered
Where we count, and who stands behind the report
Patron Accounting accepts stock audits across India and runs them through local field teams that it coordinates; planning, scope and quality review stay with Patron, and a Chartered Accountant reviews and signs off the report.
Stock audits since 2019Stock audits of all kinds since 2019, counted company-wide rather than by industry.
Plants and job workers anywhere in IndiaCounted by local field teams coordinated by Patron, with planning, scope and quality review by Patron. Tell us where the plants, the job workers and any customer warehouses are when you enquire. Work usually starts within 3 to 5 working days of confirmation.
Reviewed and signed off by a CAContent reviewed by Subham Jhunjhunwala, CA Finalist; regulatory and banking statements signed off by CA Sundram Gupta.
Sources used on this page
CGST Act, 2017: section 143 (job work, return periods and their extension) and section 17(5)(h) (credit reversal on goods written off)
ICAI, Standards on Auditing SA 501 (attendance at physical inventory counting) and SA 530 (audit sampling)
Accounting Standards AS 2 and Ind AS 2 (lower of cost and net realisable value; cost formulas); ICDS II
Reserve Bank of India directions and circulars on working capital finance, for the lender's position on stock audits
Ministry of Corporate Affairs, Companies (Auditor's Report) Order, 2020, for the line between a lender's stock audit and the statutory audit
Patron Accounting glossary terms: job work stock, sub-assembly stock, net realisable value, stock ageing
Statements about audit frequency, bank panels, job-worker stock and work in progress in drawing power describe common bank practice; your own sanction letter decides how they apply to you.
Also see
Services that sit next to a component stock audit
The component count is one scope of the stock audit service: the same independent check a lender orders on any stock-secured limit, described there with its rules, its nine-step procedure, the report the bank receives and the records to keep ready. If your stock is not auto components, start there.
Dies, moulds, jigs and fixtures, and the machining centres and presses they run on, sit in the fixed asset register rather than the stock register. Where the bank that holds the stock also finances the plant, it often asks for a fixed asset verification alongside the stock audit, matched to that register.
The report format, the RBI position, how often a stock audit is required and the common deficiencies a bank stock audit finds are covered by the guides linked from the national stock audit page.
Get a quote
Ask for an auto component stock audit quote
Share the number of plants and job workers, the approximate number of part numbers and whether the stock secures a bank limit, and you will receive a quote and a list of records to prepare.
Get a quote for an auto component stock audit
We reply on working days.
Stock that is not auto components, or a different service? Say so in the message and the right team calls instead. By sending this form you agree to our privacy policy. No spam, no sharing of your details.
Prefer to chat?
Message us on WhatsApp with the bank's request, your plants and your job workers, and the stock audit team replies.
A CA reads the bank's request, confirms the plants, the job workers and the stages in scope, and sends the scope, the fee and the records list in writing before any visit is planned.