Work in progress
Banks treat WIP differently: some exclude it from drawing power, others include it with a higher margin set in their credit policy. The auditor reports WIP by stage so the bank can apply its own rule.

Stock Audit
An independent check, usually ordered by your bank, that the stock offered as security for a cash credit or overdraft limit exists, is in saleable condition, belongs to you and is valued correctly. Counted at your premises, reconciled to your books and the stock statement, valued under AS 2, with drawing power recomputed and a signed report to the bank. For borrowers with stock-secured limits, and for the lenders who ask for the audit.
In short
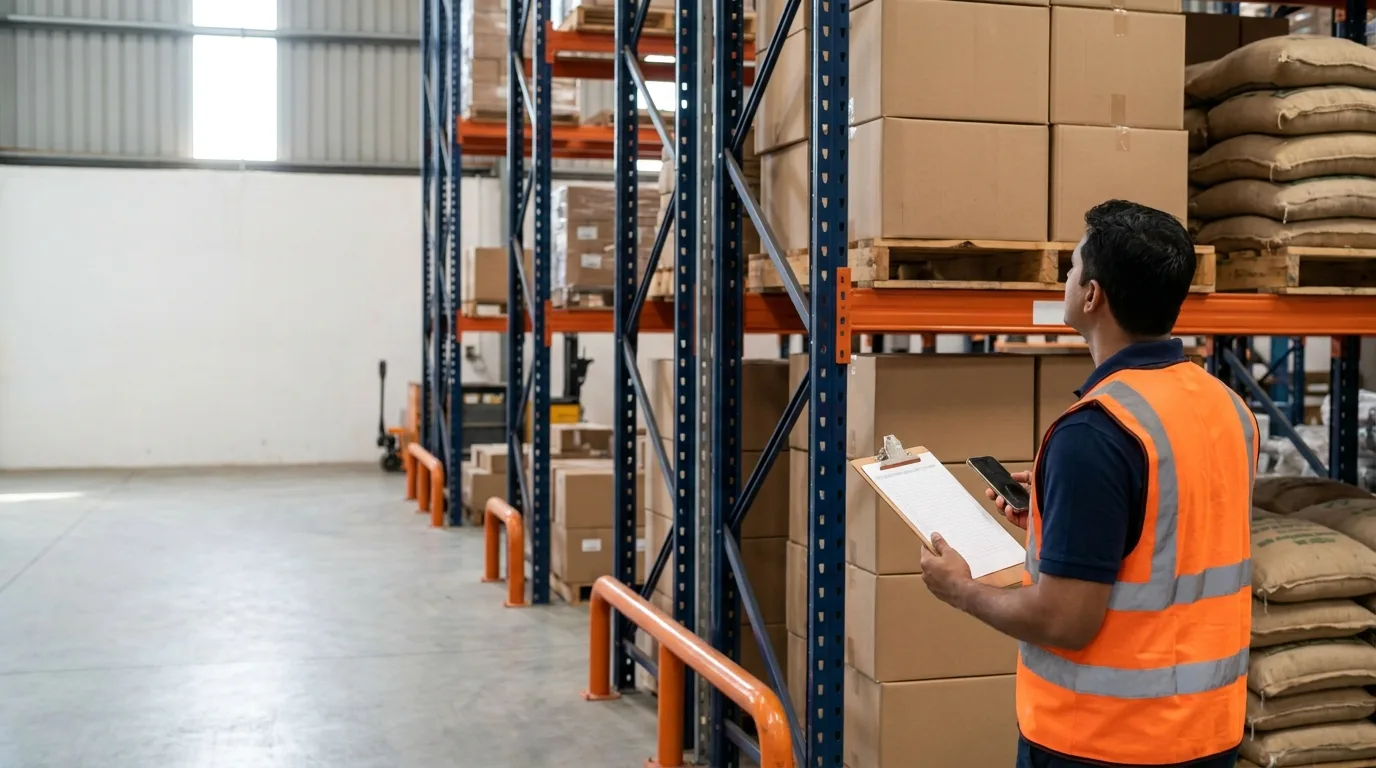
A stock audit (also called an inventory audit or a bank stock audit) is a verification of one asset class: the inventory that secures a working capital loan. It is commissioned by a lender rather than required by the Companies Act, reports to that lender and gives no opinion on the accounts. The auditor counts or test-counts the stock, analyses variances, values it at the lower of cost and net realisable value under AS 2 or Ind AS 2, and signs the report.
Because the bank lends against the stock, it wants an outside person to confirm three things the borrower's own statement cannot prove on its own: that the goods are physically there, that they are worth what the statement says, and that the limit drawn is covered by them.
Each question becomes a part of the report the bank receives (see what the report contains, further down).
When it applies
No statute orders a borrower to have a stock audit; the requirement comes through the bank's sanction letter. Its frequency, commonly quarterly or half-yearly, is set there too.
For regular accounts there is no statutory limit; each bank fixes its threshold in its credit policy and sanction letter. RBI mandates annual stock audits only for NPAs of Rs 5 crore and above. Larger limits often attract more frequent stock audits, sometimes quarterly, depending on the bank's policy. The supervisory frame sits in RBI's directions on asset classification and credit; the trigger that reaches you sits in your own sanction letter. For the RBI position in more detail, read bank stock audit and the RBI rules; for how often the audit comes round, how often a stock audit is required.
On a Patron engagement: the report is reviewed and signed off by a Chartered Accountant.
How it runs
The steps below are for a stock audit ordered by a bank; the exact steps are set by its scope letter and by the size and nature of your stock. When management, a statutory auditor or an insurer orders the check instead, they set the scope, the drawing power step does not apply, and the report goes to them.
The bank appoints the auditor and issues a scope: the borrower, the locations, the statement date to be verified, whether book debts are included and the report format the bank wants. Banks generally accept sample-based verification, with coverage set in that scope.
Bank and auditorThe auditor asks for the sanction letter, the stock statements, the stock register and the other records listed further down this page, so the count can be planned before anyone reaches the site.
Before the visitWhich locations to visit, how to handle goods moving in and out on the count day, and which items to count in full and which to sample. Sample sizes are set by the scope and the assessed risk; where the count is part of an audit of financial statements, SA 530 governs the sampling. A common approach is to count high-value items in full and sample the rest.
Before the visitThe auditor attends the count, observes how it is done, inspects the goods and performs test counts. In an audit of financial statements where inventory is material, SA 501 requires this attendance. The auditor also notes the condition of the goods, how they are stored and identified, and any stock that is damaged, expired or belongs to someone else. Whether the count covers every location, runs during or outside working hours, or takes place in shifts depends on the scope agreed with the bank.
On siteThe count is rarely on the exact statement date, so counted quantities are rolled forward or back to that date using goods received and dispatched in between. The result is compared with the stock register and with the stock statement given to the bank. Every difference is listed and explained or reported.
At the deskUnder AS 2 and Ind AS 2, inventory is carried at the lower of cost and net realisable value. LIFO is not permitted; cost formulas are FIFO or weighted average, with specific identification for non-interchangeable items. The auditor checks the cost records, the ageing of stock and recent selling prices, and reports items whose realisable value has fallen. Writing them down is management's decision.
At the deskDrawing power is worked out as your sanction letter sets it: which stock and debtors are eligible, and the margin on each. Margins and eligibility differ from one sanction to another. The auditor recomputes drawing power on the verified figures and compares it with the figure the bank has been using.
At the deskBefore the report is final, the auditor discusses the differences with you, so that genuine explanations and documents can be considered.
With youThe report is reviewed and signed off by a Chartered Accountant and goes to the bank, usually with a copy to you. Where the bank requires the report to be signed by a practising Chartered Accountant, it carries a UDIN.
To the bankA stock audit can rest on three kinds of count, and the bank's scope letter usually decides which one is used.
Every item at the location is counted, with movements stopped or recorded while the count runs. It gives the most complete result and takes the longest.
Wall-to-wall countThe auditor counts a sample of items, chosen by value and risk, and compares them with the records. Banks generally accept sample-based verification, so this is how most of the physical check in a stock audit is done.
Test countThe business itself counts a small group of items or locations on a rolling schedule, so that every item is counted several times a year. It is a control the business runs between audits; it does not replace the bank's stock audit, but good cycle-count records make the audit quicker.
Cycle countWhich kind applies to your engagement depends on the scope agreed with the bank. To see how sample sizes are worked out, try the audit sampling size calculator (SA 530).
How we count
 Patron Accounting's own stock audit app
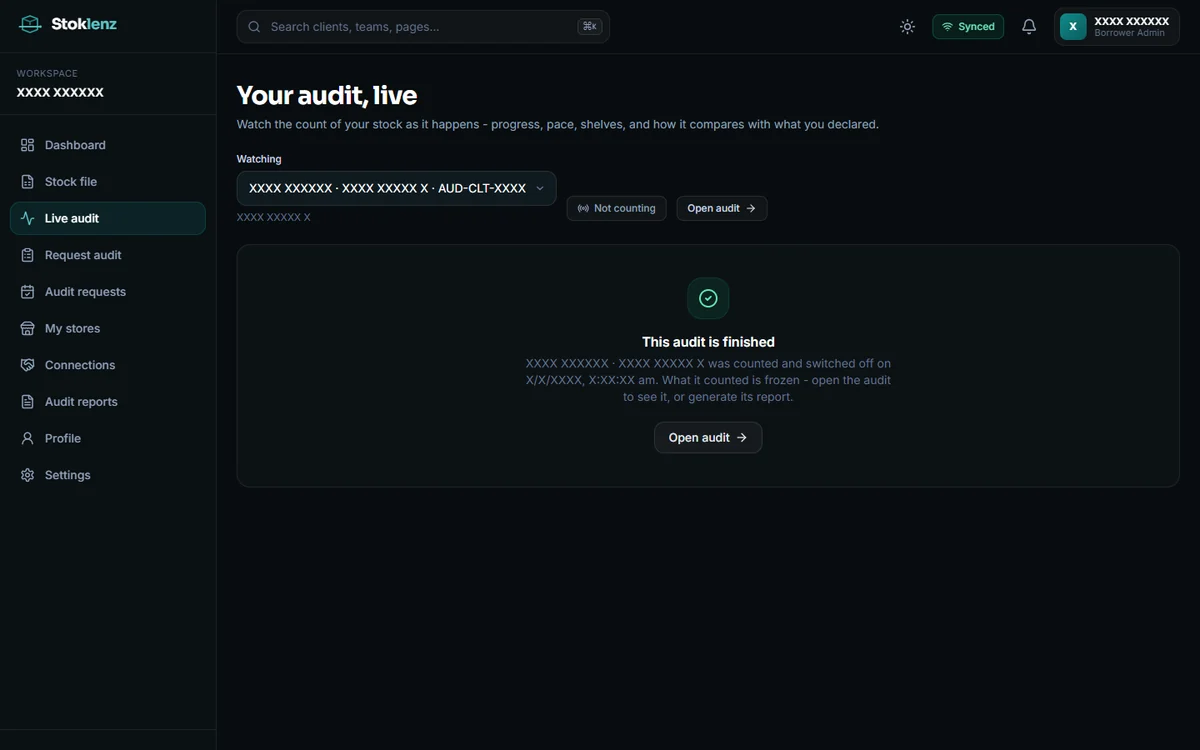
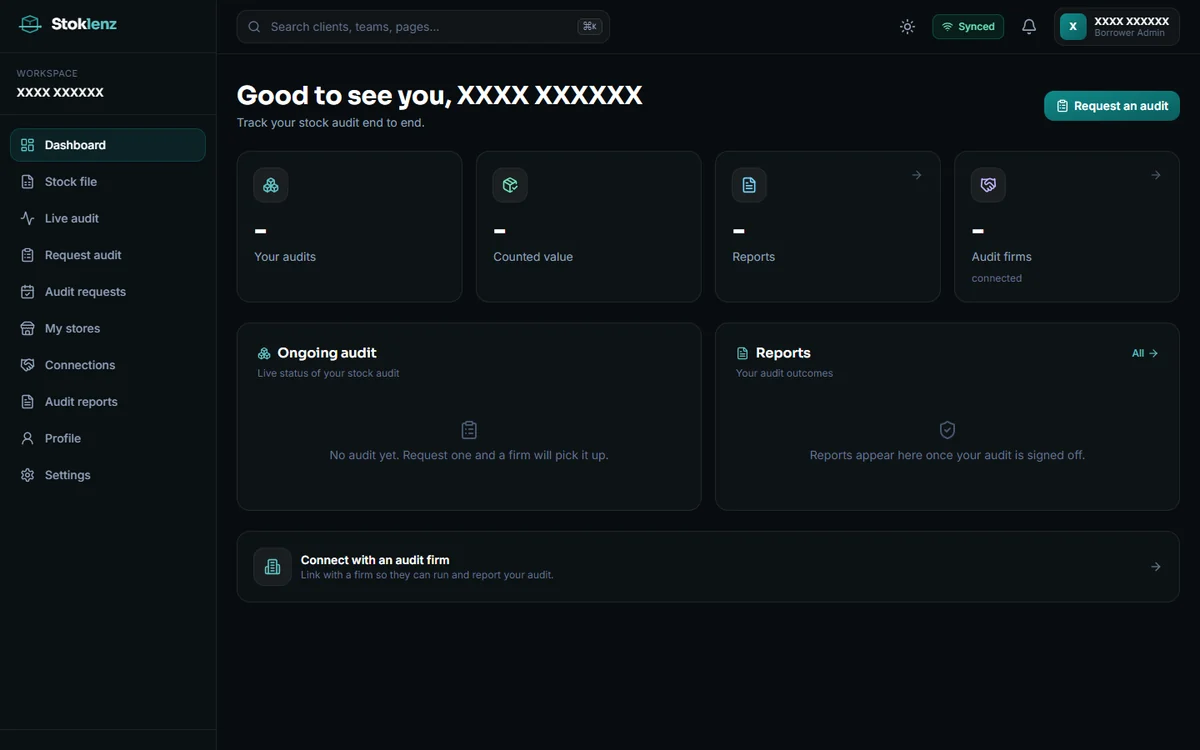
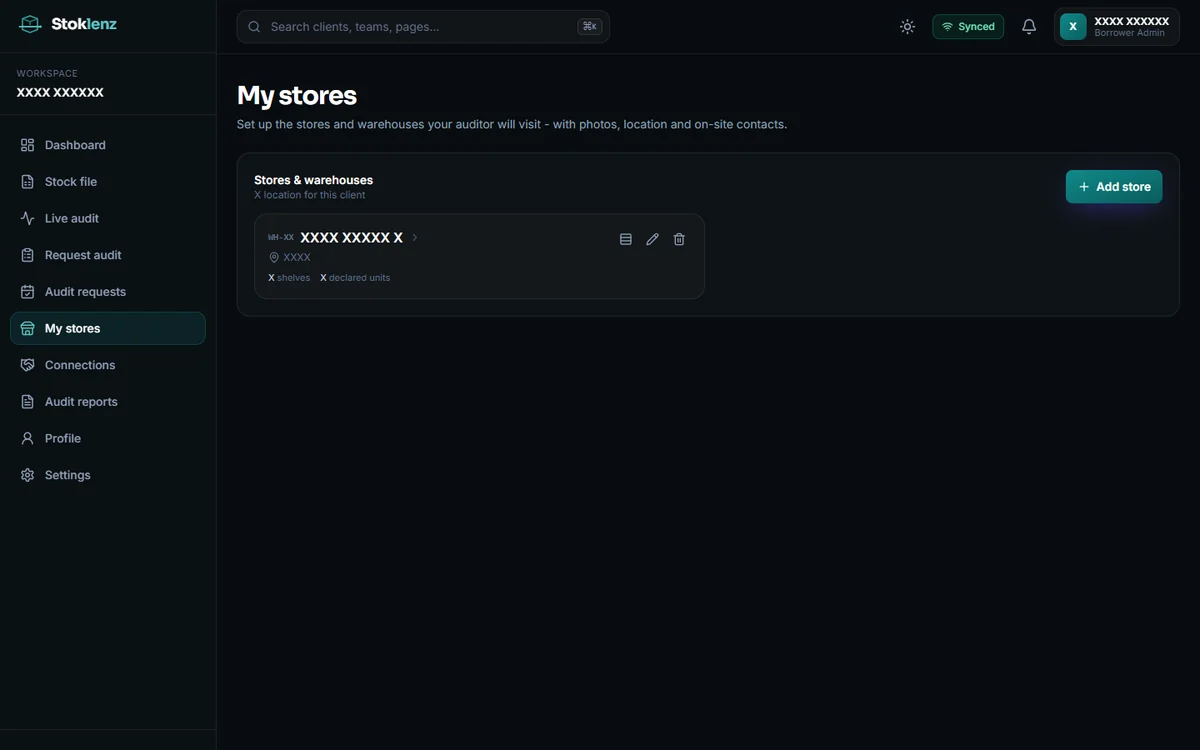
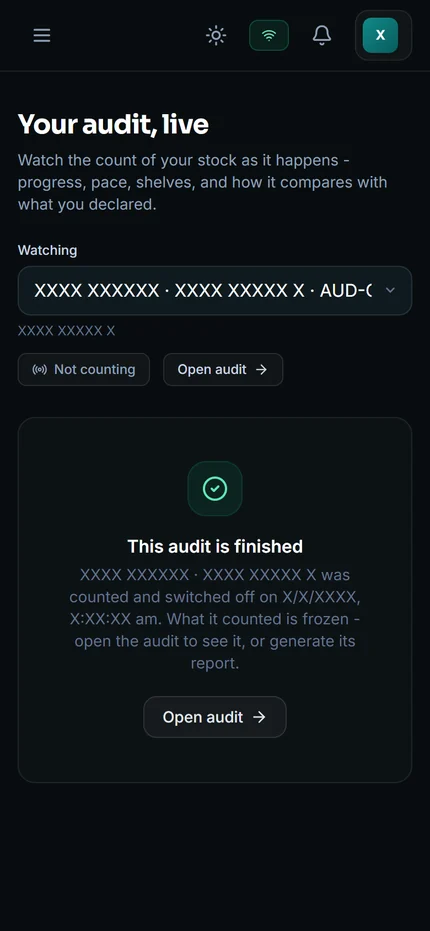
Patron's stock audits are planned, scoped and reviewed by Patron, and the count itself is recorded on Stoklenz, Patron Accounting's own stock audit app. As the crew scans each item, book stock is matched to the physical count on a live board, so the variance list you discuss with the auditor is built during the visit rather than reconstructed from paper afterwards. Scans count only from inside your store or warehouse, the count carries on without a signal and syncs when the connection returns, and the report records where and when the physical count was performed, giving your lender an auditable trail when the report is shared with them.
Stoklenz is part of the service, not a separate product. Ask about it when you send your enquiry at the end of this page.
Where disagreements start
Not all stock can simply be counted and added up. These categories are treated separately in most stock audits.
Banks treat WIP differently: some exclude it from drawing power, others include it with a higher margin set in their credit policy. The auditor reports WIP by stage so the bank can apply its own rule.
Goods sent to a job worker under section 143 of the CGST Act stay the principal's stock, so they are counted in the principal's inventory and confirmed with challans and job-worker statements. Inputs must come back within one year and capital goods within three years, or the principal is treated as having supplied them.
Stock dispatched but not yet received at the other location is checked against invoices, transport documents and, where needed, e-way bills, so that it is neither missed nor counted twice.
Bonded stock stays under customs control under the Customs Act, 1962 until it is cleared for home consumption on payment of duty or re-exported, so it is counted separately.
Goods lying with you on consignment, for repair or awaiting collection by a customer are not yours and are excluded, even when they sit on the same racks.
Listed separately, valued at net realisable value where that is lower than cost, and usually left out of drawing power. Many banks apply ageing cut-offs set in their own policy and sanction letter.
AS 2 and Ind AS 2 allow the retail method and standard costing for convenience, but only where the results approximate actual cost, so the auditor tests that the margin deducted is realistic.
What the bank receives
ICAI's Technical Guide on Stock and Receivables Audit gives an illustrative report format; banks usually prescribe their own format based on it. Whatever the bank's layout, a stock audit report normally covers the parts below. For a part-by-part walk-through, read the stock audit report format for banks.
| Part of the report | What it shows the bank |
|---|---|
| Scope and engagement details | Borrower, bank, limits, statement date verified, dates of the visit and locations covered |
| Method and coverage | How the count was done, which items were counted in full, how the sample was chosen and the share of stock covered |
| Physical, book and statement comparison | Counted quantity against the stock register and against the stock statement given to the bank, with each difference explained |
| Condition and ageing | Damaged, expired, obsolete, slow-moving and non-moving stock, and stock held for or by others |
| Valuation | Cost formula used, cost and net realisable value checks, and any write-down |
| Drawing power | Eligible stock after exclusions, creditors and margins, compared with the drawing power the bank has been using |
| Sanction-term compliance | Insurance cover, declared locations, storage, board display and other stock-related conditions |
| Observations and recommendations | Weaknesses in stock records or controls, and what the borrower should correct |
| Sign-off | Who reviewed and signed off the report, with a UDIN where a practising Chartered Accountant signs it |
Why the drawing power part matters most to the bank. When drawing power falls below the outstanding balance, the account is irregular against its security; verification shows whether it is a reporting error or a real fall in stock. If the outstanding stays above drawing power continuously for 90 days, RBI norms require the bank to classify the account as an NPA.
What we need from you
Having these ready before the visit is the single biggest factor in how smoothly a stock audit runs. Each record is listed with the reason the auditor asks for it.
Rule 56(2) of the CGST Rules requires most registered dealers to keep quantity-wise stock accounts of receipts, supplies, losses and balances; composition dealers are exempt. If your quantity records are weak, sort them out before the auditor arrives, because a count cannot be reconciled to a register that does not exist.
What the count finds
These are the issues that most often reduce drawing power or lead to adverse remarks in a stock audit report, and what a borrower can do about each. For more detail, read common deficiencies in a bank stock audit and how to fix them.
| Problem found | Why it matters to the bank | How to fix it |
|---|---|---|
| Stock statement value higher than the books or the count | Drawing power has been overstated | Prepare the statement from the closing stock in the books for the same date, and reconcile before filing |
| Stock lying at a location not declared to the bank | Under most hypothecation agreements, stock at locations not declared to the bank does not count towards drawing power | Tell the bank about every godown, depot and branch and get it added to the agreement |
| Stock with job workers left in the statement without cover | Many banks leave stock lying with job workers out of drawing power unless the sanction letter or hypothecation agreement expressly covers it | Keep job work challans and job-worker confirmations, and ask the bank to cover such stock if it is material |
| Old, expired or slow-moving stock included | Many banks exclude obsolete, expired or slow-moving stock from drawing power, using ageing cut-offs set in their own policy and sanction letter | Run an ageing report every month and show such stock separately |
| Unpaid stock not deducted | Most banks compute drawing power on paid stock, deducting trade creditors for goods | Deduct creditors for goods in the statement as your sanction letter requires |
| Insurance cover below stock value or for the wrong location | Most banks count only paid, adequately insured stock towards drawing power | Match the policy sum insured and addresses to the stock declared |
| Stock valued at selling price | Inventory is carried at the lower of cost and net realisable value | Value at cost using FIFO or weighted average, and write down only where realisable value is lower |
| Old stock statements | Under RBI's asset-classification directions, drawing power based on a stock statement older than three months is treated as irregular | File statements on the dates in your sanction letter |
| No location-wise quantity records | Quantities cannot be reconciled, so the auditor reports a control weakness | Keep a stock register with receipts, issues and balances for each location |
Late or wrong filing can freeze the limit and attract penal charges; if the outstanding stays above drawing power continuously for 90 days, the account is classified as an NPA. For cash credit, SMA-1 and SMA-2 depend on how long the account is out of order. Deliberately inflating stock statements given to a bank can be prosecuted as cheating or criminal breach of trust under the Bharatiya Nyaya Sanhita, 2023 (sections 318 and 316). Where the bank suspects more than an error, it may order a forensic review: see forensic stock audit and inventory fraud.
Not the same audit
A lender's stock audit reports to the lender. The company's statutory auditor reports separately, to the shareholders.
| Point | Lender's stock audit | Statutory audit (with CARO 2020) |
|---|---|---|
| Who asks for it | The bank, through the sanction letter | The law: the Companies Act for companies |
| Subject | Stock (and book debts if included) that secures the loan | The whole set of financial statements |
| Reports to | The bank | The members of the company |
| Opinion on the accounts | None | Yes |
| Physical count | The core of the work | Where inventory is material, SA 501 requires the statutory auditor to attend the physical count unless that is impracticable |
Other related checks
A Chartered Accountant certifies the periodic stock statement you file with the bank. It is a certificate on a statement, not a count by the bank's auditor. Stock statement certificate
A narrower audit a lender orders on a particular concern, such as one location or one class of stock. What a focused stock audit covers
The same physical-check idea applied to plant, machinery and other fixed assets rather than stock, matched to the fixed asset register. Fixed asset verification
Where inventory is material, SA 501 requires the statutory auditor to attend the physical count unless that is impracticable, and CARO 2020 adds reporting on inventory verification. Under CARO 2020 clause 3(ii)(a), the auditor reports whether management verified inventory at reasonable intervals, whether coverage was appropriate, and whether discrepancies of 10% or more in aggregate per class were noticed and properly dealt with. Under clause 3(ii)(b), where working capital limits above Rs 5 crore in aggregate are sanctioned on current-asset security, the auditor reports whether quarterly returns to banks agree with the books. CARO 2020 applies only to companies under the Companies Act 2013, including foreign companies, with listed exclusions such as one person companies; it does not apply to LLPs, firms or proprietors. For the clause in detail, read CARO 2020 and inventory verification. The audit of the full accounts is the statutory audit, a separate engagement.
Fees
One starting fee, and a quote once we know the locations, the stock and the bank's scope.
Professional fee
Starting from ₹2,499 Exl GST and Govt. Charges · one location, standard scopeThe starting fee covers a single location with a standard bank scope and stock records in reasonable order. The quote rises with the work involved, not with the size of the loan alone.
Travel is not a fixed charge: it is quoted for each location in your written quote.
Work usually starts within 3 to 5 working days of confirmation. How long the report takes depends on the scope and the team needed, and is confirmed with your quote.
Fees exclude GST and government charges. All fees listed are indicative only and do not constitute a binding offer; the final amount is confirmed after a scoping review and depends on the volume of work and the complexity involved.
What moves the cost of any stock audit is the work involved:
How it is delivered
Patron Accounting runs stock audits across India through local field teams coordinated by Patron. Engagement planning, scope and quality review stay with Patron, and the report is reviewed and signed off by a Chartered Accountant.
Sites elsewhere in India are accepted on the same basis; tell us the location when you enquire.
Statements about margins, frequency, panels and exclusions describe common bank practice; your own sanction letter decides how they apply to you.
Read and try
Get a quote
Share the bank's stock audit request or your sanction letter, the number of locations and a rough count of items, and you will receive a quote and a list of the records needed for the visit.
We reply on working days, and we call you back the same day.
Our team will get back to you shortly. No spam.
Message us on WhatsApp with the bank's request and the locations, and the stock audit team replies.
Chat on WhatsAppWorking hours: 9 AM to 6 PM, Monday to Saturday
A CA reads the bank's request and your sanction letter, confirms the locations and the statement date, and sends the scope, the fee and the records list in writing before any visit is planned.