
Talk to an expert

Tell us what you need and we will call you back the same day.

🇮🇳 +91
    Trusted by 10,000+ Businesses

    GSTAT Principal Bench Representation in New Delhi

    Reviewed by CA and CS Team, Patron Accounting LLP ICAI & ICSI Registered| 15+ Years Experience| Last Updated: 16 March 2026 Verify Credentials →

    Dispute Types: Place of supply disputes and inter-state classification under Section 109(5) CGST Act

    Pre-Deposit: 10% additional pre-deposit under Section 112(8) CGST Act - capped at Rs 20 crore

    Limitation: 3-month deadline from order date under Section 112(1) CGST Act 2017

    Specialist: GSTAT matters supported by Subham Jhunjhunwala - CA Finalist, Accounting & Tax Professional

    10,000+ Businesses Served | 4.9 Google Rating | GSTAT Appeal Support by Patron Accounting

    15+ YearsIndustry Experience
    CA & CSCertified Experts
    4.9
    Based on 500+ reviews

    Get Free Consultation

    Talk to a CA/CS expert today

    🇮🇳 +91

      Our team will get back to you shortly. No spam.

      Real Stories from Real People

      Hear how teams across industries use Patron to save time, cut costs, & stay in control.

      Sunny Ashpal
      Sunny Ashpal
      Director - Demandify Media
      Google
      Anjanay Srivastava
      Anjanay Srivastava
      Founder - Hunarsource Consulting
      Google
      Mayur Shewale
      Mayur Shewale
      Founder - Bijasani Traders
      Google
      Ascendancy International
      Ascendancy International
      Owner
      Google

      I've had an outstanding experience working with my CA - Patron Accounting. Their professionalism, attention to detail, and timely communication made the entire process seamless and stress-free.

      I'm glad that I was able to connect with Patron. They took the minimum time to do the calculations based on the details provided by me and were really helpful throughout the process.

      Really a fantastic experience with Patron Accounting especially Shubham, he was extremely great. Knowledgeable person who deserves the 5 star for smooth handling of all documentation.

      Patron Accounting gives the best service related to all account handling of our firm. I am blessed and extremely happy that Patron Accounting assigned us a dedicated point of contact.

      I have called Patron to file ITR for my 5 family members. I worked with Shubham Junjunwala and Amin Jain. It was a smooth process. They understand basics very well and respond promptly.

      From the very beginning, their approach has been highly professional, prompt, and solution-oriented. Every interaction reflected their deep knowledge and commitment to helping clients.

      Very proficient and professional staff. Do fantastic job and instant response. Strongly recommended engaging them for all accounting needs specially for startups and growing businesses.

      I contacted them to file the ITR. Shubham was the POC for me and he was really very professional and giving prompt responses. Highly recommend them for tax and compliance work.

      Join 10,000+ Satisfied Businesses

      10,000+ Businesses Served | 4.9 Google Rating | GSTAT Appeal Support by Patron Accounting

      Talk to an Expert
      10,000+Businesses ServedGST compliance and litigation support across India.
      15+Years ExperienceDeep expertise in IP registration, GST & business compliance.
      50,000+Documents FiledReturns, appeals, and filings handled accurately.
      4.9★Client RatingTrusted by entrepreneurs, startups, and growing businesses.
      ISO CertifiedProfessional standards and documented processes.
      SSL SecureYour financial and business data is fully protected.

      TL;DR

      The GSTAT Principal Bench at New Delhi, constituted under Section 109(3) CGST Act 2017, has exclusive jurisdiction over place of supply disputes under Section 109(5), anti-profiteering matters under Section 171, and NAAR advance ruling appeals from April 2026. Appeals from the Principal Bench go directly to the Supreme Court. Pre-deposit is 10% of disputed tax under Section 112(8), capped at Rs 20 crore. Patron Accounting provides end-to-end Principal Bench representation.

      ParameterDetail
      ForumGSTAT Principal Bench, New Delhi - Section 109(3) CGST Act 2017
      Exclusive JurisdictionPlace of supply (S.109(5)), Anti-profiteering (S.171), NAAR (S.101A/101B)
      Pre-Deposit10% of disputed tax under Section 112(8) - cap Rs 20 crore CGST
      Appeal Limitation3 months from order under Section 112(1) + 1 month condonation
      Appeal RouteDirectly to Supreme Court under Section 117(1)
      Filing Portalefiling.gstat.gov.in - Form GST APL-05
      Professional FeesStarting from INR 49,999 (Excl. GST and Govt. Charges)

      All fees listed are indicative only and do not constitute a binding offer. Final amounts may vary depending on volume and complexity of work.

      The GSTAT Principal Bench Delhi is the highest forum of fact in India for GST disputes - and the only GSTAT bench whose orders are appealed directly to the Supreme Court. Representation at the Principal Bench demands a different calibre of litigation strategy compared to State Bench matters, given its exclusive jurisdiction over place of supply disputes, anti-profiteering proceedings under Section 171 CGST Act, and NAAR advance ruling appeals.

      Patron Accounting's GSTAT practice provides specialist representation at the Principal Bench, combining deep indirect tax litigation experience with strategic pre-deposit advisory under Section 112(8) CGST Act 2017.
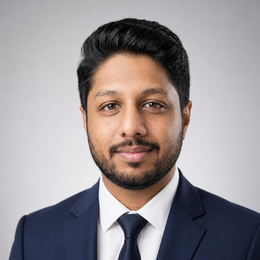
      Subham Jhunjhunwala - CA Finalist and Accounting and Tax Professional at Patron Accounting
      Accounting & Tax Professional

      Subham Jhunjhunwala

      CA Finalist | Graduate

      CA Finalist Accounting & Taxation GST & Compliance

      Subham Jhunjhunwala is a CA Finalist and Accounting & Tax Professional at Patron Accounting LLP, focused on accounting, taxation, and compliance. He works alongside the firm's CA and CS team on GST and GSTAT appeal matters.

      What Is the GSTAT Principal Bench

      Definition: The GSTAT Principal Bench is the apex bench of the Goods and Services Tax Appellate Tribunal, constituted under Section 109(3) of the Central Goods and Services Tax Act 2017 at New Delhi, with exclusive jurisdiction over place of supply disputes, anti-profiteering matters, and advance ruling appeals.

      The Principal Bench consists of the President, one Judicial Member, one Technical Member (Centre), and one Technical Member (State) under Section 109(3) CGST Act 2017. Unlike State Benches, the Principal Bench's orders are challenged directly before the Supreme Court - not the jurisdictional High Court.

      The GSTAT Principal Bench, unlike State Benches constituted under Section 109(6) which hear general GST disputes within their jurisdictional territory, has exclusive pan-India jurisdiction over place of supply disputes under Section 109(5) and anti-profiteering matters under Section 171 - making it the only bench where inter-state tax disputes and consumer benefit enforcement are adjudicated.

      GSTAT (Goods and Services Tax Appellate Tribunal), also referred to as the GST Tribunal or GST Appellate Tribunal, constituted under Section 109 CGST Act 2017 - the Principal Bench at New Delhi is the administrative and jurisdictional apex of this tribunal.

      Principal Bench Place of Supply Anti-Profiteering Section 109(3) - Apex GSTAT Bench

      3 Categories of Cases at the Principal Bench

      Place of Supply Disputes (Section 109(5) Proviso)

      Any appeal where the dispute involves determination of the place of supply under Sections 10 to 14 of the IGST Act 2017 must be heard by the Principal Bench. This covers inter-state vs intra-state classification disputes, export of services vs intermediary classification, OIDAR service place of supply, and cross-border supply determination.

      Anti-Profiteering Matters (Section 171)

      Since October 2024, the GSTAT Principal Bench has taken over jurisdiction from the NAA and CCI to examine whether GST rate reductions and ITC benefits have been passed on to consumers. The Principal Bench hears both new DGAP reports and matters remanded by the Delhi High Court.

      NAAR - Advance Ruling Appeals (Section 101A/101B)

      From April 2026, the Principal Bench functions as the National Appellate Authority for Advance Ruling, adjudicating cases where two or more State Advance Ruling Authorities have issued conflicting rulings on identical questions of law.

      Our 6 Principal Bench Representation Services

      ServiceWhat We Do
      Place of Supply Dispute RepresentationDrafting grounds of appeal, legal submissions, and hearing representation for inter-state supply classification, export of services, and OIDAR disputes
      Anti-Profiteering DefenceResponding to DGAP investigation reports, preparing profiteering computation counter-analysis, and representing businesses in Section 171 proceedings
      NAAR Advance Ruling AppealsFiling appeals under Section 101B where conflicting advance rulings from multiple states create compliance uncertainty for pan-India operations
      Pre-Deposit Calculation and FilingExact computation of the Section 112(8) pre-deposit obligation, application of the Rs 20 crore CGST cap, and securing the Section 112(9) stay of recovery
      Form GST APL-05 FilingEnd-to-end appeal filing on the GSTAT e-filing portal with demand calculation sheet and supporting documents
      Supreme Court Strategy AdvisorySince Principal Bench orders are appealed to the Supreme Court (not HC), we advise on SLP prospects and grounds preservation during the tribunal stage
      Our Process

      7 Steps to File Appeal Before GSTAT Principal Bench

      Our step-by-step process for filing and prosecuting a GSTAT appeal at the Principal Bench in New Delhi

      Step 1

      Confirm Principal Bench Jurisdiction

      Verify whether the dispute involves place of supply (Section 109(5) proviso), anti-profiteering (Section 171), or conflicting advance rulings (Section 101A/101B). If the dispute does not involve these issues, the appeal lies before the relevant State Bench.

      Jurisdiction check Bench verification
      Jurisdiction01
      Step 2

      Obtain the Impugned Order

      Secure a certified copy of the first appellate authority's order under Section 107 CGST Act. For anti-profiteering, obtain the DGAP investigation report and any prior NAA/CCI order.

      Certified copy Complete record
      Order Obtained02
      Step 3

      Calculate Pre-Deposit Under Section 112(8)

      Compute 10% of the remaining disputed tax amount. Verify the Rs 20 crore CGST cap. For anti-profiteering matters, pre-deposit applies to the profiteering amount confirmed.

      10% calculation Rs 20 crore cap
      Pre-Deposit03
      Step 4

      Pay Pre-Deposit via Electronic Cash Ledger

      Make payment via GST portal challan. Electronic Credit Ledger is not permitted. Obtain payment proof for filing.

      Cash Ledger only Payment proof
      Payment Done04
      Step 5

      Prepare Grounds of Appeal

      Draft detailed grounds of appeal, statement of facts, supporting judgments, CBIC circulars, and legal submissions. For place of supply cases, include IGST Act Section 12/13 analysis.

      Legal submissions IGST analysis
      Grounds Ready05
      Step 6

      File Form GST APL-05 on GSTAT Portal

      Register on efiling.gstat.gov.in, prepare the offline utility, complete demand calculation sheet, upload all documents in PDF, pay filing fee via Bharatkosh, and digitally sign.

      E-filing mandatory Bharatkosh fee
      Appeal Filed06
      Step 7

      Confirm Stay and Track Listing

      On successful filing with confirmed pre-deposit, the stay of recovery under Section 112(9) is automatic. Monitor GSTAT cause lists for hearing dates.

      Automatic stay Cause list tracking
      Stay Secured07

      Documents Required for Principal Bench Filing

      • Certified copy of impugned order from first appellate authority
      • Original order of adjudicating authority
      • Form GST APL-01 and Form GST APL-03 (first appeal records)
      • Challan of pre-deposit payment under Section 112(8) via Electronic Cash Ledger
      • Proof of Section 107(6) pre-deposit already paid
      • Grounds of appeal and statement of facts
      • Power of attorney / vakalatnama for authorised representative
      • Supporting CBIC circulars and HC/SC judgments
      • GSTIN and tax liability statements
      • Demand calculation sheet (GSTAT offline utility format)
      • For place of supply: IGST Act Section 12/13 analysis and classification evidence
      • For anti-profiteering: DGAP report, computation counter-analysis, prior NAA/CCI orders
      • For NAAR: conflicting advance rulings from two or more states

      Download our checklist - email sales@patronaccounting.com or call +91 945 945 6700.

      4 Common Challenges at the Principal Bench

      Identifying Principal Bench vs State Bench Jurisdiction

      The most common procedural error is filing a place of supply dispute before a State Bench instead of the Principal Bench - resulting in jurisdictional objections, transfer applications, and lost time within the 3-month limitation window. Patron Accounting conducts jurisdictional analysis at the engagement stage.

      Complex Place of Supply Determination in Digital Services

      A common error is conflating Section 12 (location of supplier) and Section 13 (location of recipient) analysis for cross-border digital services, leading to weak grounds of appeal. Our team structures place of supply arguments with reference to IGST Act provisions and CBIC circulars.

      Anti-Profiteering Computation Methodology Disputes

      DGAP computation methodology - particularly base price selection, product-wise vs entity-wide calculation, and ITC benefit quantification - is the most contested area. Patron Accounting prepares detailed counter-computation analysis.

      Supreme Court Appeal Preservation

      Since Principal Bench orders go directly to the Supreme Court, grounds not raised at the tribunal stage may be difficult to introduce at the SLP stage. Patron Accounting ensures comprehensive ground preservation.

      Illustrative Scenario

      An IT services company with operations in Bangalore and clients across 5 states received a demand of Rs 3.2 crore for place of supply reclassification - the department treating export of services as intermediary services and demanding IGST. The first appellate authority upheld the demand. Patron Accounting's GSTAT team confirmed Principal Bench jurisdiction under Section 109(5), calculated the Section 112(8) pre-deposit at Rs 32 lakh, filed the appeal on the GSTAT e-filing portal with detailed Section 13 IGST Act analysis, and secured the automatic stay of recovery under Section 112(9) for the remaining Rs 2.88 crore.

      Pre-Deposit for Principal Bench Appeals

      Statutory Basis: Section 112(8) CGST Act 2017, as amended by Finance (No. 2) Act, 2024. Pre-deposit is 10% of remaining disputed tax, in addition to the 10% already paid under Section 107(6). Cap: Rs 20 crore CGST.

      ComponentAmount (Illustrative)Basis
      Total demand orderRs 3,20,00,000First appellate authority order
      Disputed tax (IGST)Rs 3,00,00,000Place of supply reclassification
      Pre-deposit S.107(6) - already paidRs 30,00,00010% of disputed tax
      Pre-deposit S.112(8) - payable nowRs 30,00,00010% additional - cap Rs 20 crore
      Total deposited both stagesRs 60,00,000S.107(6) + S.112(8)
      Balance - stayed under S.112(9)Rs 2,60,00,000Automatic stay on GSTAT admission
      Patron Accounting Professional FeesStarting from INR 49,999Excl. GST and Govt. Charges

      All fees listed are indicative only and do not constitute a binding offer. Final amounts may vary depending on volume and complexity of work.

      The 10% deposited under Section 107(6) at the first appellate stage and the 10% deposited under Section 112(8) at the GSTAT stage are not independent obligations - paying the Section 112(8) amount activates the Section 112(9) stay of recovery, protecting the taxpayer from coercive recovery of the remaining balance for the entire duration of the GSTAT proceedings.

      Why Choose Patron Accounting for Principal Bench Representation

      Specialist Support

      Subham Jhunjhunwala, CA Finalist - accounting, taxation, and compliance support, working with the firm's CA and CS team.

      Delhi Office Proximity

      Strategic access to the Principal Bench in New Delhi for physical hearings with dedicated Delhi-based team.

      10,000+ Businesses

      4.9 Google rating, 15+ years of professional practice, offices in Pune, Mumbai, Delhi, and Gurugram.

      SC Pathway Expertise

      Every Principal Bench defence is structured with the Supreme Court appeal pathway in mind - comprehensive ground preservation from day one.

      Three Jurisdiction Expertise

      Place of supply + anti-profiteering + NAAR - the only firm combining all three Principal Bench jurisdiction areas in one dedicated practice.

      Firm-Backed Support

      Backed by Patron Accounting's ICAI and ICSI registered CA and CS team.

      Trusted Across Industries

      “Patron Accounting's GSTAT team understood our pre-deposit exposure immediately. Subham Jhunjhunwala's approach to structuring the grounds of appeal was methodical and thorough.”

      - CFO, Manufacturing Company [Illustrative]

      With offices in Pune, Mumbai, Delhi, and Gurugram, Patron Accounting provides GSTAT representation across the Principal Bench at New Delhi and State Benches including Mumbai, Bangalore, Chennai, Hyderabad, and Ahmedabad.

      Principal Bench vs State Bench vs High Court Writ

      ForumGSTAT Principal BenchGSTAT State BenchHigh Court Writ (Art.226)
      JurisdictionPlace of supply, anti-profiteering, NAARAll other GST disputes within stateJurisdictional error, natural justice
      Pre-Deposit10% under Section 112(8)10% under Section 112(8)No pre-deposit (general)
      Appeal RouteSupreme CourtHigh CourtSupreme Court
      Key PointExclusive for PoS and S.171General jurisdictionNot substitute for GSTAT

      A GSTAT appeal under Section 112 to the Principal Bench is the mandatory remedy for place of supply disputes under the Section 109(5) proviso - unlike a High Court writ under Article 226 which lies only where there is a jurisdictional error or violation of natural justice, and unlike a State Bench filing which lacks jurisdiction over inter-state supply classification matters.

      What cases does the GSTAT Principal Bench hear?

      The Principal Bench has exclusive jurisdiction over place of supply disputes under Section 109(5) CGST Act, anti-profiteering matters under Section 171, and NAAR advance ruling appeals under Sections 101A/101B from April 2026. All other GST disputes are heard by the relevant State Bench.

      Where is the GSTAT Principal Bench located?

      The Principal Bench is constituted at New Delhi under Section 109(3) CGST Act 2017. It is headed by the President of GSTAT, currently Justice (Retd.) Sanjaya Kumar Mishra.

      What is the pre-deposit amount for a GSTAT appeal?

      The pre-deposit is 10% of the remaining disputed tax under Section 112(8) CGST Act, capped at Rs 20 crore CGST. This is in addition to the 10% already paid under Section 107(6), making the total 20% of disputed tax.

      Can the GSTAT appeal deadline be extended?

      Under Section 112(2) CGST Act, the tribunal may condone delay up to 1 additional month beyond the 3-month limit. Beyond 4 months total, the right to appeal is permanently lost.

      Does paying pre-deposit give automatic stay of recovery?

      Yes - under Section 112(9) CGST Act, on filing the appeal with confirmed pre-deposit, recovery of the remaining balance is automatically stayed for the duration of the appeal.

      What is the difference between GSTAT Principal Bench and State Bench?

      The Principal Bench at New Delhi hears place of supply, anti-profiteering, and NAAR matters. State Benches hear all other GST disputes within their jurisdiction. Appeals from the Principal Bench go to the Supreme Court; from State Benches to the jurisdictional High Court.

      How are anti-profiteering cases handled at the Principal Bench?

      Since October 2024, the Principal Bench examines anti-profiteering matters under Section 171 CGST Act, taking over from the NAA and CCI. The DGAP conducts investigations and files reports, which the Principal Bench adjudicates.

      Can I choose which bench hears my GSTAT appeal?

      No - bench allocation is determined by the nature of the dispute. Place of supply matters must go to the Principal Bench under Section 109(5). The President assigns cases across benches via general or special orders.

      Quick Answers

      What is the Principal Bench?
      Apex GSTAT bench at New Delhi under Section 109(3) CGST Act - headed by the President.
      Which cases go to the Principal Bench?
      Place of supply disputes (S.109(5)), anti-profiteering (S.171), and NAAR appeals.
      Where do PB appeals go next?
      Directly to the Supreme Court under Section 117(1) - not the High Court.
      What is the pre-deposit?
      10% of disputed tax under Section 112(8), capped at Rs 20 crore CGST.
      What is the filing deadline?
      3 months from order communication under Section 112(1). Staggered: 30 June 2026.
      Where to file?
      Electronically on efiling.gstat.gov.in using Form GST APL-05.

      Time-Sensitive - 3-Month Deadline Running

      GSTAT appeals must be filed within 3 months of the date of communication of the order under Section 112(1). Condonation up to 1 additional month under Section 112(2). Beyond 4 months, the right to appeal is permanently lost.

      Staggered Filing: For orders communicated before 1 April 2026, deadline is 30 June 2026. After 1 April 2026, normal 3-month limitation applies.

      Every day from the order communication date reduces your available window. Contact Patron Accounting immediately: +91 945 945 6700 | WhatsApp Us

      The 3-Month GSTAT Deadline Is Running - Contact Us Today

      Representation at the GSTAT Principal Bench Delhi requires specialist litigation capability in place of supply analysis under the IGST Act, anti-profiteering computation methodology under Section 171, and advance ruling harmonisation under Section 101A CGST Act 2017. The stakes are elevated because Principal Bench orders are appealed directly to the Supreme Court - grounds not raised at the tribunal stage may be foreclosed.

      Patron Accounting's GSTAT practice is supported by Subham Jhunjhunwala, CA Finalist and Accounting & Tax Professional, working alongside the firm's CA and CS team on every GSTAT engagement.

      Book a Free Consultation - No Obligation.

      Content Created: 16 March 2026  |  Last Updated: 16 March 2026  |  Next Review: 16 June 2026  |  Reviewed By: CA & CS Team, Patron Accounting LLP

      This page is reviewed every 3 months or upon new GSTAT bench constitution notifications, Principal Bench member changes, Finance Act amendments to Section 112, anti-profiteering orders, NAAR operational updates, CBIC circulars on place of supply, or significant HC or SC judgments on Principal Bench jurisdiction.