Work in progress that lasts months
A machine built to order can sit in assembly for a long time, collecting castings, motors, controls and labour. Both its stage of completion and its cost to date need evidence.

Stock Audit · Engineering and machine tools
An independent count and valuation of the bar stock, castings, bought-out items, sub-assemblies, machines under build, finished machines, spares, tools and consumables held by a machine builder or engineering manufacturer, compared with the books and, where the stock secures a loan, with the bank's stock statement. A few high-value machines can sit in assembly for months while thousands of small items pass through the stores and the tool crib every day, and the count has to handle both.
In short
A stock audit, usually ordered by a lender through the sanction letter, confirms that the stock behind a working capital limit exists, is the borrower's and is valued properly. A machine builder's stock tests that from two opposite ends: a handful of machines under build that may be worth more than the whole stores, each at a different stage and tied to one customer's order, and a stores and tool crib holding thousands of small items whose records rarely agree with the bins.
This page covers what machine building changes: machines under build and their net realisable value, sub-assemblies tied to orders, the tool crib and consumables, bin cards against the stores ledger, heavy items that are measured rather than weighed, the records the count needs, the usual findings and what moves the fee. The stock audit itself is described once on our India-wide stock audit page and is not repeated here.
What changes
Six things a count in a machine-building plant has to handle that a count of finished goods on racks never meets.
A machine built to order can sit in assembly for a long time, collecting castings, motors, controls and labour. Both its stage of completion and its cost to date need evidence.
Machines and sub-assemblies built for a particular customer may be worth little to anyone else if that order is cancelled or delayed.
Fasteners, hydraulic and electrical items, bearings and seals are held in the stores in large numbers and are counted by bin, by weight or by pack.
Cutting tools, inserts, gauges and consumables are issued and returned all day, and the line between stock, expense and fixed asset is often blurred.
Spares kept to support machines already in customers' plants can stay on the shelf for years, long after the model has gone out of production.
Customers sometimes supply material or components for their own machines. It sits in your stores but is not your stock, and it has to be kept out of your figures.
Unlike the statutory audit, a lender's stock audit is not required by the Companies Act: it covers one asset class, is commissioned by the lender and reports to it, and gives no opinion on the accounts. Most bank panels require a practising Chartered Accountant firm and some lenders also empanel Cost Accountants; check your bank's panel conditions. Who can sign, and RBI's position, are under when a stock audit is needed on our India-wide stock audit page.
Scope
Every population of stock in the plant, from the bar rack to the finished machine, with the record each one is tested against. The standard parts of a bank stock audit report are under what the stock audit report contains on our India-wide stock audit page.
| Stock category | What is checked |
|---|---|
| Bar stock, plate and castings | Quantity by weight, length or count, identification and condition |
| Bought-out items | Quantity by bin or pack, ageing, and items for designs no longer built |
| Sub-assemblies | Quantity and stage, and whether each belongs to a particular order |
| Machines under build | Stage of completion, cost to date and the order each machine belongs to |
| Finished machines | Units by model and serial number, waiting for dispatch or installation |
| Spares | Quantity, ageing, and whether the machines they support are still in use |
| Tool crib and consumables | Quantity, issue records, and whether each item is stock, expense or a fixed asset |
| Scrap and rework | Quantity, and how it is recorded |
Under AS 2 and Ind AS 2, inventory is carried at the lower of cost and net realisable value. LIFO is not permitted under AS 2, Ind AS 2 or ICDS II, so cost formulas are FIFO or weighted average, with specific identification for items that are not interchangeable.
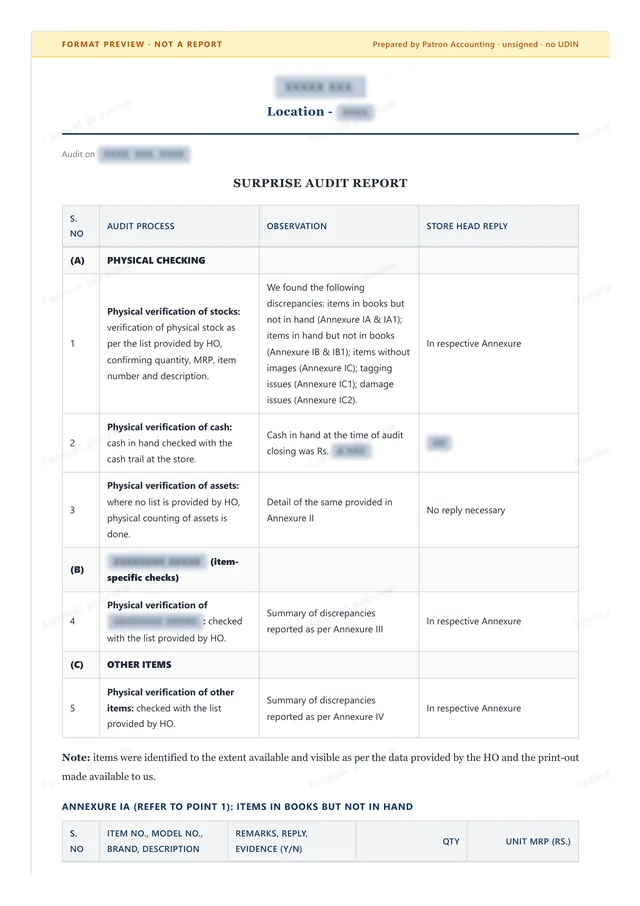
See a sample
Stock audit report
A summary of a stock audit report to the bank, with the stock and book-debt reconciliation and the drawing power.
Values hidden for privacy. Names, numbers and dates are covered. Your own document carries your details.
Download stock audit report sample (PDF) View stock audit report sample
Process
The method depends on the engagement scope: how many shops and stores there are, whether assembly pauses during the count, and whether a full count or a sample is required. These are the steps engineering stock adds to the general stock audit procedure.
Agree how issues to assembly, returns to stores and dispatches during the count will be recorded, and count the stores before the first issue slip of the day so that nothing is counted in both places.
You and the auditorCount bought-out items and spares bin by bin and compare each with its bin card and with the stores ledger, so the count shows which of the two records can be relied on.
Field teamRecord the order each machine belongs to, the main assemblies already fitted and the stage reached, and compare them with the job cost sheet.
Field team and auditorBar stock, plate and large castings that cannot go on a scale are measured and their weight worked out, with the working kept for the reviewer.
Field teamCount tools and consumables in the crib, trace items on issue to the operator or the job, and test how worn and reground tools are recorded.
Field teamWhere inventory is material, SA 501 has the auditor attend the physical count, evaluate management's procedures, inspect the inventory and perform test counts, with sample sizes and test checks designed on the principles of SA 530 (Audit Sampling).
AuditorReconcile with the stores ledger and the job cost sheets, review net realisable value for each machine under build and for slow-moving spares, recompute eligible stock where a bank limit is involved, and report. How long the report takes depends on the scope and the team needed, and is confirmed with your quote.
Patron, to the bankThe engineering task
Four places where an engineering count differs from a stores count anywhere else, a check for the stock that cannot be weighed, and the one item that usually carries the most value.
Cutting tools, inserts, holders and gauges are issued to operators and come back, are reground or are scrapped. The count covers what is in the crib and what is on issue, and checks how worn and reground tools are recorded. Long-lived tools and gauges may belong in the fixed asset register rather than in stock. Term: tool crib.
Oils, coolants, abrasives and welding material are often expensed when bought, yet together they can be a sizeable stock. The count checks that their treatment follows your policy, and that they are not reported as stock for drawing power unless the bank has agreed to it.
Sub-assemblies are built ahead, for several orders or for one machine. The count separates those tied to a live order, those for general use and those for cancelled or delayed orders, which may need a write-down. Term: sub-assembly stock.
Where the stores keep bin cards alongside a computerised stores ledger, the two often disagree. Comparing both with the count shows which record can be trusted. Terms: bin card, stores ledger. Guide: reconciling two records that rarely agree.
Weight check
The weight of a round steel bar follows from its diameter and length, so long bars on a rack can be measured instead of lifted. When the worked-out weight and the stores ledger disagree, the gap points to a wrong size in the records, offcuts that were never recorded, or a shortage.
The factor comes from the density of carbon steel, about 7.85 grams per cubic centimetre; alloy steel, cast iron and non-ferrous bar use their own density. The working is kept so the reviewer can repeat it.
A machine built to order collects castings, motors, controls and labour for months before it ships. Net realisable value is the estimated selling price less the estimated costs to complete and sell (AS 2 para 3.2; Ind AS 2 para 6). For a machine under build that means the order price less the cost still to be spent to finish and deliver it, which is why the count records the stage reached and tests the job cost sheet against it.
Banks treat WIP differently: some exclude it from drawing power, others include it with a higher margin set in their credit policy. Where a machine takes a long time to build, check how interest has been treated in its cost: for borrowing costs, Ind AS 23 uses a 'substantial period of time' test, while ICDS IX treats inventory as a qualifying asset only if it takes 12 months or more to become saleable.
What to keep ready
These are the records a machine builder keeps that a general stock audit does not ask for. The general list a bank expects, from the sanction letter to the insurance policy, is under records to keep ready before the count on our India-wide stock audit page.
Goods sent to a job worker under section 143 of the CGST Act stay the principal's stock, because ownership does not pass, so they are counted in the principal's inventory and confirmed with challans and job-worker statements. Term: job work stock.
What the count finds
The six differences that come up most often in engineering stock, the usual reason, and what the plant can do about each before the next count.
| Finding | Usual cause | What to do |
|---|---|---|
| A machine under build costed far above its order value | Rework, design changes, or cost booked to the wrong job | Review the job cost sheet; write down to net realisable value |
| Sub-assemblies for cancelled orders | The order was cancelled after the build started | Identify them, reuse where possible, otherwise write down |
| Stores ledger and bin cards disagree | Issues posted in one record and not the other | Keep one record; post issues on the day |
| Tools on issue that cannot be traced | Weak control over the crib | Issue against an operator and a job; count the crib regularly |
| Old spares for machines no longer supported | No ageing review | Review spares ageing and write down the slow movers |
| Customer free-issue material in the stock figures | Not tagged when it arrived | Tag and record customer material separately |
Many banks exclude obsolete, expired or slow-moving stock from drawing power, using ageing cut-offs set in their own policy and sanction letter. Spares for machines no longer supported and sub-assemblies left from cancelled orders are listed with their age, so the bank can apply its own cut-off and the write-down is made before the bank asks.
Fees
A written quote once the shops, the stores, the machines under build and the bank's requirements are known. The general cost drivers of a stock audit are under what a stock audit costs on our India-wide stock audit page.
Professional fee
Get a quote Exl GST and Govt. Charges · final fee after scopingThe quote follows the stores items, the machines under build and the state of the records, not the size of the loan alone. travel quoted per location
Fees exclude GST and government charges. All fees listed are indicative only and do not constitute a binding offer; the final amount is confirmed after a scoping review and depends on the volume of work and the complexity involved.
For a quote, send the number of shops and stores, the machines under build and whether the stock secures a bank limit; the fee and the records list come back in writing.
How it is delivered
Patron Accounting takes on stock audits anywhere in India and has them carried out by local field teams it coordinates, keeping the planning, the scope and the quality review itself; a Chartered Accountant reviews and signs off the report.
Statements about audit frequency, bank panels, work in progress and ageing exclusions describe common bank practice; your own sanction letter decides how they apply to you. The bar weight check is arithmetic from the density of carbon steel.
Read
The report format, the RBI position, how often a stock audit is required and the common deficiencies a bank stock audit finds are covered by the guides linked from the national stock audit page.
Get a quote
Share the number of shops and stores, the number of machines under build and whether the stock secures a bank limit, and you will receive a quote and a list of records to prepare.
We reply on working days.
Stock that is not engineering or machine tools, or a different service? Say so in the message and the right team calls instead. By sending this form you agree to our privacy policy. No spam, no sharing of your details.
Message us on WhatsApp with the bank's request, your shops and stores and the machines under build, and the stock audit team replies.
Chat on WhatsAppWorking hours: Monday to Saturday, 9 AM to 6 PM.
A CA reads the bank's request, confirms the shops, the stores and the machines in scope, and sends the scope, the fee and the records list in writing before any visit is planned.