
Income Tax & ITR
ITR Filing for Salary
File your salaried return with a CA; your Form 16 checked against your AIS and Form 26AS, your tax worked out under both regimes, and every employer's salary included if you changed jobs.
- Form 16 checked against AIS and Form 26AS Your employer's certificate compared with what the department already holds
- Every employer's salary added up If you changed jobs, each Form 16 is included so nothing is missed or counted twice
- Old and new regime compared Your tax worked out both ways, with the lower one shown
- Right form, filed and e-verified The form chosen for your income, the return filed and verification completed
In short
What salaried ITR filing covers
If you earn a salary, your employer deducts tax every month and gives you a Form 16 at the end of the year. Your income-tax return is your own statement to the department. It brings together your salary, any other income, your deductions and the tax already deducted, and shows whether you owe more or should get a refund.
This service is for
- employees with one employer and a single Form 16
- people who changed jobs and have more than one Form 16
- employees with shares or stock options from their employer
- salaried people who also sold shares, mutual funds or property during the year
- employees with income or assets outside India
When we file your return, the work covers
- checking your Form 16 against your AIS and Form 26AS
- adding up salary from every employer, if you had more than one
- working out your tax under the old and the new regime
- claiming the deductions you are entitled to
- choosing the right form, filing the return and helping you e-verify it
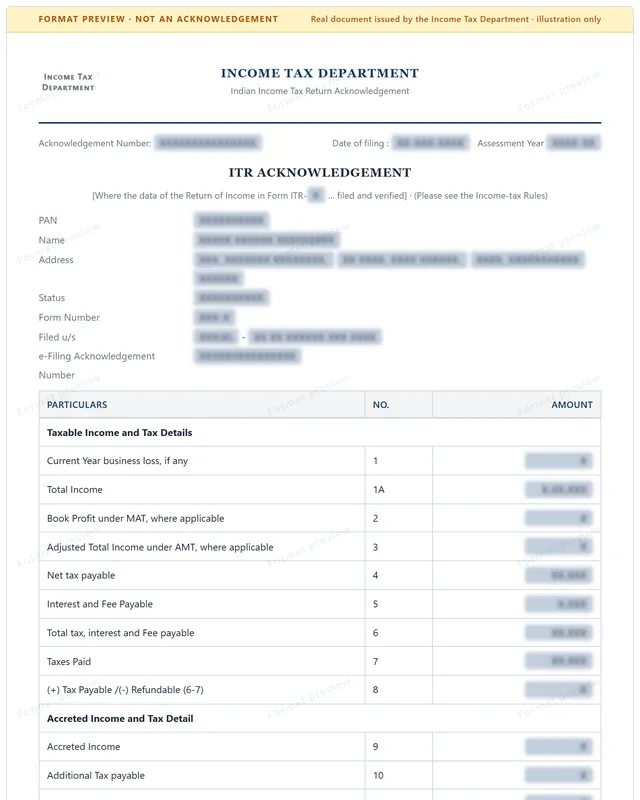
See a sample
ITR acknowledgement
The acknowledgement that an income-tax return was filed.
- Issued by
- Income Tax Department, through the e-filing portal
- When you get it
- Right after the return is filed.
Values hidden for privacy. Names, numbers and dates are covered. Your own document carries your details.
Download ITR acknowledgement sample (PDF) View ITR acknowledgement sample
Who it applies to
Do you need to file, and which form
In general, you need to file if your income is above the basic exemption limit:
| Regime | Who | Basic exemption limit |
|---|---|---|
| New regime | Any age | ₹4,00,000 |
| Old regime | Below 60 years | ₹2,50,000 |
| Old regime | Resident, 60 to 79 years | ₹3,00,000 |
| Old regime | Resident, 80 years or more | ₹5,00,000 |
Same limits for FY 2025-26 and tax year 2026-27 (Finance Act, 2026).
TDS already deducted does not mean you can skip the return
If your income is above the limit, you still file, and filing is also how you get back any extra tax your employer or bank deducted.
You must file if your total income, before deductions such as 80C to 80U and certain exemptions, is above the basic exemption limit. Even below that limit, you must file if in the year you deposited more than ₹1 crore in current accounts, spent more than ₹2 lakh on foreign travel, paid more than ₹1 lakh for electricity, had business turnover above ₹60 lakh or professional receipts above ₹10 lakh, had TDS and TCS of ₹25,000 or more (₹50,000 for a resident aged 60 or more), or deposited ₹50 lakh or more in savings accounts. A resident (other than not ordinarily resident) who holds or benefits from an asset outside India, or can sign in a foreign account, must also file. To carry forward a business or capital-gains loss, or to claim a refund, you need to file a return. (FY 2025-26: 1961 Act section 139(1) and its provisos, with rule 12AB; tax year 2026-27: The corresponding provision of the 2025 Act, with rule 163 of the Income-tax Rules, 2026.)
Which form
Most salaried people use one of the two simplest forms. You need a fuller form if, for example, you have capital gains, foreign assets, or total income above ₹50 lakh.
Salary, one employer or several, and the usual other income.
For example, if you have:
- capital gains
- foreign assets
- total income above ₹50 lakh
For FY 2025-26 and tax year 2026-27, ITR-1 is for a resident individual (not RNOR) with total income up to ₹50 lakh from salary or pension, house property, other sources such as interest, agricultural income up to ₹5,000, and long-term gains on listed shares or equity funds up to ₹1.25 lakh. It cannot be used by a company director, or if you hold unlisted shares, have foreign assets or foreign income, have tax deferred on start-up stock options, or have losses brought forward or carried forward. For FY 2025-26 it also cannot be used if you have short-term capital gains. ITR-2 is for individuals and HUFs with no business or professional income who cannot use ITR-1.
How we work
How we file a salaried return
The eight steps, in the order they happen.
- Collect your documents
Form 16 from each employer, your AIS and Form 26AS, and statements for any shares, mutual funds or property you sold.
- Match AIS and Form 26AS
We compare the TDS and income in your AIS and Form 26AS with your Form 16 and records. Wrong entries in the AIS can be corrected through feedback on the portal before you file.
- Compare the two regimes
We work out your tax under the old and the new regime side by side and show you which is lower. If you have only salary income, you choose the regime in the return itself each year.
For FY 2025-26 the new regime is the default, and you can choose the old regime in the return as long as it is filed by the due date. For tax year 2026-27, you opt out of the new regime in the return you file for that year (the corresponding provision of the 2025 Act).
- Choose the form
Based on your income, we pick the form that fits.
- Add up salary from every employer
If you changed jobs, each employer gave you a separate Form 16, and each may have treated your salary as if it were the only one. We add the salary from every employer and work out the tax on the total, so nothing is missed or counted twice.
For a step-by-step guide, read How to File ITR with Multiple Form 16.
- Handle shares, stock options and capital gains
Stock options and shares from your employer, and any sales of shares, funds or property, are reported in the right parts of the return.
Shares or stock options from your employer are taxed as salary when allotted. The taxable value is the fair market value on the date you exercise the option, less what you paid (FY 2025-26: 1961 Act section 17(2)(vi); tax year 2026-27: The corresponding provision of the 2025 Act). If your employer is an eligible start-up, the tax on this can be deferred to within 14 days of the earliest of 48 months from the end of the assessment year, the sale of the shares, or your leaving the employer. When you sell, listed equity shares and equity-fund units held for more than 12 months are long-term and taxed at 12.5% on gains above ₹1.25 lakh; held 12 months or less, gains on STT-paid listed equity are taxed at 20%. Land and buildings are long-term after more than 24 months and taxed at 12.5%; a resident individual or HUF may instead choose 20% with indexation for land or buildings bought before 23 July 2024. Debt-fund units, unlisted shares and older purchases follow their own rules.
- Work out the tax and validate
We apply the rebate where you qualify, pay any balance tax before filing, and clear every error the portal's checks raise.
- File and e-verify
The return is filed by the due date and e-verified, for example through Aadhaar OTP or net banking.
For FY 2025-26 returns, e-verify within 30 days of uploading the return (CBDT Notification No. 2/2024). If you verify later, the date of verification is treated as the date of filing, with the late-filing consequences that follow. For tax year 2026-27, follow the time limit notified for that year.
Old or new
Old or new regime for salaried people
The new regime is the default. It has lower rates but allows few deductions. The old regime has higher rates but lets you claim deductions such as investments, health insurance, rent allowance and home loan interest.
Default
New regime slabs
Any age
| Up to ₹4,00,000 | Nil |
|---|---|
| ₹4,00,001 to 8,00,000 | 5% |
| ₹8,00,001 to 12,00,000 | 10% |
| ₹12,00,001 to 16,00,000 | 15% |
| ₹16,00,001 to 20,00,000 | 20% |
| ₹20,00,001 to 24,00,000 | 25% |
| Above ₹24,00,000 | 30% |
Optional
Old regime slabs
Below 60 years
| Up to ₹2,50,000 | Nil |
|---|---|
| ₹2,50,001 to 5,00,000 | 5% |
| ₹5,00,001 to 10,00,000 | 20% |
| Above ₹10,00,000 | 30% |
Residents aged 60 to 79 pay nil up to ₹3,00,000, and residents aged 80 or more pay nil up to ₹5,00,000, with the same rates above.
Slabs are the same for FY 2025-26 and tax year 2026-27. A 4% cess is added on the tax (and any surcharge).
Rebate
Under the new regime, the rebate cannot be used against tax on income taxed at special rates, such as some capital gains.
Deductions that matter most for salary
- Standard deduction for salary ₹75,000 under the new regime and ₹50,000 under the old regime, limited to your salary, in both FY 2025-26 (1961 Act s.16(ia)) and tax year 2026-27 (the corresponding provision of the 2025 Act).
- Rent allowance (HRA) HRA exemption is available only under the old regime. The exempt amount is the least of the HRA received, the rent paid minus 10% of salary, and 50% of salary in Mumbai, Kolkata, Delhi or Chennai (40% elsewhere) for FY 2025-26 (1961 Act section 10(13A) with rule 2A). For tax year 2026-27 the 50% rate also covers Hyderabad, Pune, Ahmedabad and Bengaluru (rule 279 of the Income-tax Rules, 2026).
- Home loan on the house you live in Under the old regime, interest on a loan to buy or build the house you live in can be deducted up to ₹2,00,000 a year. Under the new regime, this interest is not allowed for a self-occupied house.
Want to compare both regimes for your own salary? Use our income tax calculator.
What to keep ready
Documents to keep ready
Four items for every salaried return, and three more depending on what happened in your year.
Always For every salaried return
- 01PAN and Aadhaar
- 02Form 16 from each employer you worked for during the year
- 03Your AIS and Form 26AS
- 04Bank account details for any refund
If it applies Depending on your year
- 05If you use the old regime Proof of investments, health insurance premiums, rent receipts and the home loan interest certificate
- 06If you sold shares, funds or property Broker statements, mutual fund statements and the sale and purchase deeds
- 07If you have shares from a foreign parent company The stock plan statement
Dates
Due date
This is the due date for people without business or professional income.
| Return | Due date |
|---|---|
| FY 2025-26 (1961 Act) | 31 July 2026 |
| Tax year 2026-27 (2025 Act) | 31 July 2027 |
If you also have business or professional income, a later date applies; see Income Tax Return Filing.
Filed late or missed the date?
You can still file after the due date, but what it costs and how long you have are set by law for each year.
For FY 2025-26, the late fee is ₹5,000, or ₹1,000 if total income is not more than ₹5 lakh (1961 Act s.234F). A belated return can be filed by 31 December 2026, or before the assessment is completed if that is earlier. A revised return can be filed by 31 March 2027, or before the assessment is completed. Revising after 31 December 2026 costs ₹1,000 if total income is up to ₹5 lakh, or ₹5,000 otherwise.
For tax year 2026-27, the same fees apply under 2025 Act. The belated return deadline is 31 December 2027 and the revised return deadline is 31 March 2028.
What it costs
Fee
The fee depends on what your return covers: for example more than one employer, stock options, capital gains or foreign assets.
Professional fee
One starting fee; the final fee follows what your return covers.
What moves the fee
- More than one employer
- Stock options
- Capital gains
- Foreign assets
Send us your Form 16 and tell us what else happened this year, and we will tell you what the filing will cost.
Questions
Frequently asked questions
The questions salaried people ask most before they send us a return.
Is Form 16 the same as an ITR?
No. Form 16 is a certificate your employer gives you. It shows the salary paid and the tax the employer deducted and deposited. Your income-tax return is your own filing with the Income Tax Department, covering all your income for the year. Form 16 is one of the main documents you use to prepare the return, but receiving it does not mean your return has been filed.
Which deductions can I claim under the old regime?
Under the old regime you can claim Section 80C up to ₹1.5 lakh (PPF, ELSS, EPF, LIC premium and children's tuition fees). You can also claim Section 80D for health insurance for yourself, your spouse, children and parents, Section 80CCD(1B) for NPS up to ₹50,000, and others such as 80E and 80G, along with HRA exemption and home loan interest. Most of these are not available under the new regime.
Do I need my landlord's PAN to claim HRA?
Yes, if the rent you pay is more than ₹1 lakh a year. Keep the rent receipts and the lease agreement as well, since HRA exemption is claimed only under the old regime.
I changed jobs this year. How do I avoid a tax shortfall?
Give your new employer Form 12B with the salary and tax details from your previous employer. If you do not, the new employer works out TDS only on the salary it pays, tax is under-deducted, and the shortfall falls due when you file. In the return, the salary and TDS from every Form 16 are added together and any balance is paid as self-assessment tax before filing.
Can I get a refund if I did not declare my investments to my employer?
Yes. If you did not give your employer proof of investments in time, too much tax may have been deducted. Claiming those deductions in your return, under the old regime, produces a refund of the excess TDS.
Is professional tax deducted from salary everywhere?
No. Professional tax is a state levy. Haryana does not levy it, so salary TDS is the only deduction for employees there. Employees in Mumbai pay ₹2,500 a year, in Bengaluru ₹2,500 a year (₹200 a month and ₹300 in February), and in Chennai an amount that varies.
Get a quote
File your salaried return with a CA
Send us your Form 16 and tell us what else happened this year: a job change, a sale of shares, a new home loan. We will tell you which form you need and what the filing will cost.
Get a quote
Leave your details and we will call you back.
By sending this form you agree to our privacy policy.
What you get back
- Which form you need
- What the filing will cost
Sources
- Income Tax Department, section 139 (1961 Act), who must file
- Income Tax Department, rule 12AB (1962 Rules), other filing conditions
- Income Tax Department, section 17 (1961 Act), stock options as a perquisite
- Income Tax Department, section 192 (1961 Act), start-up ESOP tax deferral
- Income Tax Department, rule 2A (1962 Rules), HRA exemption
- e-Filing portal: 30-day e-verification timeline (Notification No. 2/2024)
- Finance Act, 2026: due dates (s.5, s.66), revised-return windows and fees, First Schedule slabs, exemption limits
- Memorandum to Finance Bill 2026, Part A, rates and cess
- Memorandum to Finance Bill 2025: rebate
- e-Filing portal help, AY 2026-27: form eligibility, regime choice, rebate and house-property tables
- Income-tax Act, 2025: standard deduction (the corresponding provision), rebate (the corresponding provision), interest cap (the corresponding provision), new regime (s.202), returns (s.263), fees (the corresponding provision)
- Income-tax Rules, 2026, return forms (rule 164): incometaxindia.gov.in (Income-tax Rules, 2026)
- Memorandum to Finance (No. 2) Bill 2024, standard deduction
- Income Tax Department, "Penalties and Prosecutions", late fee (s.234F)