Talk to an Expert
Talk to an Expert ✆ +91 945 945 6700
Trusted by 10,000+ Businesses

GSTAT Appeal: Exporters: Resolve Conflicting GST Rulings at GSTAT

Reviewed by CA and CS Team, Patron Accounting LLP ICAI & ICSI Registered| 15+ Years Experience| Last Updated: 16 March 2026 Verify Credentials →

Dispute Types: IGST refund rejection and inverted duty structure disputes under Section 54 CGST Act

Pre-Deposit: 10% pre-deposit at GSTAT stage under Section 112(8) CGST Act - capped at Rs 20 crore

Deadline: 3-month appeal deadline from order date under Section 112(1) CGST Act 2017

Specialist: GSTAT matters supported by Subham Jhunjhunwala - CA Finalist, Accounting & Tax Professional

10,000+ Businesses Served | 4.9 Google Rating | GSTAT Appeal Support by Patron Accounting

15+ YearsIndustry Experience
CA & CSCertified Experts
4.9
Based on 500+ reviews

Get Free Consultation

Talk to a CA/CS expert today

🇮🇳 +91

    Our team will get back to you shortly. No spam.

    Real Stories from Real People

    Hear how teams across industries use Patron to save time, cut costs, & stay in control.

    Sunny Ashpal
    Sunny Ashpal
    Director - Demandify Media
    Google
    Anjanay Srivastava
    Anjanay Srivastava
    Founder - Hunarsource Consulting
    Google
    Mayur Shewale
    Mayur Shewale
    Founder - Bijasani Traders
    Google
    Ascendancy International
    Ascendancy International
    Owner
    Google

    I've had an outstanding experience working with my CA - Patron Accounting. Their professionalism, attention to detail, and timely communication made the entire process seamless and stress-free.

    I'm glad that I was able to connect with Patron. They took the minimum time to do the calculations based on the details provided by me and were really helpful throughout the process.

    Really a fantastic experience with Patron Accounting especially Shubham, he was extremely great. Knowledgeable person who deserves the 5 star for smooth handling of all documentation.

    Patron Accounting gives the best service related to all account handling of our firm. I am blessed and extremely happy that Patron Accounting assigned us a dedicated point of contact.

    I have called Patron to file ITR for my 5 family members. I worked with Shubham Junjunwala and Amin Jain. It was a smooth process. They understand basics very well and respond promptly.

    From the very beginning, their approach has been highly professional, prompt, and solution-oriented. Every interaction reflected their deep knowledge and commitment to helping clients.

    Very proficient and professional staff. Do fantastic job and instant response. Strongly recommended engaging them for all accounting needs specially for startups and growing businesses.

    I contacted them to file the ITR. Shubham was the POC for me and he was really very professional and giving prompt responses. Highly recommend them for tax and compliance work.

    Join 10,000+ Satisfied Businesses

    10,000+ Businesses Served | 4.9 Google Rating | GSTAT Appeal Support by Patron Accounting

    Talk to an Expert
    10,000+Businesses ServedGST compliance and litigation support across India.
    15+Years ExperienceDeep expertise in IP registration, GST & business compliance.
    50,000+Documents FiledReturns, appeals, and filings handled accurately.
    4.9★Client RatingTrusted by entrepreneurs, startups, and growing businesses.
    ISO CertifiedProfessional standards and documented processes.
    SSL SecureYour financial and business data is fully protected.

    GSTAT Appeal for Exporters - Overview

    TL;DR: 1. File GSTAT appeal within 3 months under Section 112(1) CGST Act. 2. Pay 10% pre-deposit on disputed refund amount under Section 112(8) - capped at Rs 20 crore. 3. Contact Patron Accounting for IGST refund rejection and export dispute representation.

    ParameterDetails
    Industry FocusIGST refund rejection (Rule 96), LUT/ITC refund (Rule 89), inverted duty (Section 54(3)), intermediary classification (Section 2(13) IGST)
    Pre-Deposit10% of disputed tax under S.112(8) - capped at Rs 20 crore CGST
    Time Limit3 months from order communication under S.112(1)
    Stay of RecoveryAutomatic under S.112(9) on filing with pre-deposit
    Filing Portalefiling.gstat.gov.in via Form GST APL-05
    Backlog Deadline30 June 2026 for pre-1 April 2026 orders

    Exporters facing rejection of IGST refund claims, denial of ITC refund on zero-rated supplies under LUT, or inverted duty structure refund disputes now have a dedicated appellate remedy through GSTAT. GSTAT appeal for exporter refund rejection under Section 112 CGST Act 2017 requires specialist representation combining deep knowledge of export GST compliance - Section 54 refund procedures, Rule 89 and Rule 96 mechanisms, LUT bond requirements - with tribunal litigation strategy. Patron Accounting provides this through our GSTAT practice.
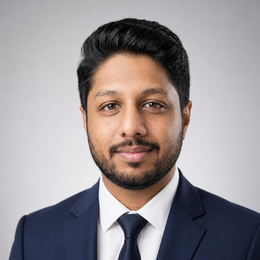
    Subham Jhunjhunwala - CA Finalist and Accounting and Tax Professional at Patron Accounting
    Accounting & Tax Professional

    Subham Jhunjhunwala

    CA Finalist | Graduate

    CA Finalist Accounting & Taxation GST & Compliance

    Subham Jhunjhunwala is a CA Finalist and Accounting & Tax Professional at Patron Accounting LLP, focused on accounting, taxation, and compliance. He works alongside the firm's CA and CS team on GST and GSTAT appeal matters.

    What Is a GSTAT Appeal for Exporter Refund Rejection?

    Definition: An exporter refund rejection under Section 54 of the Central Goods and Services Tax Act 2017 occurs when the proper officer denies a refund claim for IGST paid on exports, unutilised ITC on zero-rated supplies under LUT, or accumulated credit arising from inverted duty structure.

    When the first appellate authority under Section 107 upholds a refund rejection - whether for IGST-paid exports under Rule 96 or ITC refund under Rule 89 - the exporter may file a second appeal before GSTAT under Section 112 within 3 months.

    GSTAT vs Commissioner (Appeals): GSTAT, unlike the Commissioner (Appeals) under Section 107, is a judicial body - its orders carry the force of a court decree, making it the first genuinely independent forum for resolving export refund disputes.

    Key Terms:

    • Zero-rated Supply - Exports under Section 16 IGST Act, eligible for IGST or ITC refund
    • LUT (Letter of Undertaking) - Export without IGST under Rule 96A, refund on ITC
    • Inverted Duty Structure - Higher input rate than output, ITC refund under Section 54(3)
    • Rule 96 - IGST refund on exports (shipping bill as application)
    • Rule 89 - ITC refund for zero-rated supplies under LUT
    Export BusinessZero-rated - S.16 IGST IGST RefundRule 96 ITC Refund LUTRule 89 Inverted DutyS.54(3) ✗Refund Rejected GSTAT Appeal - Section 11210% Pre-deposit | 3-Month Deadline | Auto Stay Export Refund Rejection Types Leading to GSTAT Appeal

    Who Should File a GSTAT Appeal for Export Refund Rejection

    Exporters of goods, exporters of services, merchant exporters, 100% EOUs, and SEZ units that have received an adverse order from the Commissioner (Appeals) under Section 107 CGST Act should consider filing a GSTAT appeal. Common triggers include:

    • IGST refund rejection on exports (Rule 96) - Shipping bill or GSTR-1/3B mismatch
    • ITC refund denial on zero-rated supplies under LUT (Rule 89) - Computation disputes
    • Inverted duty structure refund denials under Section 54(3)
    • LUT bond invalidity or non-furnishing orders under Rule 96A
    • Export of services vs intermediary reclassification under Section 2(13) IGST Act

    Under Section 112(1), the appeal must be filed within 3 months. For orders before 1 April 2026, exporters may file until 30 June 2026.

    6 GSTAT Services for Export Refund Disputes

    ServiceWhat We Do
    IGST Refund Rejection AssessmentAnalyse the refund rejection order, identify grounds of appeal, and calculate pre-deposit under Section 112(8) to protect export working capital
    Grounds of Appeal for Export DisputesStructure legal arguments on IGST computation errors, shipping bill mismatches, LUT validity, and intermediary classification
    Form GST APL-05 E-FilingComplete electronic filing on efiling.gstat.gov.in with refund workpapers and supporting documents
    Stay of Recovery Under Section 112(9)Secure automatic stay against recovery of any refund adjustment or demand raised consequent to refund rejection
    Hearing RepresentationAdvocate representation before all 31 State Benches and the Principal Bench at New Delhi
    High Court Writ Under Article 226Alternative remedy where GSTAT appeal window has expired - particularly relevant for time-sensitive export disputes
    Our Process

    7 Steps to File a GSTAT Appeal for Export Refund Rejection

    Our end-to-end process for exporter GSTAT appeals under Section 112

    Step 1

    Review Impugned Order

    Obtain the first appellate order relating to IGST refund rejection, ITC refund denial, or inverted duty structure refund order.

    Expert guidanceCompliance ensured
    Order Reviewed01
    Step 2

    Calculate Pre-Deposit

    Compute 10% of disputed tax under Section 112(8), verify Rs 20 crore cap, account for Section 107(6) amount already paid.

    Expert guidanceCompliance ensured
    Pre-Deposit Computed02
    Step 3

    Pay Pre-Deposit

    Pay via GST portal challan or Bharatkosh and obtain payment proof.

    Expert guidanceCompliance ensured
    ₹
    Payment Made03
    Step 4

    Prepare Grounds of Appeal

    Draft grounds focusing on Rule 89/96 computation errors, shipping bill mismatch evidence, LUT validity, FIRC/BRC proof.

    Expert guidanceCompliance ensured
    Grounds Drafted04
    Step 5

    Prepare Offline Utility JSON

    Download GSTAT offline utility, pre-fill appeal details, generate JSON file for upload.

    Expert guidanceCompliance ensured
    {}JSON
    JSON Prepared05
    Step 6

    File Form GST APL-05

    File on efiling.gstat.gov.in within 3-month limitation. Upload documents (PDF, max 50 MB), digitally sign.

    Expert guidanceCompliance ensured
    Appeal Filed06
    Step 7

    Receive Filing Number

    Filing number via SMS and email. Serve notice on respondent. Apply for stay under Section 112(9).

    Expert guidanceCompliance ensured
    Hearing Ready07

    Export GSTAT Appeal Document Checklist

    • Certified copy of impugned order from Commissioner (Appeals) rejecting refund
    • Original refund rejection order (Form GST RFD-06) from adjudicating authority
    • Form GST APL-01 and Form GST APL-03 from first appeal stage
    • Challan of pre-deposit payment under Section 112(8)
    • Grounds of appeal with specific refund rejection dispute details
    • Power of attorney or vakalatnama
    • Original refund application (Form GST RFD-01) with all annexures
    • Shipping bills, bills of lading, and Export General Manifest (EGM) data
    • GSTR-1 and GSTR-3B returns for relevant refund periods
    • Foreign Inward Remittance Certificates (FIRCs) or Bank Realisation Certificates (BRCs)
    • Letter of Undertaking (LUT) filed under Rule 96A for relevant periods
    • Inverted duty structure computation workpapers (if applicable)
    • Supporting CBIC circulars and HC judgments

    Download checklist - email sales@patronaccounting.com or call +91 945 945 6700.

    4 Common Challenges in Exporter GSTAT Appeals

    IGST Refund Rejection Due to Shipping Bill Mismatch

    The most common ground for refund rejection under Rule 96 is a mismatch between IGST in GSTR-1 and the shipping bill at ICEGATE. In our experience, these mismatches often arise from timing differences between return filing and customs clearance - not substantive tax errors.

    ITC Refund Denial Under Rule 89 for LUT Exports

    Exporters under LUT face rejection of accumulated ITC claims due to computation disputes, incorrect turnover figures, or denial of ITC on input services. Subham Jhunjhunwala notes that authorities commonly disallow ITC on freight, insurance, and commission without verifying direct attribution to zero-rated exports.

    Export of Services vs Intermediary Classification

    Reclassification as intermediary under Section 2(13) IGST Act denies zero-rated treatment. This is particularly acute for IT services, BPO, and staffing companies where place of supply shifts to the supplier's location.

    Inverted Duty Structure Refund Denial

    Exporters with higher input rates face denials where the department applies the amended Rule 89(5) formula to exclude input service ITC from refund computation.

    Illustrative Scenario: An export trading company with turnover of Rs 200 crore received a refund rejection of Rs 85 lakh on IGST paid under Rule 96, citing GSTR-1 Table 6A vs ICEGATE shipping bill mismatch. Commissioner (Appeals) upheld the rejection. Patron Accounting's GSTAT team structured grounds around reconciled export data showing the mismatch arose from a timing difference in EGM filing - resulting in admission with automatic stay under Section 112(9), protecting cash flow.

    Pre-Deposit and Engagement Terms for Export Disputes

    ComponentAmount (Rs)Basis
    Refund rejection (treated as demand)85,00,000IGST refund rejected by first appellate authority
    Of which: disputed tax (IGST)75,00,000Tax component of refund rejection
    Pre-deposit S.107(6) - already paid7,50,00010% of disputed tax
    Pre-deposit S.112(8) - payable now7,50,00010% additional
    Total deposited both stages15,00,00020% of disputed tax
    Balance - stayed under S.112(9)70,00,000Automatic stay

    Illustrative figures. For export refund disputes, the 'demand' is the rejected refund amount. Finance Act 2024 caps S.112(8) pre-deposit at Rs 20 crore CGST.

    FeeAmount
    Patron Accounting Professional FeesStarting from INR 24,999 (Exl GST and Govt. Charges)

    All fees listed are indicative only and do not constitute a binding offer. Final amounts may vary depending on volume and complexity of work.

    Calculate Your Pre-Deposit - Speak to Our GSTAT Team

    Why Choose Patron Accounting for Exporter GSTAT Appeals

    Export & GST Compliance Support

    Subham Jhunjhunwala, working with the firm's CA and CS team, provides unique depth for IGST refund and LUT disputes.

    Firm-Backed Support

    Backed by Patron Accounting's ICAI and ICSI registered CA and CS team.

    10,000+ Businesses Served

    4.9 Google rating, 15+ years. Pan-India GSTAT representation across Principal and State Benches.

    Pan-India Exporter Coverage

    Offices in Pune, Mumbai, Delhi, Gurugram. Serving exporters in Mumbai (trading houses), Chennai (manufacturing), Delhi (DGFT), Bangalore (IT/services).

    Trusted by Exporters Across India

    10,000+
    Businesses Served
    4.9
    Google Rating
    15+
    Years Experience
    "Patron Accounting's GSTAT team understood our refund exposure immediately. Subham Jhunjhunwala's approach to structuring the grounds of appeal was methodical and thorough." - CFO, Export Trading Company

    With offices in Pune, Mumbai, Delhi, and Gurugram, Patron Accounting provides GSTAT representation for exporters across all benches - including Mumbai (trading houses), Chennai (manufacturing exporters), New Delhi (DGFT interface), and Bangalore (IT/services exports).

    GSTAT Appeal vs High Court Writ for Export Refund Disputes

    FeatureGSTAT Appeal (S.112)HC Writ (Art.226)SC SLP
    When to UseAdverse order on refund rejection within 3 monthsJurisdictional error, natural justice violation, GSTAT time-barredAfter HC final order
    Pre-Deposit10% under S.112(8)No pre-depositNo pre-deposit
    TimelineVariable - bench dependent6-18 months12-36 months
    Key PointPrimary remedy - exhaust before writNot a substitute for GSTATLast resort

    A GSTAT appeal under Section 112 is the appropriate remedy for export refund rejections where the first appellate authority has passed an order on merits - unlike a High Court writ under Article 226, which lies only for jurisdictional errors or where the GSTAT remedy is time-barred beyond 4 months.

    What is the pre-deposit for a GSTAT appeal on export refund rejection?

    The pre-deposit under Section 112(8) is 10% of the disputed tax, capped at Rs 20 crore CGST. For export refund rejections, the disputed amount is the refund rejected by the first appellate authority. Payment triggers automatic stay under Section 112(9).

    What is the time limit to file a GSTAT appeal for export refund?

    3 months from date of communication under Section 112(1). Condonation up to 1 additional month under Section 112(2). For orders before 1 April 2026, deadline extends to 30 June 2026.

    What happens if I miss the deadline?

    Beyond 4 months the tribunal remedy is permanently lost. The only recourse is a writ petition under Article 226 - costlier, slower, and limited to jurisdictional errors.

    Can I get stay of recovery after filing?

    Yes - Section 112(9) provides automatic stay once the appeal is admitted with confirmed pre-deposit. This protects export working capital during proceedings.

    What is the difference between Rule 96 and Rule 89 export refunds?

    Rule 96 provides IGST refund on exports where the shipping bill acts as the application. Rule 89 provides ITC refund when exporting under LUT without IGST. An exporter cannot claim both for the same export.

    Can the deadline be extended for exporters?

    Yes - under Section 112(2), condonation up to 1 additional month. Beyond 4 months total, only recourse is HC writ under Article 226.

    What is an intermediary classification dispute?

    When the authority reclassifies export of services as intermediary under Section 2(13) IGST Act, place of supply shifts to India, denying zero-rated treatment. Common for IT, BPO, and staffing exporters.

    Is the 2-year refund limitation mandatory?

    The Karnataka HC in Merck Life Science (November 2025) held the limitation under Section 54 is directory, not mandatory. However, filing within the prescribed period avoids litigation risk.

    Quick Answers

    GSTAT pre-deposit percentage?
    10% of disputed tax under Section 112(8), capped at Rs 20 crore CGST.
    GSTAT appeal deadline?
    3 months from order under Section 112(1). Max 4 months with condonation.
    Refund application form?
    Form GST RFD-01. For IGST exports, shipping bill acts as application under Rule 96.
    Is stay of recovery automatic?
    Yes - Section 112(9) auto stay on filing with pre-deposit.
    Which form for GSTAT appeal?
    Form GST APL-05 on efiling.gstat.gov.in.
    LUT validity period?
    Valid for one financial year under Rule 96A. Fresh LUT needed each year.

    3-Month GSTAT Deadline for Export Refund Disputes - Act Now

    GSTAT appeals must be filed within 3 months of order communication under Section 112(1). Condonation up to 1 additional month. Beyond 4 months, the tribunal remedy is permanently lost for your export refund dispute.

    Contact us: +91 945 945 6700 | WhatsApp Us

    The 3-Month GSTAT Deadline Is Running - Contact Us for Export Refund Disputes

    GSTAT appeal for exporter refund rejection under Section 112 CGST Act 2017 provides the dedicated judicial forum that exporters need - a specialist tribunal to review and reverse adverse orders on IGST refund rejections, ITC refund denials, LUT bond disputes, and inverted duty structure claims that directly impact export competitiveness and cash flow.

    Patron Accounting's GSTAT practice is supported by Subham Jhunjhunwala, CA Finalist and Accounting & Tax Professional, working alongside the firm's CA and CS team on every GSTAT engagement. The 3-month limitation period and 10% pre-deposit make timely expert action essential.

    Book a Free Consultation - No Obligation.

    Content Created: 16 March 2026  |  Last Updated: 16 March 2026  |  Next Review: 16 June 2026  |  Reviewed By: CA & CS Team, Patron Accounting LLP

    This page is reviewed every 3 months or when triggered by: Changes to Section 54 refund provisions, Rule 89/96 amendments, CBIC circulars on export refund, Finance Act amendments to Section 112, GSTAT portal changes, significant HC/SC judgments on export refund or LUT disputes, or changes to intermediary classification rules.