Talk to an expert

Tell us what you need and we will call you back the same day.

🇮🇳 +91
    Trusted by 10,000+ Businesses

    Accounting for Consultants and Service Businesses

    Reviewed by CA and CS Team, Patron Accounting LLP ICAI & ICSI Registered| 15+ Years Experience| Last Updated: July 2026 Verify Credentials →

    Revenue tied to the fee basis: How each engagement earns comes from the signed contract, and that basis drives the accounting, not the invoice date.

    Unbilled work valued monthly: We value open engagements against the billing plan each month end, so delivered but uninvoiced effort shows as an asset.

    Realisation per engagement: Each month closes with fee earned, delivery cost, write-offs and recovery against the contracted rate, engagement by engagement.

    Client advances kept as liabilities: You hold retainers and advances as liabilities, released only against the invoice they belong to.

    15+ YearsIndustry Experience
    CA & CSCertified Experts
    4.9
    Based on real Google reviews

    Get Free Consultation

    Talk to a CA/CS expert today

    🇮🇳 +91

      Our team will get back to you shortly. No spam.

      Real Stories from Real People

      Verified Google reviews from founders and businesses Patron works with across India.

      Sunny Ashpal
      Sunny Ashpal
      Director - Demandify Media
      Google
      Anjanay Srivastava
      Anjanay Srivastava
      Founder - Hunarsource Consulting
      Google
      Mayur Shewale
      Mayur Shewale
      Founder - Bijasani Traders
      Google
      Ascendancy International
      Ascendancy International
      Owner
      Google

      I've had an outstanding experience working with my CA - Patron Accounting. Their professionalism, attention to detail, and timely communication made the entire process seamless and stress-free.

      I'm glad that I was able to connect with Patron. They took the minimum time to do the calculations based on the details provided by me and were really helpful throughout the process.

      Really a fantastic experience with Patron Accounting especially Shubham, he was extremely great. Knowledgeable person who deserves the 5 star for smooth handling of all documentation.

      Patron Accounting gives the best service related to all account handling of our firm. I am blessed and extremely happy that Patron Accounting assigned us a dedicated point of contact.

      I have called Patron to file ITR for my 5 family members. I worked with Shubham Junjunwala and Amin Jain. It was a smooth process. They understand basics very well and respond promptly.

      From the very beginning, their approach has been highly professional, prompt, and solution-oriented. Every interaction reflected their deep knowledge and commitment to helping clients.

      Very proficient and professional staff. Do fantastic job and instant response. Strongly recommended engaging them for all accounting needs specially for startups and growing businesses.

      I contacted them to file the ITR. Shubham was the POC for me and he was really very professional and giving prompt responses. Highly recommend them for tax and compliance work.

      Join 3,000+ Founders and Businesses on Patron

      Rated 4.9 on Google - trusted for startup accounting since 2019.

      Talk to an Expert
      10,000+Businesses ServedGST compliance and litigation support across India.
      15+Years ExperienceDeep expertise in IP registration, GST & business compliance.
      50,000+Documents FiledReturns, appeals, and filings handled accurately.
      4.9★Client RatingTrusted by entrepreneurs, startups, and growing businesses.
      ISO CertifiedProfessional standards and documented processes.
      SSL SecureYour financial and business data is fully protected.

      What Service Sector Accounting Covers — Scope, Deliverables and Who It Suits

      📌 TL;DR - Service Sector Accounting Services at a Glance

      Accounting for consultants makes unbilled work in progress visible every month instead of at year end. Patron reports engagement-wise realisation and WIP ageing, applies place-of-supply rules to inter-state assignments and reconciles Section 194J deductions against Form 26AS. Retainer and milestone billing are tracked to the contract that created them. Best suited to consultancies, agencies and firms billing time rather than goods.

      The books sit in whichever ledger your practice already runs, with a timesheet or billing tool feeding into it. Patron maps every engagement to one code that is carried across both systems, so hours booked, invoices raised and amounts still open reconcile back to a single figure. Journals for accrued income and provisions are posted at close, and accounting for a consultancy ends in schedules an auditor can trace, as project billing for media agencies illustrates.

      Where staff book time in arrears rather than daily, effort rises, as it does when live engagements multiply, when retainers sit beside milestone contracts and when registrations span several states at once. Service industry accounting includes each month's close, the engagement schedule, the ledger review and returns filed through the GST portal. Statutory audit, transfer pricing and litigation support are commissioned independently.
      What Is Service Sector Accounting?

      Accounting for consultants is the engagement that turns time and contracts into a defensible set of books, and its single job is to keep the value of unbilled work visible every month. A firm that sells hours, not goods, has revenue sitting in timesheets long before an invoice exists, and that is what this service captures.

      Each engagement is mapped to one code, so hours worked, amounts invoiced and balances still open all reconcile to a single figure. It reports profitability by engagement, applies the right place-of-supply treatment to assignments that cross state lines, and matches tax deducted by clients against the annual tax statement. Accounting for consultants tracks retainers and milestone fees back to the contract that created them. Service industry accounting of this kind ends in schedules an auditor can trace. In short, it is bookkeeping built for a business that bills time rather than stock. A statutory audit, along with transfer pricing and litigation support, is arranged separately from this engagement.

      Key Terms for Service Sector Accounting:

      What Is Service Sector Accounting. Accounting for consultants is the engagement that turns time and contracts into a

      Who Needs Service Sector Accounting in India?

      Accounting for consultants suits firms that sell time and expertise rather than stock. When revenue is earned before it is billed and staff book their hours after the fact, the businesses below need work in progress valued every month.

      • Management and strategy consultancies billing by the hour, carrying unbilled work between one invoice run and the next.
      • Creative and media agencies running monthly retainers alongside milestone project fees on a single client.
      • Architecture, design and engineering practices valuing work in progress per project before any bill goes out.
      • PR and marketing agencies recharging pass-through media and print costs their clients later approve.
      • Studios leaning on subcontractors and associates whose cost must sit against the engagement that used them.
      • Professional firms where Section 194J TDS deducted by clients must reconcile against Form 26AS.
      • Practices taking assignments across several states, applying place-of-supply rules to each engagement.
      • Consultancies holding client retainers as advances until the work behind them is delivered.

      Our Service Sector Accounting Services

      ServiceWhat We Do
      Engagement profitability reportingRevenue, delivery cost and realisation reported per engagement, so professional services accounting shows which clients and projects actually make money Monthly
      Unbilled revenue and WIP valuationOpen work valued and carried as unbilled revenue against the billing plan, using our method for unbilled revenue and WIP each month Monthly
      Client advance and retainer trackingRetainer and advance receipts held as liabilities and adjusted against invoices only as work is billed, keeping deferred fees accurate Monthly
      Milestone and retainer billing supportInvoices raised against milestones or retainers from your engagement terms, with credit notes and write-offs recorded cleanly for each client On event / as needed
      Associate and subcontractor cost accountingAssociate, freelancer and subcontractor invoices coded to the right engagement, giving project accounting services that show true delivery cost Monthly
      Monthly retainer accounting closeA monthly retainer covering bookkeeping, bank reconciliation and management accounts, our accounting for consultants keeps your firm's books review-ready Monthly
      Our Process

      How Service Sector Accounting Works — Our Process

      How Patron delivers service sector accounting, step by step from onboarding to a clean monthly close.

      Step 1

      Reading engagement terms into billing

      We work through each signed engagement letter, SOW and retainer agreement and record how that engagement earns: fixed fee, time and materials, milestone or monthly retainer. That fee basis, not the invoice date, drives how the engagement is accounted for.

      Illustration for Reading engagement terms into billing: We work through each signed engagement letter, SOW and retainer
      Step 2

      Matching timesheets to invoices

      The time-tracking export is reconciled by client, project and person against invoices actually raised. Hours recorded but not billed are carried as unbilled; hours abandoned are written off only against a named approval, so realisation is visible rather than hidden.

      Illustration for Matching timesheets to invoices: The time-tracking export is reconciled by client, project and person
      Step 3

      Valuing unbilled work in progress

      At each month end we value open engagements against the billing plan and recognise revenue as the promised service is delivered, not as bills go out. The unbilled schedule is rolled forward so the balance is explainable line by line.

      Illustration for Valuing unbilled work in progress: At each month end we value open engagements against the billing plan and
      Step 4

      Tracking unadjusted client advances

      Retainers and advances are held as liabilities and adjusted only against the invoice they relate to. Because GST on a service falls due on the earlier of invoice or receipt, we check that receipt vouchers and the advance ledger agree with what was reported.

      Illustration for Tracking unadjusted client advances: Retainers and advances are held as liabilities and adjusted only
      Step 5

      Separating pass-through client costs

      Reimbursables are tested against the pure agent conditions: third-party bill in the client's name, client authorisation on record and recovery at actual. Costs that fail the test are treated as your own expense and recovered as taxable value instead.

      Illustration for Separating pass-through client costs: Reimbursables are tested against the pure agent conditions:
      Step 6

      Costing associates and subcontractors

      Associate, freelancer and subcontractor invoices are tagged to the engagement they served, and deduction is applied at the rate their engagement terms call for. This keeps delivery cost against the right revenue instead of pooling it in overheads.

      Illustration for Costing associates and subcontractors: Associate, freelancer and subcontractor invoices are tagged to the
      Step 7

      Reporting engagement level profitability

      Each month closes with a view per engagement: fee earned, cost of delivery, write-offs and realisation against the contracted rate. Loss-making engagements and stale unbilled balances are listed for you to price or close.

      Illustration for Reporting engagement level profitability: Each month closes with a view per engagement: fee earned, cost of

      Documents Required for Service Sector Accounting

      With no goods to count, the trail for a services firm runs from the engagement letter through the timesheet to the invoice.

      • Signed engagement letters, SOWs and retainer agreements with fee basis and milestone terms
      • Timesheets / time-tracking export by client, project and person
      • Unbilled revenue / work-in-progress schedule and the billing plan for open engagements
      • Advance / retainer receipts register showing unadjusted client advances
      • Reimbursable / pass-through expense records with client approval and supporting third-party bills
      • Subcontractor and associate/freelancer invoices with the engagement terms
      • Sales invoices raised, with credit notes and write-offs
      • Bank statements for all accounts, and business credit card statements
      • Purchase and expense bills: rent, software subscriptions, travel, professional indemnity insurance
      Client Portal

      How You Work With Patron

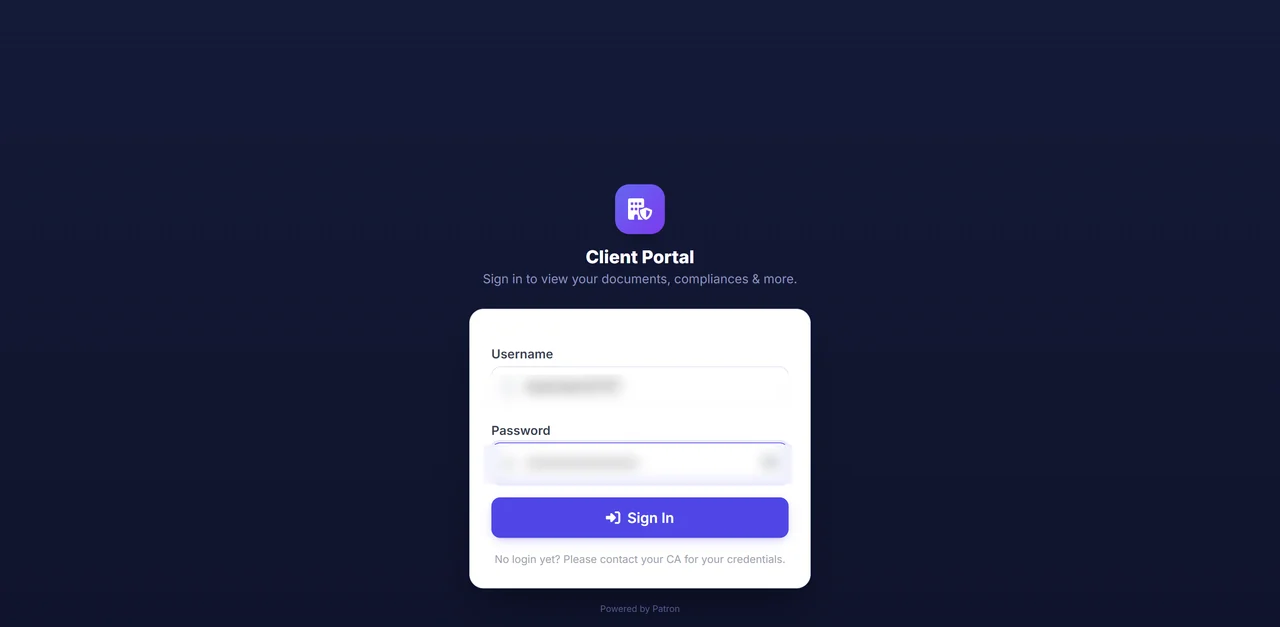
      Everything happens in one secure login. You can see your active services, the Patron team on your account, and anything still pending. Once you raise a request, it moves through the same clear steps every time, so you always know exactly where your work stands.

      Secure client portal login screen
      1

      Sign in securely

      Your books, documents and requests all sit behind one private, password protected login. The team handling your account is shown on screen, so nothing sensitive ever needs to travel over email or WhatsApp.

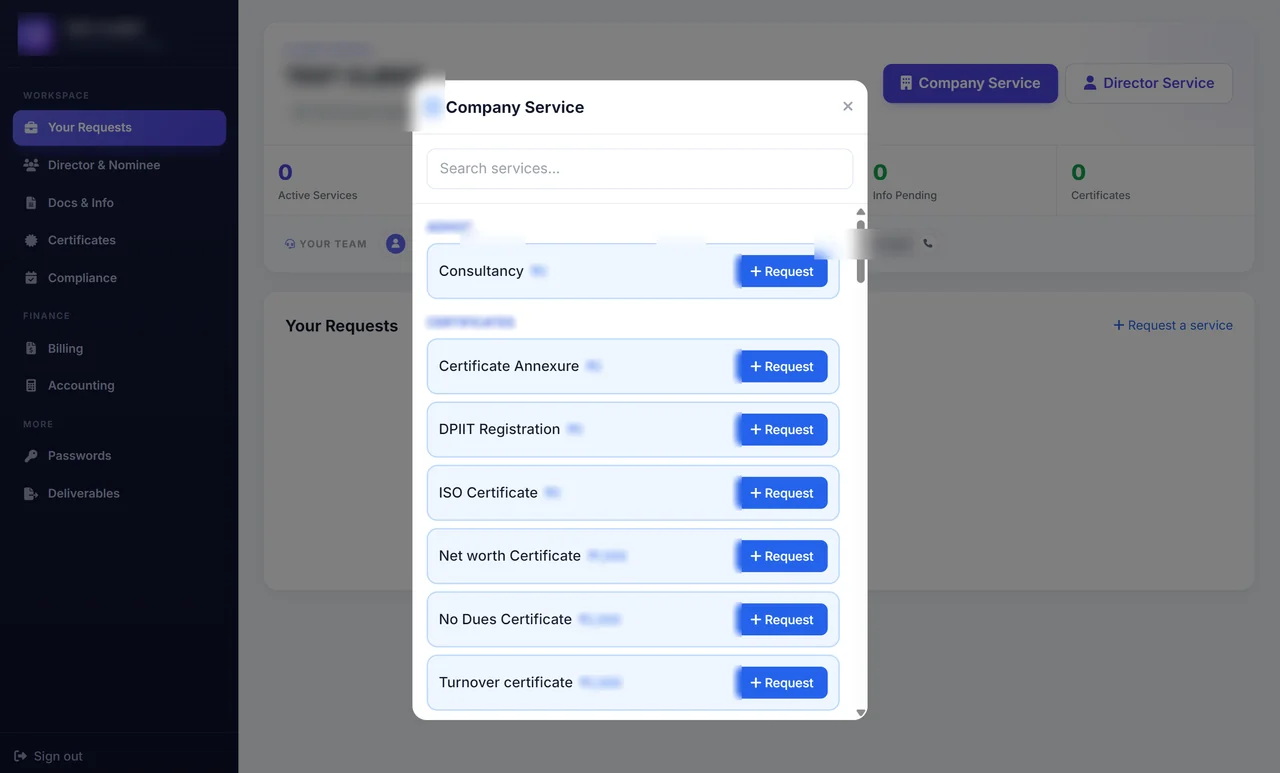
      Service catalogue inside the client portal
      2

      Raise your request

      Choose the service you need from the menu inside the portal, where the price is shown before you go ahead. Your request is logged the moment you send it, with no phone calls or reminder emails to wait on.

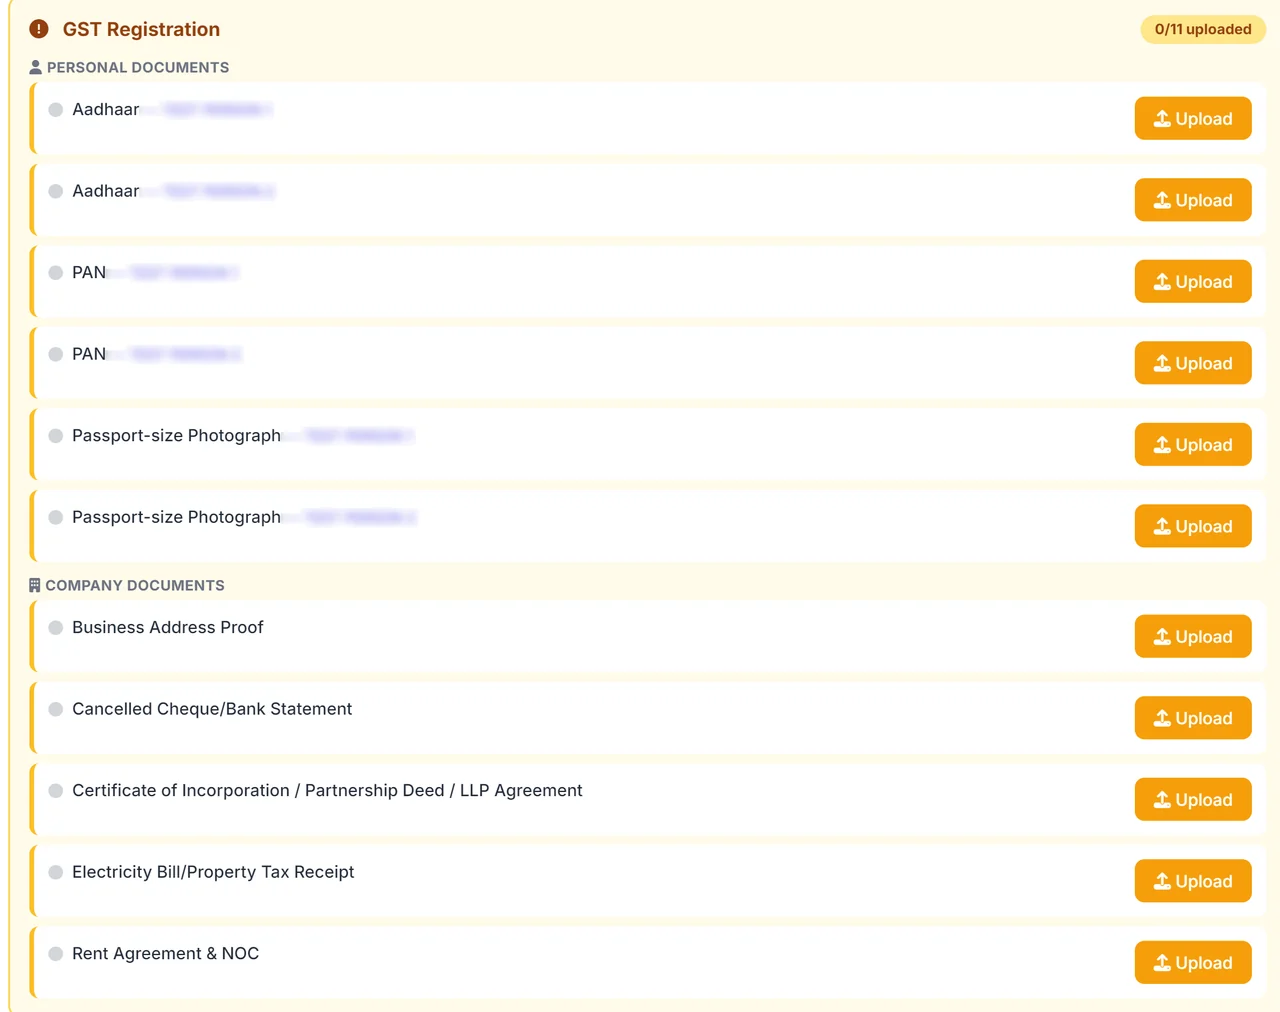
      GST registration document checklist in the client portal, with an upload button beside each item
      3

      Share what the service asks for

      For every service, the portal lists the exact documents it needs, each with its own upload button. The example shown here is the GST registration checklist. When a service needs nothing from you, it simply asks for nothing.

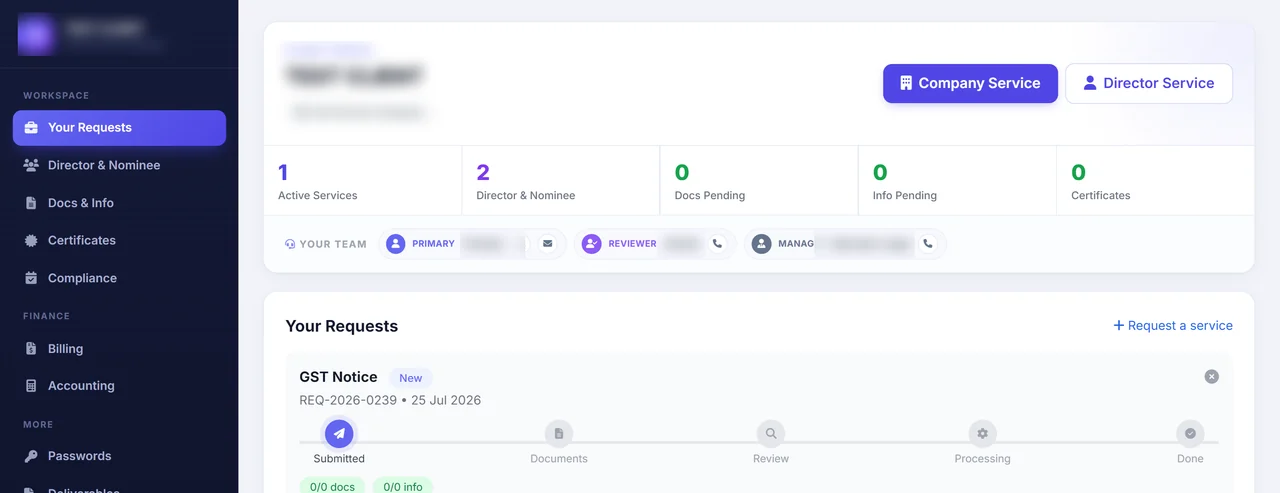
      Live request tracker inside the client portal
      4

      We review, prepare and file

      Once your documents are in, your team checks them, prepares the work and files it for you. A live tracker shows each stage as it happens, from review to processing to done, so you never have to ask where things stand.

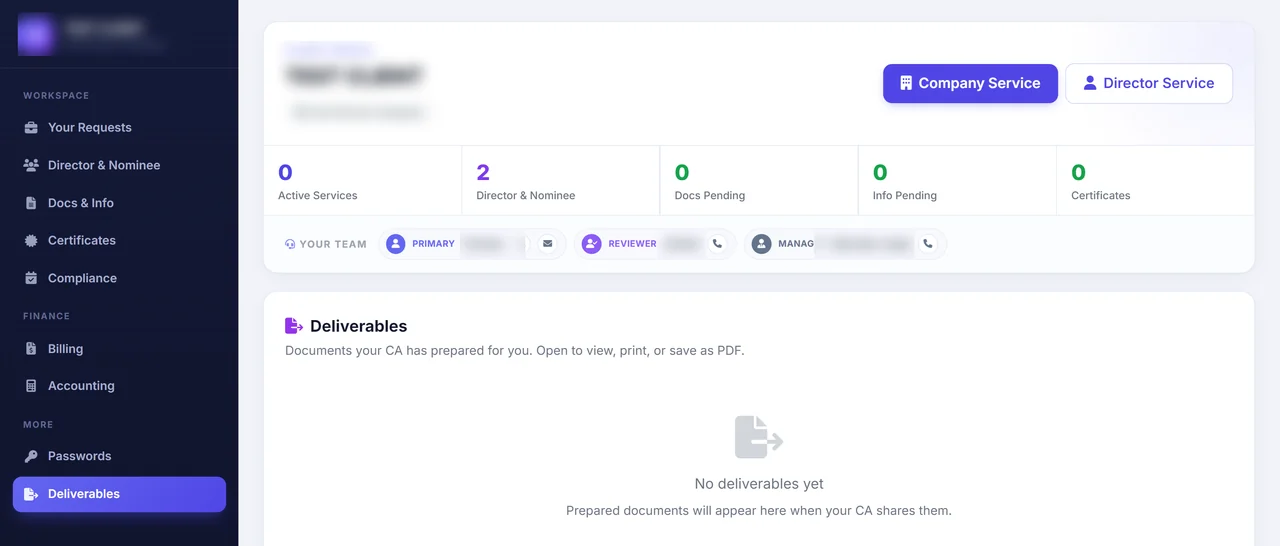
      Deliverables area of the client portal
      5

      Collect your finished work

      Every completed return, computation and certificate is placed in your Deliverables area. You can open, print or download any of them as a PDF whenever you need a copy.

      Common Service Sector Accounting Challenges and How We Solve Them

      ChallengeImpactHow Patron Accounting Solves It
      Fixed-fee engagements recognised when invoiced, not as deliveredRevenue lands in lumps at billing, so profit and advance-tax estimates swing with paperwork, not real progress.Our team recognises revenue by percentage completion against cost-to-complete estimates; read unbilled revenue for service firms.
      Non-billable hours and write-downs erode realisation unseenEffective rate per hour drops below cost without anyone noticing until the engagement has already lost money.Patron reports realisation against standard rates per engagement, surfacing write-offs and utilisation gaps monthly.
      Reimbursable costs billed with GST as though they were feesTax charged on pure pass-through costs inflates invoices and overstates both revenue and output GST.We segregate pure-agent reimbursements under GST valuation rules, keeping pass-through costs out of taxable turnover.
      Long debtor cycles carry no doubtful-debt provisionDebtors look fully collectable on the balance sheet while old, doubtful invoices quietly sit uncollected.Patron provides for doubtful debts by ageing bucket, so receivables reflect what will actually be collected.
      Fixed-price overruns hit before anyone re-forecasts the marginCosts quietly cross the budget mid-project, and the loss only surfaces when the final invoice is raised.Our team tracks cost-to-complete against contract value each month, flagging engagements slipping into loss early.

      Service Sector Accounting Fees

      Fee ComponentAmount
      Starter — one service entity with routine monthly billing and receivablesINR 2,499
      Excl. GST & Government Charges
      Growth — higher invoice volume, added GST states or a second entityOn quote
      Managed — multi-entity books with custom receivable and revenue reportingOn quote

      Our Starter plan suits a single consultancy at INR 2,499: monthly billing, receivable tracking and clean ledgers. What moves accounting for consultants up a tier is invoice volume and how many receivables need chasing, not headcount. Request a customised estimate on +91 94594 56700.

      Fees exclude GST and government charges. Final quote confirmed after a scoping review.

      All fees and charges listed are indicative only and do not constitute a binding offer. Final amounts may vary depending on the volume of work and the complexity involved.

      Professional accounting and compliance charges are scoped to your number of entities, funding stage and monthly transaction volume, and are separate from statutory and government charges. Contact us for a detailed, fixed quote.

      Get a free Service Sector Accounting consultation - Call +91 945 945 6700 or WhatsApp us. No-obligation assessment.

      Service Sector Accounting Compliance Calendar 2026

      ComplianceDue DateApplies To
      TDS / TCS deposit (Challan ITNS-281)7th of every month (30 April for March)Every business that deducts tax at source on salaries, rent, contractor or professional fees
      GSTR-1 (outward supplies)11th of every month for monthly filersGST-registered businesses filing monthly returns
      GSTR-3B (summary return and tax payment)20th of every month for monthly filersGST-registered businesses filing monthly; QRMP filers pay via PMT-06
      GST PMT-06 (QRMP monthly tax payment)25th of the month for the first two months of each quarterQRMP filers paying tax monthly while filing GSTR-3B quarterly
      TDS return for Jan-Mar quarter (Form 24Q / 26Q)31 May 2026Deductors filing quarterly TDS statements
      Income-tax return, non-audit cases31 July 2026Proprietors, firms and individuals not liable to tax audit
      Advance tax second instalment (45% cumulative)15 September 2026Companies, firms and individuals liable to advance tax
      Annual GST return GSTR-9 and reconciliation GSTR-9C31 December 2026GST-registered businesses above the annual-return and audit thresholds

      For a service firm the recurring dates are the 194J TDS on the 7th and the 20th GSTR-3B, with the non-audit ITR on 31 July. Unbilled revenue needs a cut-off before each close. Patron builds these into your consultancy accounting rhythm so revenue and TDS reconcile cleanly. Download the 2026 calendar or talk to a CA on +91 94594 56700.

      Key Benefits

      Why Professional Service Sector Accounting Matters

      Revenue tied to the fee basis

      How each engagement earns comes from the signed contract, and that basis drives the accounting, not the invoice date.

      • Basis read from engagement letters, SOWs and retainer agreements
      • Fixed fee, milestone, time and materials or retainer each treated on its terms
      • Without it, bill-date accounting lands income in the wrong month

      Unbilled work valued monthly

      We value open engagements against the billing plan each month end, so delivered but uninvoiced effort shows as an asset.

      • Unbilled revenue carried on a rolled-forward WIP schedule
      • Without it, a year's leakage surfaces only at the annual accounts

      Realisation per engagement

      Each month closes with fee earned, delivery cost, write-offs and recovery against the contracted rate, engagement by engagement.

      • Recovery measured against the rate each engagement was contracted at
      • Without it, a loss-making job is repriced only after it finishes

      Client advances kept as liabilities

      You hold retainers and advances as liabilities, released only against the invoice they belong to.

      • Receipt vouchers agreed to the advance and retainer register
      • Released against the specific invoice, keeping the tax position supported
      • Without it, advances booked as income inflate a good month

      Pass-through costs tested properly

      We test each reimbursable against the pure agent conditions, so genuine recharges stay out of your taxable value.

      • Pure agent conditions: client-name bill, written authorisation, recovery at actual
      • Costs that fail the test recovered as taxable value
      • Without it, travel and printing recharges become a liability at assessment

      Delivery cost against the right revenue

      We tag associate and subcontractor invoices to the engagement they served rather than pooling them in overheads.

      • Deduction applied on the terms of each subcontractor's contract
      • Without it, true engagement margin stays hidden in overheads

      Why Businesses Choose Patron Accounting for Service Sector Accounting (Project Billing)

      Five things a founder can check before handing over the books. Each is a claim with the proof behind it.

      Unbilled WIP visible every month, not discovered at year end

      Retainers and milestone fees leave work unbilled between invoice runs. Across 15+ years serving consultancies, we value unbilled revenue and WIP every month, so realisation is visible long before the year-end review.

      Place-of-supply on inter-state work and Section 194J deduction

      We set place-of-supply correctly on inter-state engagements and deduct Section 194J at source. With 25,000+ filings behind us, clients can claim 194J credit via 26AS without the year-end scramble.

      Project billing and time capture wired into the ledger

      We build inside the platform already running your books, whether Zoho Books, Xero, Tally Prime or Odoo. We wire your project billing and time capture into the ledger, so hours booked flow straight to revenue.

      Engagement-wise realisation and WIP ageing every month

      Each month you receive engagement-wise realisation and WIP ageing, showing which jobs are earning and which are stuck. The cadence is monthly, and our 4.9 star Google rating reflects firms that finally trust their numbers.

      Consultancies and agencies among 3,000+ businesses served

      Consultancies, agencies and professional practices sit among the 3,000+ businesses we have served since 2019. That reach, with 15+ years of experience and a 4.9 star Google rating, stands behind every engagement.

      Figures reflect Patron Accounting LLP engagements since 2019. Scope and turnaround are confirmed in your engagement letter.

      Milestone Billing vs Retainer Billing

      CriterionMilestone BillingRetainer Billing
      What it isFees invoiced when defined project milestones or deliverables are accepted.A fixed periodic fee for ongoing availability or a recurring scope.
      Revenue recognitionRecognised as performance obligations are met, often over time via POCM.Recognised evenly across the retainer period as the service is delivered.
      Unbilled vs advanceWork done ahead of a milestone sits as unbilled revenue or WIP.Fees billed ahead of delivery sit as a client advance liability.
      Cash flowLumpy inflows tied to sign-offs, with gaps between milestones.Predictable monthly inflow that smooths working-capital planning.
      Profitability trackingMargin read per project once delivery cost meets milestone revenue.Margin depends on hours consumed against the fixed fee each month.
      TDS and complianceClient deducts TDS per invoice; credit tracked against each milestone.Regular TDS on each periodic bill; simpler to reconcile in 26AS.
      VerdictMatch the model to the engagement; milestone billing suits defined project work, retainers suit continuing advisory. Both need unbilled revenue and advances tracked correctly, which is where accounting for consultants earns its keep. See unbilled revenue and WIP.

      Legal and Regulatory Framework for Service Sector Accounting

      For a firm that sells hours rather than goods, Section 128 still defines the books, but the provision that shapes them most in practice is the revenue standard, because the hardest question each month is how much of the work done has actually been earned. The framework around it decides when a service is invoiced, where it is taxed and how the fee is measured.

      The answer changes with the contract. A retainer, a milestone and a time-and-materials engagement are recognised differently, so Unbilled Revenue (WIP Hours) is carried where work is ahead of billing, and the Milestone vs Retainer Billing split drives both the ledger and the GST invoice. Accounting for consultants keeps these judgements consistent against the provisions below.

      • AS 9 / Ind AS 115Fee income is recognised as the service is performed, with unbilled revenue carried for work delivered but not yet invoiced.
      • Sections 12 and 13, IGST Act 2017The place-of-supply rules decide whether a service is intra-state or inter-state, fixing CGST/SGST versus IGST on each invoice.
      • Section 194J, Income-tax Act 1961Professional and technical fees attract TDS at 10% (2% for technical services), which the books track against Form 26AS.
      • Section 44ADA, Income-tax Act 1961Eligible professionals up to Rs 75 lakh receipts may declare 50% presumptive income instead of maintaining full books.
      • Section 128, Companies Act 2013An incorporated agency keeps its books on accrual and double entry at the registered office, retained for eight years.
      • Rule 3(1), Companies (Accounts) Rules 2014The audit trail stays enabled, so a revised time sheet or a reclassified retainer leaves a record - the basis of a defensible Project-Wise Profitability Margin. Filing runs from the hub page.

      Official sources: Ministry of Corporate Affairs · Income Tax Department · GST Portal · Startup India (DPIIT)

      What is the chart of accounts for service industry?

      A service business chart of accounts splits fee income by service line, then cost of delivery such as consultant salaries, subcontractor fees and project travel, and only then administrative overhead, so gross margin per service line is visible every month. It also needs control accounts for unbilled revenue, advances from clients, TDS receivable under Section 194J and GST input and output ledgers. We build this before the first entry.

      How do you account for unbilled revenue on ongoing projects?

      Unbilled revenue is recognised each month for work delivered but not yet invoiced and carried as a contract asset, then reversed when the invoice is raised. We reconcile timesheets or delivery milestones with the invoice register every month, so the profit and loss shows earned revenue rather than only collections and long projects do not distort a quarter.

      What expenses can a consultant claim?

      A consultant can claim any expense incurred wholly and exclusively for the profession under Section 37 of the Income Tax Act, including office rent, laptops and software, professional subscriptions, client travel, subcontractor fees, telephone and internet, and the business share of vehicle running cost. Personal spending is not allowable, capital purchases are claimed through depreciation, and cash payments above the Section 40A(3) limit are disallowed.

      Is GST payable on consulting services exported to overseas clients?

      Export of services is zero rated under GST, so no tax is charged on the invoice where you export under a Letter of Undertaking. The LUT has to be filed on the GST portal for each financial year, payment must be received in convertible foreign exchange, and the bank realisation advice or FIRC has to be kept for every invoice.

      How is TDS deducted by clients under Section 194J adjusted?

      TDS deducted by clients on professional fees at 10 percent is booked against each invoice and reconciled every quarter with Form 26AS and the annual information statement. Any deduction a client has not actually deposited is followed up before the return is filed, because credit is allowed only for amounts appearing against your PAN in the department's records.

      How much does monthly accounting cost for a consulting firm or agency?

      Monthly accounting for a consulting firm or agency typically costs Rs 8,000 to Rs 20,000 a month for up to 150 transactions, and Rs 25,000 to Rs 45,000 where payroll, project profitability reporting and multi state GST are involved. Fees move with invoice volume, headcount and the number of GST registrations rather than with your revenue.

      Can you report profitability for each client or project?

      Yes, client and project level profitability is reported monthly, usually within 10 working days of month end, once costs are tagged. Direct salaries, subcontractor cost and pass through expenses are mapped to each engagement using cost centres in Zoho Books or Tally, so you can see gross margin by client, by service line and by delivery team.

      How should reimbursable expenses billed to clients be recorded?

      Reimbursable expenses can be excluded from your taxable value only where you act as a pure agent and meet the conditions in the GST valuation rules, otherwise they form part of the value of your invoice. We keep the third party invoice in the client's name where the pure agent route is used, because the documentation is what an officer checks.

      How are retainer fees received in advance treated in the books?

      Retainer fees received in advance are shown as a liability and released to income as the work is performed each month. GST is generally payable on receipt of an advance for services, so the tax is discharged in the month of receipt even though revenue is recognised later. Unused retainer balances are tracked client wise for refund or adjustment.

      What happens when invoices, timesheets and books have not been reconciled for a year?

      A twelve month clean up usually takes 3 to 6 weeks and starts by rebuilding the invoice register from the GST portal, matching it to bank credits and identifying invoices raised but never recorded. We then reconcile TDS credits, write up unbilled work and restate the profit and loss month by month so the annual return goes out on correct numbers.

      Quick Answers

      The books sit in whichever ledger your practice already runs, with a timesheet or billing tool feeding into it. Patron maps every engagement to one code that is carried across both systems, so hours booked, invoices raised and amounts still open reconcile back to a single figure. Journals for accrued income and.

      Service Sector Accounting Deadlines You Cannot Afford to Miss

      TDS / TCS deposit (Challan ITNS-281) is due 7th of every month (30 April for March). GSTR-1 (outward supplies) is due 11th of every month for monthly filers. GSTR-3B (summary return and tax payment) is due 20th of every month for monthly filers. Patron tracks each against your books so nothing is reconstructed after the fact. Call +91 94594 56700 to set up a filing-reminder schedule.

      Start Your Service Sector Accounting with Patron Accounting

      What changes first under accounting for consultants is the middle of the month. Unbilled hours are already valued instead of nothing happening until an invoice run. An engagement running past its budget is flagged while it is still running, and the partner review has numbers in front of it rather than impressions.

      Month end under accounting for agencies starts with the engagement schedule rather than the bank. Hours booked convert into a billing decision while the client still remembers the work, and the close lands on figures your partners reviewed first. Recovery on a job is known while that job can still be steered.

      We ask how your people record time: daily, weekly or from memory at the end of a job. Then comes the shape of your contracts, and which of them bill on milestones your finance team never sees, a pattern shared with software firms we already support.

      Book a Free Consultation - No Obligation.

      Service Sector Accounting Near You

      Local teams for service sector accounting in these cities.

      Reviewed by the CA & CS Team, Patron Accounting LLP
      ICAI & ICSI registered  ·  15+ years in Indian accounting & compliance  ·  Last reviewed 23 July 2026  ·  Next review 23 October 2026
      Join 5,000+ business owners. Get compliance due date alerts on WhatsApp. Join Free →