Talk to an Expert
Talk to an Expert ✆ +91 945 945 6700
Trusted by 10,000+ Businesses

Accounting for Trading Businesses in India

Reviewed by CA and CS Team, Patron Accounting LLP ICAI & ICSI Registered| 15+ Years Experience| Last Updated: July 2026 Verify Credentials →

Stock that matches the godown: Your book stock is agreed location by location: main premises, each declared godown and goods lying with consignees.

Margin read by product group: You get gross margin split by product group and explained: which lines fell, what discounts took, where slow movers tied cash.

Credit kept, not reversed: You get a running list of purchase bills unpaid past the point where input tax credit must be reversed. It reaches you in time to act.

Import cost per item: Every consignment enters the books with duty, freight, insurance and CHA charges in its landed cost per item. Import IGST comes off the Bill of Entry.

15+ YearsIndustry Experience
CA & CSCertified Experts
4.9
Based on real Google reviews

Get Free Consultation

Talk to a CA/CS expert today

🇮🇳 +91

    Our team will get back to you shortly. No spam.

    Real Stories from Real People

    Verified Google reviews from founders and businesses Patron works with across India.

    Sunny Ashpal
    Sunny Ashpal
    Director - Demandify Media
    Google
    Anjanay Srivastava
    Anjanay Srivastava
    Founder - Hunarsource Consulting
    Google
    Mayur Shewale
    Mayur Shewale
    Founder - Bijasani Traders
    Google
    Ascendancy International
    Ascendancy International
    Owner
    Google

    I've had an outstanding experience working with my CA - Patron Accounting. Their professionalism, attention to detail, and timely communication made the entire process seamless and stress-free.

    I'm glad that I was able to connect with Patron. They took the minimum time to do the calculations based on the details provided by me and were really helpful throughout the process.

    Really a fantastic experience with Patron Accounting especially Shubham, he was extremely great. Knowledgeable person who deserves the 5 star for smooth handling of all documentation.

    Patron Accounting gives the best service related to all account handling of our firm. I am blessed and extremely happy that Patron Accounting assigned us a dedicated point of contact.

    I have called Patron to file ITR for my 5 family members. I worked with Shubham Junjunwala and Amin Jain. It was a smooth process. They understand basics very well and respond promptly.

    From the very beginning, their approach has been highly professional, prompt, and solution-oriented. Every interaction reflected their deep knowledge and commitment to helping clients.

    Very proficient and professional staff. Do fantastic job and instant response. Strongly recommended engaging them for all accounting needs specially for startups and growing businesses.

    I contacted them to file the ITR. Shubham was the POC for me and he was really very professional and giving prompt responses. Highly recommend them for tax and compliance work.

    Join 3,000+ Founders and Businesses on Patron

    Rated 4.9 on Google - trusted for startup accounting since 2019.

    Talk to an Expert
    10,000+Businesses ServedGST compliance and litigation support across India.
    15+Years ExperienceDeep expertise in IP registration, GST & business compliance.
    50,000+Documents FiledReturns, appeals, and filings handled accurately.
    4.9★Client RatingTrusted by entrepreneurs, startups, and growing businesses.
    ISO CertifiedProfessional standards and documented processes.
    SSL SecureYour financial and business data is fully protected.

    What Trading Business Accounting Covers — Scope, Deliverables and Who It Suits

    📌 TL;DR - Trading Accounting Services at a Glance

    Accounting for trading business is stock-led: every lot valued on a consistent cost or net realisable value basis at each close. Purchase and sales registers tie to GSTR-2B and GSTR-1 before filing, with e-way bill data reconciled back to the sales register. Patron reports godown-wise stock and splits margin by product line. Common among distributors, wholesalers and commodity traders across India.

    Input credit is lost when the purchase register and the supplier's own filing part ways, and the shortfall shows only on close inspection. Patron lists the differences supplier by supplier, separates goods still in transit from bills never uploaded, ties credit notes back to the original invoice and chases what is missing before the return goes in. Accounting for a trading business leaves you the residual gap, as recovering credit lost to supplier mismatches explains.

    The recurring cycle is what sits inside scope: purchase and sales coding, stock valuation at each close, the landed-cost working on imports, and every schedule that sits behind them. A wholesale business takes more effort where several godowns, branch registrations or import consignments are involved, and the filing rhythm follows the published return calendar. Physical stock counts are arranged separately.
    What Is Trading Business Accounting?

    Every consignment of goods bought and sold is the unit this service is built around, from the price paid to the margin finally realised. Accounting for trading business is the discipline that values that stock accurately and keeps the purchase and sales records tying back to it.

    Closing stock is valued on a consistent basis at each period, so the profit reported is the profit actually earned rather than a figure agreed after the fact. It reconciles the purchase and sales registers against the returns filed at the portal, builds the landed cost of imported goods, and reports stock and margin by godown and by product line. Accounting for trading business treats the stock ledger, not the bank statement, as the spine of the accounts. Wholesale accounting services of this kind scale with the number of godowns and import consignments involved. Physical stock counts and any departmental representation are arranged separately from this engagement.

    Key Terms for Trading Accounting:

    What Is Trading Business Accounting. Every consignment of goods bought and sold is the unit this service is built

    Who Needs Trading Business Accounting in India?

    Accounting for trading business suits firms whose profit is settled at the godown, not on the invoice. When stock outruns the paperwork, the businesses below each carry a distinct reason their books turn on inventory and supplier credit.

    • Distributors holding stock across several godowns that must reconcile to one another.
    • Wholesalers moving goods on delivery challans to exhibitions or approval, where movements stay open.
    • Importers building landed cost from Bill of Entry, freight and customs duty per consignment.
    • Multi-state traders billing inter-state branch transfers between the same PAN and different GSTINs.
    • Commodity traders running trade and quantity schemes that shift the rate after a sale.
    • Buyers crossing the 194Q threshold who must deduct TDS on their goods purchases.
    • Traders whose purchase register keeps parting ways with GSTR-2B at each filing.
    • Firms valuing closing stock on FIFO or weighted average that a banker relies on.

    The software and platforms we work with

    Amazon
    Flipkart

    Our Trading Business Accounting Services

    ServiceWhat We Do
    Warehouse and godown stock reconciliationStock reconciled per godown and additional place of business against GRNs, transfers and physical counts, so book stock matches what is on the floor Monthly
    GST input credit reconciliationPurchase register matched to GSTR-2B so eligible input tax credit is claimed and not reversed, following our approach to GSTR-2B reconciliation for traders Monthly
    Import landed cost accountingBill of entry duty, IGST, freight and clearing charges built into landed cost per item, giving accurate margins for your import export business On event / as needed
    Branch transfer and challan trackingInter-state branch transfers between GSTINs valued correctly and open delivery challans closed off, keeping stock and turnover reconciled across locations Monthly
    Scheme, rate difference and credit notesTrade schemes, quantity discounts and rate differences posted through credit and debit notes, matched supplier by supplier for wholesale accounting services Monthly
    Monthly trading accounts and margin reviewComplete accounting for trading business each month with product-group margins, closing stock valuation and management accounts for owner review Monthly
    Our Process

    How Trading Business Accounting Works — Our Process

    How Patron delivers trading accounting, step by step from onboarding to a clean monthly close.

    Step 1

    Godown-wise stock reconciliation

    Stock is reconciled location by location against the books: main premises, each declared godown, and goods held with consignees. Where records are required to be kept at a place of business, we check that the location is actually on your registration and that its records exist.

    Illustration for Godown-wise stock reconciliation: Stock is reconciled location by location against the books: main
    Step 2

    Valuing inter-state branch transfers

    Stock moved between your own registrations is a supply between distinct persons and needs a tax invoice, not a challan. We check the value adopted against the valuation rule and confirm the receiving branch has taken the credit.

    Illustration for Valuing inter-state branch transfers: Stock moved between your own registrations is a supply between
    Step 3

    Closing out delivery challan movements

    Goods sent to exhibitions, to godowns or on approval move on a delivery challan. We track each challan to its close, whether a sale invoice is raised or the goods come back, so nothing sits open past the period allowed for approval supplies.

    Illustration for Closing out delivery challan movements: Goods sent to exhibitions, to godowns or on approval move on a
    Step 4

    Building import landed cost

    For each import consignment we assemble the Bill of Entry value, customs duty, ocean or air freight, insurance and CHA charges into a landed cost per item. Import IGST is claimed off the Bill of Entry data; basic duty stays in cost.

    Illustration for Building import landed cost: For each import consignment we assemble the Bill of Entry value, customs duty,
    Step 5

    Handling schemes and rate differences

    Sales returns, rate differences and quantity or trade schemes are put through the credit and debit note register. Where a discount is meant to reduce taxable value we check it was agreed before supply and linked to the original invoices.

    Illustration for Handling schemes and rate differences: Sales returns, rate differences and quantity or trade schemes are
    Step 6

    Supplier-wise credit matching

    The inward supply register is matched supplier by supplier to the auto-populated statement, and unmatched invoices are chased with the supplier. We also flag purchase bills unpaid beyond the period after which credit has to be reversed.

    Illustration for Supplier-wise credit matching: The inward supply register is matched supplier by supplier to the
    Step 7

    Closing stock and margin review

    Closing stock is valued on a consistent basis, shortages, damages and slow movers are identified from the count, and gross margin is read by product group. The result explains why margin moved rather than only that it moved.

    Illustration for Closing stock and margin review: Closing stock is valued on a consistent basis, shortages, damages and slow

    Documents Required for Trading Business Accounting

    Stock held at a godown declared as an additional place of business drives most of what follows, alongside the usual purchase and sales records.

    • Godown-wise / additional-place-of-business stock records
    • Delivery challans for stock moved to godowns, exhibitions or on approval
    • Inter-state branch transfer invoices between distinct persons (same PAN, different GSTIN)
    • Bill of Entry and customs duty / IGST payment challans for import consignments
    • CHA / freight forwarder bills, ocean or air freight invoices and insurance for each consignment
    • Credit and debit notes register (sales returns, rate difference, trade and quantity schemes)
    • Sales invoice file and sales register (serially numbered tax invoices)
    • Purchase invoices and inward supply register with supplier GSTINs
    • Bank statements (all current, OD/CC and payment-gateway accounts) and the cash book
    Client Portal

    How You Work With Patron

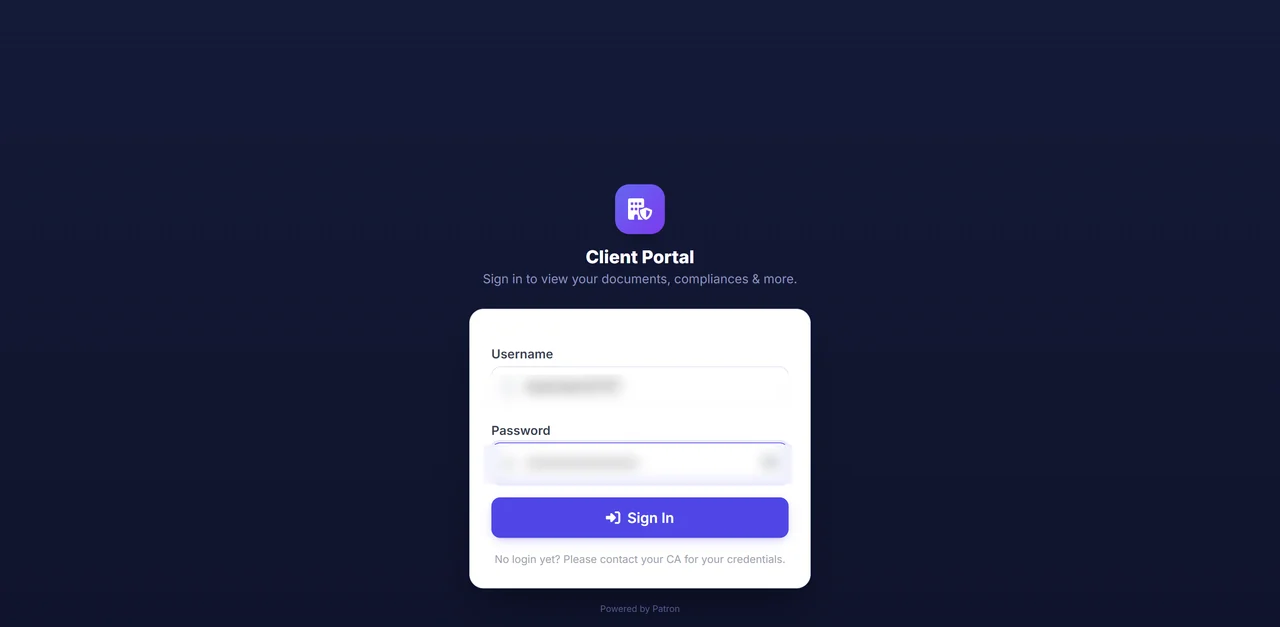
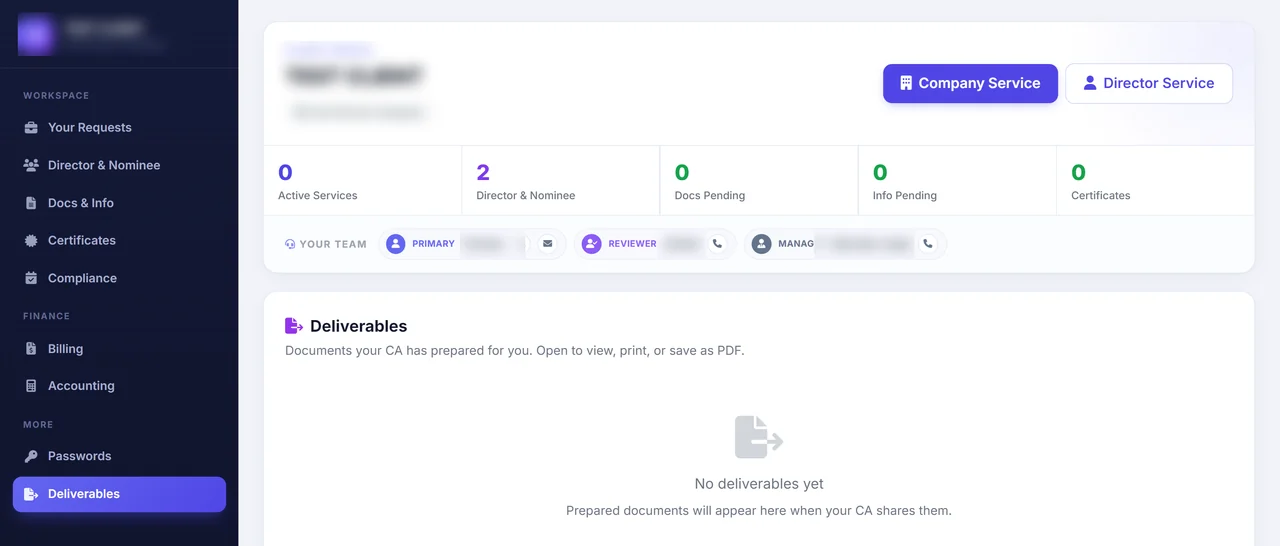
    Everything happens in one secure login. You can see your active services, the Patron team on your account, and anything still pending. Once you raise a request, it moves through the same clear steps every time, so you always know exactly where your work stands.

    Secure client portal login screen
    1

    Sign in securely

    Your books, documents and requests all sit behind one private, password protected login. The team handling your account is shown on screen, so nothing sensitive ever needs to travel over email or WhatsApp.

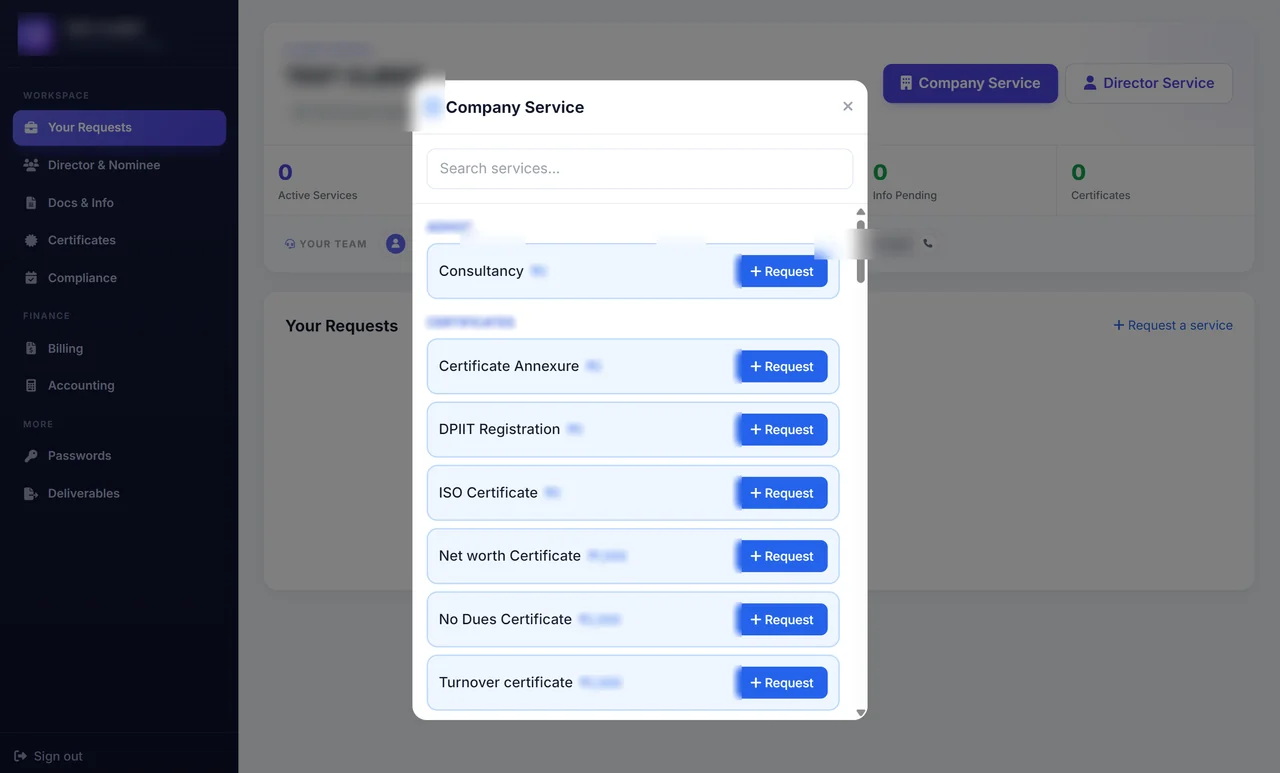
    Service catalogue inside the client portal
    2

    Raise your request

    Choose the service you need from the menu inside the portal, where the price is shown before you go ahead. Your request is logged the moment you send it, with no phone calls or reminder emails to wait on.

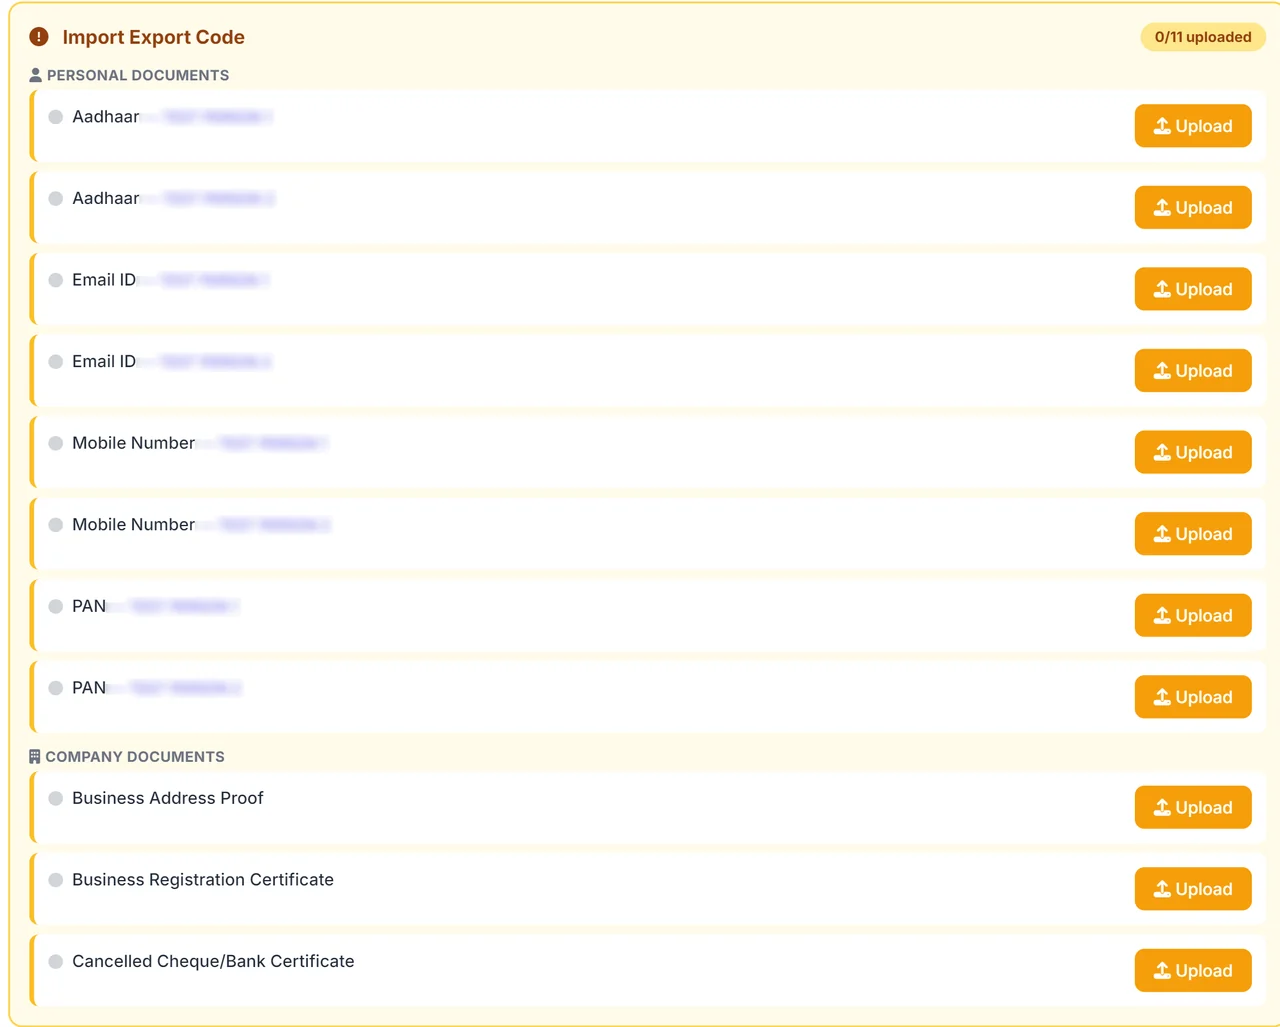
    Import Export Code document checklist in the client portal, with an upload button beside each item
    3

    Share what the service asks for

    For every service, the portal lists the exact documents it needs, each with its own upload button. The example shown here is the Import Export Code checklist. When a service needs nothing from you, it simply asks for nothing.

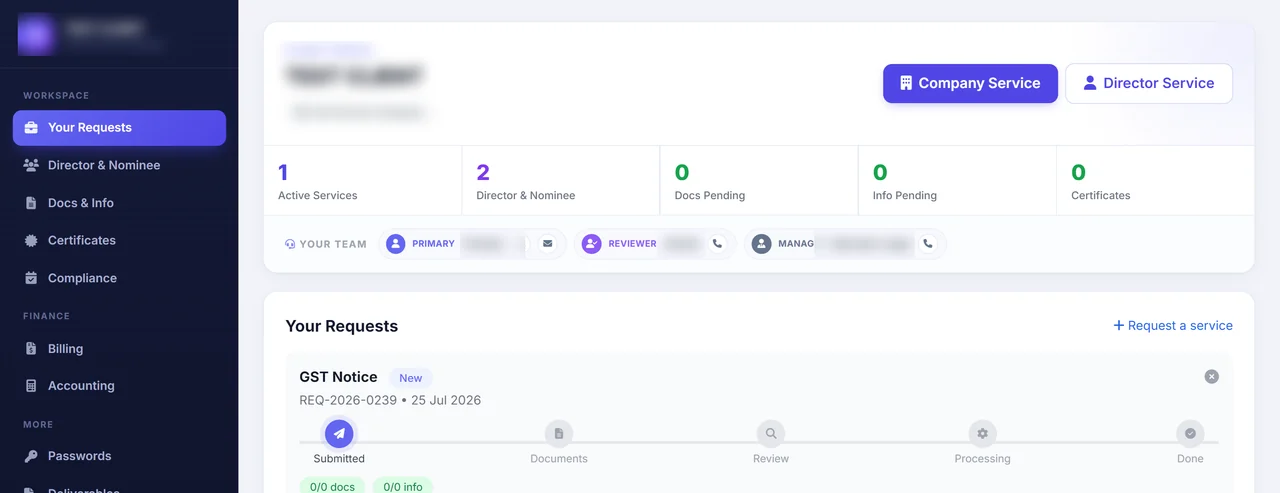
    Live request tracker inside the client portal
    4

    We review, prepare and file

    Once your documents are in, your team checks them, prepares the work and files it for you. A live tracker shows each stage as it happens, from review to processing to done, so you never have to ask where things stand.

    Deliverables area of the client portal
    5

    Collect your finished work

    Every completed return, computation and certificate is placed in your Deliverables area. You can open, print or download any of them as a PDF whenever you need a copy.

    Common Trading Business Accounting Challenges and How We Solve Them

    ChallengeImpactHow Patron Accounting Solves It
    Supplier ledgers carry unadjusted advances, debit notes and rate claimsCreditor balances overstated, duplicate payments slip through, and input credit is lost on mismatches.Reconcile each supplier monthly, clearing advances and claims, to stop losing input tax credit.
    Goods in transit and consignment stock omitted at closeClosing stock understated, so gross profit swings between periods and bank stock statements misreport.Apply a cut-off that captures in-transit and consignment stock with delivery evidence at every close.
    Damaged, expired or slow-moving wholesale stock carried at full costInventory overstated, then a sudden write-off distorts one quarter's profit and the stock-turn ratio.Provide for obsolescence by ageing bucket; value slow stock at net realisable value each close.
    Inward freight and clearing charges expensed, not added to stockCost of goods understated, so margins read better than they are and duty costing is wrong.Apportion inward freight and clearing into inventory cost under AS 2, per consignment.
    Import purchases valued at invoice rate, ignoring duty and forexImported stock cost is wrong and duty-inclusive margin misstated for the import export business.Land each import at invoice plus basic customs duty and the exchange difference to booking date, keeping creditable IGST out of cost.

    Trading Business Accounting Fees

    Fee ComponentAmount
    Starter — one trading entity with routine monthly invoice volumeINR 2,999
    Excl. GST & Government Charges
    Growth — rising purchase and sales invoices with more stock linesOn quote
    Managed — multi-entity or multi-branch books with custom stock reportingOn quote

    Accounting for a trading business is priced by the volume of purchase and sales invoices you raise and the number of stock lines we track. The entry plan suits one entity on routine monthly volume; heavier invoicing or added branches move it up. Speak with an accounting specialist on +91 94594 56700.

    Fees exclude GST and government charges. Final quote confirmed after a scoping review.

    All fees and charges listed are indicative only and do not constitute a binding offer. Final amounts may vary depending on the volume of work and the complexity involved.

    Professional accounting and compliance charges are scoped to your number of entities, funding stage and monthly transaction volume, and are separate from statutory and government charges. Contact us for a detailed, fixed quote.

    Get a free Trading Accounting consultation - Call +91 945 945 6700 or WhatsApp us. No-obligation assessment.

    Trading Business Accounting Compliance Calendar 2026

    ComplianceDue DateApplies To
    TDS / TCS deposit (Challan ITNS-281)7th of every month (30 April for March)Every business that deducts tax at source on salaries, rent, contractor or professional fees
    GSTR-1 (outward supplies)11th of every month for monthly filersGST-registered businesses filing monthly returns
    GSTR-3B (summary return and tax payment)20th of every month for monthly filersGST-registered businesses filing monthly; QRMP filers pay via PMT-06
    MSME-1 half-yearly return on dues to micro and small suppliers30 April 2026 and 31 October 2026Companies with payments to MSME vendors outstanding beyond 45 days
    Advance tax first instalment (15%)15 June 2026Companies, firms and individuals with a tax liability of Rs 10,000 or more
    Tax audit report (Form 3CA/3CB-3CD)30 September 2026Businesses crossing the Section 44AB turnover threshold
    Income-tax return, audit cases31 October 2026Companies and audit-liable firms
    Annual GST return GSTR-9 and reconciliation GSTR-9C31 December 2026GST-registered businesses above the annual-return and audit thresholds

    For a trading business the 11th GSTR-1 and 20th GSTR-3B set the monthly pace, with the tax audit on 30 September once turnover crosses the 44AB line. MSME-1 falls half-yearly. Patron matches your purchase register to GSTR-2B before each trading accounting filing so input credit holds. Request a consultation on +91 94594 56700 to set filing reminders.

    Key Benefits

    Why Professional Trading Business Accounting Matters

    Stock that matches the godown

    Your book stock is agreed location by location: main premises, each declared godown and goods lying with consignees.

    • Stock reconciled per godown and additional place of business
    • Goods with consignees counted separately
    • Without it, shortages surface only at the annual count, after margin was reported

    Margin read by product group

    You get gross margin split by product group and explained: which lines fell, what discounts took, where slow movers tied cash.

    • Gross margin split by product group and explained
    • Scheme discounts and rate differences isolated
    • Without it, a blended margin hides which buying decision to change

    Credit kept, not reversed

    You get a running list of purchase bills unpaid past the point where input tax credit must be reversed. It reaches you in time to act.

    • Supplier-wise matching flags bills unpaid beyond the reversal period
    • Credit returns once the supplier is paid
    • Without it, credit is claimed then reversed later with interest

    Import cost per item

    Every consignment enters the books with duty, freight, insurance and CHA charges in its landed cost per item. Import IGST comes off the Bill of Entry.

    • Duty, freight, insurance and CHA charges in landed cost per item
    • Import IGST claimed off the Bill of Entry
    • Without it, pricing off the supplier invoice sells at a margin never there

    Branch transfers priced correctly

    Stock moving between your own GSTINs goes out on a tax invoice valued against the valuation rule. You confirm the receiving branch took the credit.

    • Inter-state branch transfers invoiced between distinct persons
    • Value holds against the valuation rule; receiving branch credit confirmed
    • Without it, an unsupported outward supply sits at one GSTIN, unclaimed at the other

    Open challans closed off

    We track goods sent to a godown, an exhibition or a customer on approval through to their close, either invoiced or returned.

    • Delivery challans tracked to invoice or return
    • Covers godown, exhibition and approval movements
    • Without it, stock sits elsewhere with no sale and the count disagrees with books

    Why Businesses Choose Patron Accounting for Trading Business Accounting Services

    Five things a founder can check before handing over the books. Each is a claim with the proof behind it.

    Lot-wise stock valued on a consistent cost-or-NRV basis, every close

    We value lot-wise stock at the lower of cost or net realisable value, applied the same way every close. That inventory judgement rests on 15+ years of trading-industry books.

    E-way bill data reconciled back to the sales register

    Reconciling e-way bill and e-invoicing data to the sales register is routine here, one thread in 25,000+ filings completed for Indian traders.

    Multi-godown and multi-state stock in one ledger

    We run Tally Prime, Odoo, Zoho Books and Xero, configuring multi-godown, multi-state stock so every location posts to one ledger.

    Stock and margin report each month, godown by godown

    Every month you get a stock and margin report broken out godown by godown, drawn from the ledger. Consistent delivery like this earns our 4.9 star Google rating.

    Trading and distribution businesses, commodity to FMCG

    Trading and distribution businesses, from commodity dealers to FMCG distributors, are among the 3,000+ businesses served since 2019. Our in-house team of CAs and CS runs their accounting and bookkeeping.

    Figures reflect Patron Accounting LLP engagements since 2019. Scope and turnaround are confirmed in your engagement letter.

    Section 44AD Presumptive vs Regular Books

    CriterionSection 44AD PresumptiveRegular Books
    EligibilityResident trader with turnover up to ₹2 crore, or ₹3 crore if cash is 5% or less.Any trader, and compulsory once turnover exceeds the presumptive limit.
    Income basisIncome deemed at 8% of turnover, or 6% on digital receipts.Actual profit from real sales, purchases, stock and expenses.
    Record-keepingDetailed books not mandatory, though basic records still advisable.Full books, stock records and ledgers must be maintained.
    Tax auditNo 44AB audit while conditions hold and profit is declared at deemed rate.Tax audit u/s 44AB applies once the turnover threshold is crossed.
    MIS clarityNo real margin or stock visibility, so decision-making stays blind.True gross margin, stock and creditor position visible for control.
    Continuity ruleOpting out later locks you out of 44AD for five years.No lock-in; you keep books every year regardless of turnover.
    VerdictPresumptive suits low-margin traders under the turnover limit who value simplicity. Once turnover crosses it, regular books become compulsory and give control, so accounting for trading business should plan the shift. See Section 44AD presumptive for traders.

    Legal and Regulatory Framework for Trading Business Accounting

    A trading margin is thin, and the exchequer's claim on it must be captured without the same rupee being taxed twice: the CGST Act governs the stock and the credit while the Income-tax Act governs the deduction and the collection. The two have to reconcile line by line.

    That reconciliation is the whole discipline. A purchase can carry both a TDS obligation and a supplier's TCS, and a single consignment moves under an e-way bill that must match the invoice it travels with. So GSTR-2B Input Tax Credit Matching and the Section 194Q TDS on Goods check are not optional refinements; they are what stops a notice. Accounting for trading business holds the stock register, the credit ledger and the tax deductions against the provisions below.

    • AS 2 / Ind AS 2, Valuation of InventoriesTraded stock is valued at the lower of cost and net realisable value on a consistent FIFO or weighted-average basis - the choice behind FIFO vs Weighted Average Cost.
    • Section 194Q and Section 206C(1H), Income-tax Act 1961TDS at 0.1% on purchases above Rs 50 lakh, or TCS on sales where the buyer has not deducted, is reconciled so the transaction is taxed only once.
    • Sections 16 and 17, CGST Act 2017Input tax credit is matched to GSTR-2B before it is claimed, and the stock register ties to the outward supplies.
    • Rule 138, CGST Rules 2017An e-way bill supports movement of goods above the notified value and is reconciled against the tax invoice it accompanies.
    • Section 35(1), CGST Act 2017Accounts of inward and outward supplies, stock and tax are kept at the principal place of business for every GSTIN held.
    • Rule 3(1), Companies (Accounts) Rules 2014The audit trail stays enabled, so a rate correction or a landed-cost adjustment is always logged. GST return filing runs from the hub page.

    Official sources: Ministry of Corporate Affairs · Income Tax Department · GST Portal · Startup India (DPIIT)

    What does accounting for a trading or wholesale business include?

    It includes purchase and sales entry, stock ledgers, debtor and creditor reconciliation, GST return workings, TDS, freight and landed cost allocation, monthly gross margin reporting and year end finalisation. For wholesale and distribution clients we also track scheme discounts, credit notes, sales returns and dealer claims, because those are the entries that most often distort the margin you actually report.

    How do you value closing stock for a distribution business?

    Closing stock is valued at the lower of cost and net realisable value under AS 2, with cost including purchase price, inward freight, customs duty and other landed costs but excluding recoverable GST. We agree whether you follow FIFO or weighted average at the start and apply it consistently, since changing method mid year distorts margin and invites an audit query.

    Should a trading firm use Section 44AD presumptive taxation or regular books?

    Presumptive taxation under Section 44AD suits small trading firms below the prescribed turnover limit that want minimal compliance, but it fixes declared profit at a deemed rate and blocks most expense claims. If your actual margin is thin, if you need bank funding, or if you are a company or LLP, regular books usually work out better. We model both before you decide.

    How do you handle import and export entries in the books?

    Import and export entries are recorded at the exchange rate on the transaction date. Landed cost carries basic customs duty, social welfare surcharge, clearing charges and inward freight. IGST paid at import is not a cost, it is booked as input tax credit receivable and matched to your credit ledger. Year end foreign currency balances are revalued and export refund claims tracked separately.

    How do you reconcile hundreds of debtor and creditor ledgers every month?

    Party ledgers are reconciled monthly by importing counterparty statements and matching them line by line, with a formal balance confirmation cycle at year end. Unmatched items are grouped into invoices not booked, payments in transit, discounts and returns, and each group is routed to your sales or purchase team with a due date rather than left sitting in the ledger.

    Which GST returns does a trading business need to file each period?

    A trading business registered under GST files an outward supply return and a summary return for each period, plus the annual return where applicable, and a separate set for every state registration it holds. We prepare the workings, reconcile sales against e-invoice and e-way bill data and match purchases to GSTR-2B before filing, so that eligible credit is not lost.

    What does trading business accounting cost per month?

    Trading business accounting generally costs Rs 10,000 to Rs 40,000 a month, based on the number of invoices, warehouses and GST registrations rather than on turnover. A single state wholesaler with about 300 invoices a month sits at the lower end. Stock valuation support, debtor reconciliation drives and year end finalisation can be added as separate fixed fee modules.

    How are credit notes, discounts and sales returns recorded?

    Credit notes, trade discounts and sales returns are recorded against the original invoice with the GST treatment applied correctly, so your books and your outward supply return tell the same story. Post sale discounts that were not agreed at the time of supply cannot always be adjusted against output tax, so we flag those separately and treat them as a margin item.

    Can you manage books across multiple warehouses and state GST registrations?

    Yes, books are maintained with location wise stock ledgers and a separate return set for each GSTIN. Stock transfers between your own branches are recorded with the correct documentation and valuation, and inter branch balances are reconciled every month so the consolidated accounts eliminate them cleanly instead of carrying a difference into the year end.

    How quickly are gross margin numbers by product available?

    Product wise and category wise gross margin reports arrive with the monthly MIS, normally by the tenth working day after month end. The report shows sales, landed cost, discounts and returns for each product group along with stock cover in days. Where your billing software already tags SKUs, those tags are mapped to the ledger so nothing is entered twice.

    Quick Answers

    Input credit is lost when the purchase register and the supplier's own filing part ways, and the shortfall shows only on close inspection. Patron lists the differences supplier by supplier, separates goods still in transit from bills never uploaded, ties credit notes back to the original invoice and chases what is.

    Trading Accounting Deadlines You Cannot Afford to Miss

    TDS / TCS deposit (Challan ITNS-281) is due 7th of every month (30 April for March). GSTR-1 (outward supplies) is due 11th of every month for monthly filers. GSTR-3B (summary return and tax payment) is due 20th of every month for monthly filers. Patron tracks each against your books so nothing is reconstructed after the fact. Call +91 94594 56700 to set up a filing-reminder schedule.

    Start Your Trading Business Accounting with Patron Accounting

    Closing stock in a trading ledger is often a figure someone agreed to rather than one somebody counted at the godown. Margin by product line is derived from it, the profit shown to your banker rests on it, and next year's buying decisions follow it. Accounting for trading business closes that gap before it compounds.

    Under wholesale accounting services, purchases, sales and stock arrive at the close agreed to one another. Differences that used to surface at the year end are raised in the month they occur, with the supplier still answering emails. The closing figure carried into the next period needs no adjustment.

    The godown list opens the discussion: where stock sits, which addresses are declared, and whether imports use your IEC. Supplier concentration matters too, because two large suppliers who file erratically shape the work differently to many small ones. Any software line sits under our subscription revenue guidance.

    Book a Free Consultation - No Obligation.

    Explore Our Accounting Services

    Related services our CA-led team delivers for businesses across India.

    Reviewed by the CA & CS Team, Patron Accounting LLP
    ICAI & ICSI registered  ·  15+ years in Indian accounting & compliance  ·  Last reviewed 23 July 2026  ·  Next review 23 October 2026